


 |
市場調查報告書
商品編碼
2123600
撒哈拉以南非洲汽車產業:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Sub-Saharan Africa Automotive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
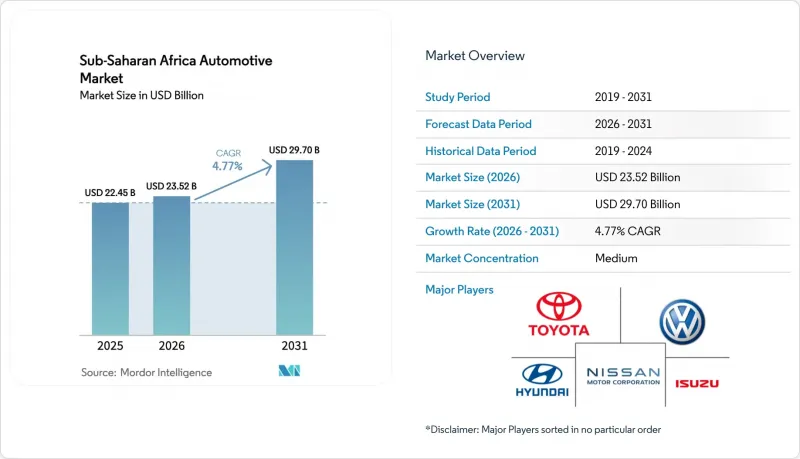
根據 Mordor Intelligence 估計,到 2026 年,撒哈拉以南非洲的汽車市值將達到 235.2 億美元,高於 2025 年的 224.5 億美元。
預計到 2031 年,該產業規模將達到 297 億美元,2026 年至 2031 年的複合年成長率為 4.77%。
本報告按車輛類型(乘用車、輕型商用車等)、燃料類型(汽油、柴油等)、驅動技術(內燃機 (ICE)、混合動力汽車 (HEV) 等)、銷售管道和國家/地區進行細分。市場預測以貨幣價值(美元)和銷售(輛)兩種形式呈現。
撒哈拉以南非洲汽車市場的趨勢與洞察
中產階級收入增加與都市化
隨著城市人口以每年4.1%的速度成長,購買力正向經銷商網路、金融選擇和售後服務更為集中的大都會圈轉移。奈及利亞、肯亞和加納的中等收入家庭傾向於選擇價格適中的車型,而中國和印度汽車製造商之間的競爭也日益激烈。緊湊型SUV和掀背車因其在堵塞道路上的靈活性而備受歡迎,但郊區消費者則依賴於二手車的湧入,而這又得益於都市區不斷成長的以舊換新需求。金融機構也順應勞動力集中趨勢,導致人口超過百萬的都市區提供的汽車貸款產品數量是農村地區的五倍之多。雖然該地貨幣貶值推高了進口汽車的成本,但與資源開採產業相關的薪資成長在一定程度上抵消了價格上漲的壓力,並支撐了需求。
共享出行平台的激增正在加速車輛更替。
像Moove這樣的供應商提供的結構化車輛融資方案,使叫車司機能夠繞過傳統的信用審查障礙,從而提振撒哈拉以南非洲汽車市場多年來的基礎需求。叫車每天運作8-12小時,大約是私家車運作時間的四倍,將車輛更換週期縮短至3-4年。這種可預測的運作節奏使汽車製造商能夠將庫存計劃與平台的採購計劃相匹配,即使在消費者購買力下降的情況下也能確保銷售。預計到2025年,奈及利亞、肯亞和南非的活躍叫車駕駛人總數將超過45萬,隨著平台覆蓋農村地區,潛在需求也將進一步擴大。政府機構越來越認知到這些車輛群體是交通服務正常化的催化劑,衣索比亞和加納已為引入叫車的低排放氣體車輛提供關稅退款。由此帶來的車輛數量成長,緩解了許多市場零售融資覆蓋範圍有限的風險。
在二手車進口領域佔據主導地位
根據非洲汽車製造商協會的數據,2024年撒哈拉以南非洲地區二手車佔所有輕型車輛註冊量的83%。南非稅務局的海關數據顯示,二手和二手車之間45%至60%的價格差異正在影響消費者的購買偏好。由於該地貨幣貶值,新車價格上漲時,這種價格差異會進一步擴大。預計2030年,經濟已開發國家將放鬆對內燃機(ICE)車輛的管制,每年可能增加1,500萬輛汽車的出口能力。除非制定更嚴格的進口品質標準,否則這將導致該地區長期存在大量高排放氣體車輛。儘管聯合國歐洲經濟委員會的《車輛合格性議定書》旨在防止不合格車輛湧入,但由於邊境檢查站執法力度不一致,其有效性仍然有限。
細分市場分析
預計到2025年,乘用車在撒哈拉以南非洲汽車市場整體佔有率將維持在73.80%,並在中產階級壯大的推動下,到2031年將以5.56%的複合年成長率成長。輕型商用車(LCV)受益於電子商務的快速發展,尤其是在奈及利亞和肯亞,兩國的末端配送業者正在租賃專為人口密集的都市區路線最佳化的小型貨車。中型和重型卡車的成長落後於整體市場成長,這與南非、尚比亞和安哥拉的大宗商品出口商業週期密切相關。共乘出行透過系統化的融資方案降低了購車者的初始成本,從而支撐了穩定的乘用車需求,並吸收了轎車和掀背車的庫存。
在衣索比亞,政策主導的電氣化正在重塑乘用車市場格局。一項規定,新註冊車輛中必須有60%為電動車,這推動了專門的電動車組裝企業和公共部門的採購。同時,由於負載容量和續航里程的限制,商用車的電氣化進程相對滯後,儘管約翰內斯堡正在實施試驗計畫,測試純電動貨車在都市區物流中的應用。乘用車市場的持續發展動能仍將取決於整個撒哈拉以南非洲汽車市場的貨幣穩定以及融資管道改革的進展。
預計到2025年,柴油車平台將佔撒哈拉以南非洲汽車市場54.60%的佔有率,這主要得益於其卓越的燃油效率和完善的服務基礎設施,預計到2031年,其複合年成長率將達到6.02%。汽油車在都市區越來越普及,因為那裡的成本差距正在縮小,而排放氣體法規也日益嚴格。諸如壓縮天然氣(CNG)和液化石油氣(LPG)等替代燃料正在特定車隊部署領域獲得市場佔有率,例如奈及利亞的壓縮天然氣(CNG)計劃,該計劃鼓勵計程車和公共汽車進行燃料轉換。在加納和肯亞,利用當地原料生產生質燃料的計畫正在興起,但其推廣取決於政策的穩定性以及對混合設施的投資。
由於建築和礦業車輛需求的成長,撒哈拉以南非洲的柴油動力系統汽車市場正在擴張。然而,隨著電動車(EV)獎勵的訂定,新的需求轉向電動平台,柴油動力汽車的市場佔有率正在逐漸下降。各國政府放寬燃油價格管制的方式也會影響電動車的普及速度。那些較早取消柴油補貼的國家可能會加速汽油和混合動力汽車的普及。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 中產階級收入增加與都市化
- 共享出行平台的激增正在加速車輛的更替。
- 政府對CKD/SKD組裝的獎勵措施
- 基礎設施建設改善了道路連通性。
- 非洲大陸自由貿易區(AfCFTA)下的關稅減讓將擴大區域內貿易。
- 中國微型電動車進口量的成長正在填補超低價車的市場空白。
- 市場限制因素
- 在二手車進口領域佔據主導地位
- 消費貸款獲取限制和高利率
- 該地貨幣波動推高了進口成本。
- 撒哈拉以南非洲地區型式認可標準的差異
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 車輛類型
- 搭乘用車
- 輕型商用車
- 中型和大型商用車輛
- 按燃料類型
- 汽油
- 柴油引擎
- 替代燃料(壓縮天然氣、液化石油氣、生質燃料)
- 透過推進技術
- 內燃機(ICE)
- 混合動力電動車(HEV)
- 電池式電動車(BEV)
- 插電式混合動力車(PHEV)
- 按銷售管道
- OEM(原廠設備製造商)- 授權經銷商
- 灰色進口/平行進口
- 國家
- 南非
- 奈及利亞
- 肯亞
- 衣索比亞
- 迦納
- 坦尚尼亞
- 安哥拉
- 尚比亞
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Toyota Motor Corporation
- Volkswagen AG
- Hyundai Motor Company
- Nissan Motor Corporation
- Isuzu Motors Ltd.
- Ford Motor Company
- Groupe Renault
- Honda Motor Corporation
- Suzuki Motor Corporation
- Subaru Corporation
- Stellantis NV
- Daimler AG(Mercedes-Benz)
- BYD Co.
- Geely Auto Group
- Changan Auto
- JAC Motors
- BAIC Group
- Tata Motors
- Mahindra & Mahindra
- Innoson Vehicle Manufacturing(Nigeria)
第7章 市場機會與未來展望
According to Mordor Intelligence, the Sub-Saharan Africa automotive market size in 2026 is estimated at USD 23.52 billion, growing from the 2025 value of USD 22.45 billion, with projections for 2031 showing USD 29.7 billion, representing a 4.77% CAGR over the 2026-2031 period.
This report is Segmented by Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Fuel Type (Gasoline, Diesel, and More), Propulsion Technology (Internal Combustion Engine (ICE), Hybrid Electric Vehicle (HEV), and More), Sales Channel, and Country. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Sub-Saharan Africa Automotive Market Trends and Insights
Rising Middle-Class Income and Urbanization
An annual 4.1% urban-population uptick shifts purchasing power toward metropolitan nodes where dealer networks, financing options, and aftermarket services coalesce. Middle-income households in Nigeria, Kenya, and Ghana gravitate towards affordable models, intensifying competition between Chinese and Indian OEMs. Compact SUVs and hatchbacks hold favor for maneuverability in congested corridors, whereas peri-urban consumers rely on incoming used stock propelled by rising urban trade-in flows. Lenders follow employment clusters, resulting in cities above 1 million inhabitants offering up to five times more car-loan products than rural districts. Although local-currency depreciation erodes import affordability, wage growth linked to extractive sectors partially offsets price pressure, sustaining demand.
Surge of Ride-Hailing Platforms Accelerating Fleet Renewal
Structured fleet-financing programs from providers such as Moove enable ride-hailing drivers to bypass conventional credit hurdles, lifting multi-year baseline demand for the Sub-Saharan Africa automotive market. Ride-hailing vehicles operate 8-12 hours daily, roughly quadrupling private-use utilization, which shortens replacement cycles to 3-4 years. This predictable cadence enables OEMs to align inventory planning with platform procurement schedules, thereby protecting volumes when consumer sentiment declines. Nigeria, Kenya, and South Africa collectively host over 450,000 active ride-hailing drivers as of 2025, and platform expansion into secondary cities deepens the addressable demand. Government agencies increasingly recognize such fleets as catalysts for formalizing transport services, offering duty rebates on low-emission vehicles deployed for ride-hailing in Ethiopia and Ghana. Resultant fleet growth moderates the risk of limited retail financing reach in many markets.
Dominance of Used-Car Imports
Used vehicles represented 83% of all light-duty vehicle registrations across Sub-Saharan Africa in 2024, according to the African Association of Automotive Manufacturers . South African Revenue Service customs data show that price gaps of 45-60% between used and new models tilt buyer preference. This disparity is magnified whenever local-currency depreciation inflates showroom prices. Projected deregistrations of ICE cars in wealthier economies could add 15 million exportable units annually by 2030, prolonging the region's high-emission fleet unless stricter import-quality rules take hold. UNECE roadworthiness protocols aim to stem sub-standard flows, but uneven enforcement across border posts still dilutes effectiveness.
Other drivers and restraints analyzed in the detailed report include:
- Government CKD/SKD Assembly Incentives
- Infrastructure Upgrades Improving Road Connectivity
- Limited Consumer Credit Access and High Interest Rates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars preserved a 73.80% share of the Sub-Saharan Africa automotive market volume in 2025 and are forecast to grow at a 5.56% CAGR through 2031, as middle-income cohorts expand. Light commercial vehicles (LCVs) benefit from e-commerce acceleration, especially in Nigeria and Kenya, where last-mile delivery providers lease small vans optimized for dense urban routes. Medium- and heavy-duty trucks trail the overall market growth, tied to commodity-export cycles in South Africa, Zambia, and Angola. Ride-hailing fleets underpin steady passenger-car demand, absorbing sedan and hatchback stock through structured financing programs that lower upfront cost burdens.
Policy-driven electrification in Ethiopia reshapes the passenger-car mix: 60% of newly registered cars must be EVs, catalyzing dedicated assembly ventures and public-sector procurement. Conversely, commercial-vehicle electrification lags due to payload-range constraints, although pilot programs in Johannesburg are testing battery-electric vans under urban logistics duty cycles. Sustained momentum within the passenger-car segment remains contingent on currency stability and progressive credit-access reforms across the Sub-Saharan Africa automotive market.
Diesel platforms held a 54.60% share of the Sub-Saharan Africa automotive market volume in 2025, buoyed by superior fuel economy and extensive service infrastructure, and they are projected to post a 6.02% CAGR through 2031. Gasoline penetration increases in urban centers where cost gaps narrow, and emissions policies become stricter. Alternative fuels, such as CNG and LPG, capture niche fleet deployments, as highlighted by Nigeria's compressed natural gas scheme, which incentivizes taxi and bus conversions. Biofuel initiatives are germinating in Ghana and Kenya, utilizing local feedstocks, but scaling up hinges on policy consistency and investment in blending facilities.
The Sub-Saharan African automotive market size for diesel powertrains expands alongside demand for construction and mining vehicles. Yet, its share gradually erodes as EV incentives redirect incremental demand toward electrified platforms. Government fuel-price deregulation trajectories also influence adoption curves; countries that phase out diesel subsidies sooner may prompt faster adoption of gasoline or hybrids.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- By Fuel Type
- Gasoline
- Diesel
- Alternative Fuels (CNG, LPG, Bio-fuel)
- By Propulsion Technology
- Internal Combustion Engine (ICE)
- Hybrid Electric Vehicle (HEV)
- Battery Electric Vehicle (BEV)
- Plug-in Hybrid Electric Vehicle (PHEV)
- By Sales Channel
- Original Equipment Manufacturer (OEM)-Authorized Dealer
- Grey Import / Parallel
- By Country
- South Africa
- Nigeria
- Kenya
- Ethiopia
- Ghana
- Tanzania
- Angola
- Zambia
List of Companies Covered in this Report:
- Toyota Motor Corporation
- Volkswagen AG
- Hyundai Motor Company
- Nissan Motor Corporation
- Isuzu Motors Ltd.
- Ford Motor Company
- Groupe Renault
- Honda Motor Corporation
- Suzuki Motor Corporation
- Subaru Corporation
- Stellantis N.V.
- Daimler AG (Mercedes-Benz)
- BYD Co.
- Geely Auto Group
- Changan Auto
- JAC Motors
- BAIC Group
- Tata Motors
- Mahindra & Mahindra
- Innoson Vehicle Manufacturing (Nigeria)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Middle-Class Income and Urbanization
- 4.2.2 Surge of Ride-Hailing Platforms Accelerating Fleet Renewal
- 4.2.3 Government CKD/SKD Assembly Incentives
- 4.2.4 Infrastructure Upgrades Improving Road Connectivity
- 4.2.5 AfCFTA Tariff Reductions Expanding Intra-Regional Trade
- 4.2.6 Growth of Chinese Micro-EV Imports Filling Ultra-Low-Cost Niche
- 4.3 Market Restraints
- 4.3.1 Dominance of Used-Car Imports
- 4.3.2 Limited Consumer Credit Access and High Interest Rates
- 4.3.3 Local-Currency Volatility Inflating Import Costs
- 4.3.4 Fragmented Homologation Standards Across SSA
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Light Commercial Vehicles
- 5.1.3 Medium and Heavy Commercial Vehicles
- 5.2 By Fuel Type
- 5.2.1 Gasoline
- 5.2.2 Diesel
- 5.2.3 Alternative Fuels (CNG, LPG, Bio-fuel)
- 5.3 By Propulsion Technology
- 5.3.1 Internal Combustion Engine (ICE)
- 5.3.2 Hybrid Electric Vehicle (HEV)
- 5.3.3 Battery Electric Vehicle (BEV)
- 5.3.4 Plug-in Hybrid Electric Vehicle (PHEV)
- 5.4 By Sales Channel
- 5.4.1 Original Equipment Manufacturer (OEM)-Authorized Dealer
- 5.4.2 Grey Import / Parallel
- 5.5 By Country
- 5.5.1 South Africa
- 5.5.2 Nigeria
- 5.5.3 Kenya
- 5.5.4 Ethiopia
- 5.5.5 Ghana
- 5.5.6 Tanzania
- 5.5.7 Angola
- 5.5.8 Zambia
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Toyota Motor Corporation
- 6.4.2 Volkswagen AG
- 6.4.3 Hyundai Motor Company
- 6.4.4 Nissan Motor Corporation
- 6.4.5 Isuzu Motors Ltd.
- 6.4.6 Ford Motor Company
- 6.4.7 Groupe Renault
- 6.4.8 Honda Motor Corporation
- 6.4.9 Suzuki Motor Corporation
- 6.4.10 Subaru Corporation
- 6.4.11 Stellantis N.V.
- 6.4.12 Daimler AG (Mercedes-Benz)
- 6.4.13 BYD Co.
- 6.4.14 Geely Auto Group
- 6.4.15 Changan Auto
- 6.4.16 JAC Motors
- 6.4.17 BAIC Group
- 6.4.18 Tata Motors
- 6.4.19 Mahindra & Mahindra
- 6.4.20 Innoson Vehicle Manufacturing (Nigeria)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 拉丁美洲汽車產業的成長機會,2026年推動全球汽車市場發展的關鍵趨勢:2026 年展望
 南美汽車市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)非洲汽車產業:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)北美汽車市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2034年汽車銷售市場預測-按車輛類型、驅動方式、所有權類型、價格範圍、自動化程度、銷售管道和地區分類的全球分析
 2026年全球汽車市場報告中國汽車市場展望(2026年)2026年東協汽車產業的成長機遇
 越南汽車塗料市場(2025)