


 |
市場調查報告書
商品編碼
2121881
南美汽車市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)South America Automotive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
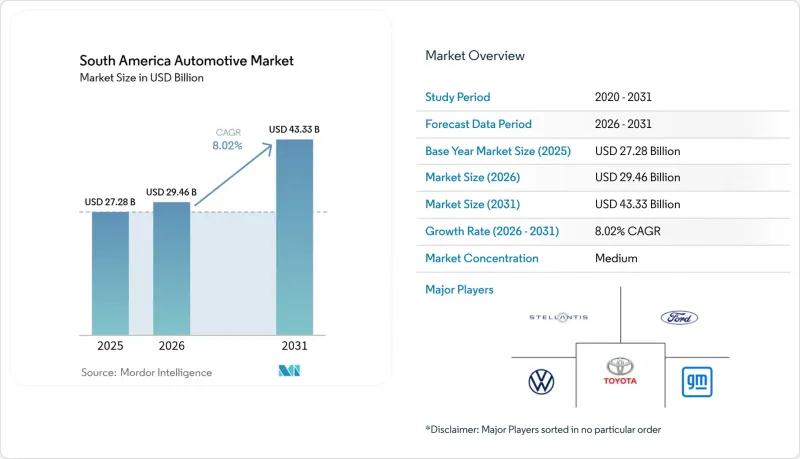
根據 Mordor Intelligence 預測,南美汽車市場規模將從 2025 年的 272.8 億美元成長到 2026 年的 294.6 億美元,然後在 2031 年達到 433.3 億美元,2026 年至 2031 年的複合年成長率為 8.02%。
本報告按車輛類型(乘用車、商用車、摩托車、非公路用車)、驅動方式(內燃機車輛和電動車)、銷售管道(OEM/直銷、經銷商/零售、其他)、最終用戶(個人/私人用戶、中小企業車隊、其他)和國家/地區進行細分。市場預測以美元計價。
南美洲汽車市場趨勢與洞察
OEM廠商對區域汽車平臺的投資
在南美,由於傳統汽車和電動車銷量成長,以及大眾汽車集團和Stellantis NV等主要廠商活性化投資,汽車產業的盈利正在提升。光是Stellantis就投資了56億歐元,創下該地區歷史上單筆投資額的最高紀錄。大眾汽車集團已為其位於阿根廷的「Amaroc」計畫撥款5.8億美元,該計畫旨在適應當地的使用條件。同時,豐田汽車和寶馬集團也宣布了未來多年專注於混合動力和靈活燃料動力系統的業務擴張計劃。通用汽車與現代汽車的合作項目等,將涵蓋五款車型,目標年銷量為80萬輛,這標誌著企業正朝著成本共用和加快產品推出週期的方向發展。這些區域性平台透過降低外匯風險、滿足區域監管標準以及利用南方共同市場的關稅優惠,全面提升了南美汽車市場的競爭力。
疫情後GDP復甦與消費信貸擴張
預計到2025年,該地區GDP將年增1.9%至2.5%,主要受家庭收入成長和汽車貸款需求增加的推動,儘管基準利率持續高企。巴西經濟預計在2024年成長3.4%,失業率維持在6.5%,為購車創造了有利環境。阿根廷的改革已將月通膨率降至2.8%,為購車者開闢了新的融資管道;哥倫比亞的製造業產出逐年成長,提振了南美汽車市場的發展動能。儘管資金籌措成本仍然較低,但隨著大多數央行繼續放鬆貨幣政策,貸款取得的便利性預計將逐步改善。宏觀經濟基本面的改善預計將在2025年全年推動展示室客流量和累積訂單的增加。
高貸款利率和通貨膨脹推高了汽車價格。
預計巴西的法定所得稅率(selic)將在2025年升至14.25%,這將推高汽車貸款利率,加重購車負擔。儘管阿根廷的通膨有所緩解,但披索的波動導致貸款利差依然較大,而區域貨幣的波動也使進口價格前景不明朗。目前,汽車製造商正在提供延長還款期限和利率補貼,但信貸利用率仍低於疫情前水準。因此,在金融狀況好轉之前,南美汽車市場的短期銷售量可能會低於預期水準。
細分市場分析
到2025年,乘用車將佔南美汽車市場的73.68%,預計到2031年將以11.95%的複合年成長率成長,這主要得益於都市化加快和中產階級收入提高。 SUV和跨界車因其較高的駕駛位置和良好的安全性而成為市場需求的主要驅動力,而緊湊型轎車憑藉其燃油效率,即使在汽油價格上漲的情況下也能保持一定的市場佔有率。商用車雖然銷量較小,但卻為主要農業和礦業路線的物流運輸提供了支持;小型皮卡在巴西農場更受歡迎,而大型卡車則支撐著智利的銅出口。摩托車作為一種經濟實惠的交通工具,在擁擠的大都市中迅速普及,而受公共工程支出的推動,非公路用車市場也在成長。
Stellantis計劃在2030年推出40多款新車型,其中許多車型將採用在地化平台,並與靈活燃料驅動系統,這將進一步推動乘用車市場的發展動能。此外,融資優惠政策旨在緩解貸款利率上升的不利影響,否則利率上升將導致展示室客流量下降。同時,二手車數位化平台正在提高置換流動性,降低實際更換成本,並維持銷售周轉率。這些車型陣容凸顯了南美洲汽車市場如何平衡個人交通需求和商務傳輸需求。
預計2025年,內燃機汽車仍將佔據南美汽車市場72.95%的佔有率。然而,在財政獎勵和中國本地化生產縮小價格差距的推動下,電池式電動車( EV)正以11.15%的複合年成長率快速成長。巴西的E30計劃在確保其與靈活燃料引擎的成本競爭力方面發揮著重要作用,該計劃減少了汽油進口,同時增加了國內對乙醇的需求。混合動力汽車發揮橋樑作用,尤其是相容於乙醇的車型,與汽油車相比,其排放量減少了更多。
柴油車在綿延數千公里的長途運輸路線上仍然發揮著至關重要的作用,而壓縮天然氣(CNG)則主要用於市政車輛等加氣網路完善的細分領域。燃料電池的研發仍處於起步階段,但隨著現代汽車宣佈在巴西投資11億美元發展氫能的藍圖,燃料電池正日益受到關注。預計到2026年,C級純電動車(BEV)的進口關稅將提高至35%,屆時,本地馬達和電池工廠的運作將有助於維持電動車的價格優勢,加速其普及,並逐步改變南美汽車市場的動力系統格局。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 疫情後GDP復甦與消費貸款供應擴張
- 巴西擴大對彈性燃料汽車的優惠待遇
- OEM廠商對區域汽車平臺的投資
- 中國汽車製造商利用南方共同市場的關稅優惠建造待開發區電動車工廠
- 利用數位技術的二手二手平台正在加速以舊換新的機會。
- 利用礦業特許權使用費補貼購買電動車
- 市場限制因素
- 高額資金籌措利率和通貨膨脹推高了汽車價格。
- 本地組裝用半導體供應的波動
- 由於港口堵塞,CKD套件和電池的進口被延誤。
- 消費者對城際充電網路可靠性的不信任
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 車輛類型
- 搭乘用車
- 掀背車
- 轎車
- SUV 與跨界車
- MPV
- 商用車輛
- 小型商用皮卡
- 小型商用貨車
- 大型卡車
- 巴士和長途汽車
- 摩托車
- 摩托車
- 踏板車/輕型機踏車
- 非公路用車輛
- 農用曳引機
- 工程機械
- 搭乘用車
- 依推進類型
- 內燃機(ICE)
- 汽油
- 柴油引擎
- 彈性燃料(乙醇)
- 天然氣(CNG/LNG)
- 電動車
- 電池式電動車(BEV)
- 混合動力汽車(HEV)
- 插電式混合動力汽車(PHEV)
- 燃料電池汽車(FCEV)
- 內燃機(ICE)
- 按銷售管道
- OEM/直銷
- 經銷商和零售
- 向車隊和企業客戶銷售
- 線上直接面對消費者
- 最終用戶
- 個人/一般消費者
- 中小企業車隊
- 大型企業擁有車輛
- 政府和地方政府車輛
- 出行業者(叫車、共乘)
- 國家
- 巴西
- 阿根廷
- 智利
- 秘魯
- 哥倫比亞
- 厄瓜多
- 其他南美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Stellantis NV
- Volkswagen AG
- General Motors Company
- Toyota Motor Corporation
- Ford Motor Company
- Hyundai Motor Company
- Nissan Motor Co. Ltd.
- Honda Motor Co. Ltd.
- Renault SA
- Mercedes-Benz Group AG
- Kia Corporation
- BYD Company Limited
- Chery Automobile Co. Ltd.
- Great Wall Motor Co. Ltd.
- Geely Automobile Holdings
- BMW AG
- Volvo Car AB
第7章 市場機會與未來展望
According to Mordor Intelligence, the south american automotive market size is expected to grow from USD 27.28 billion in 2025 to USD 29.46 billion in 2026 and is forecast to reach USD 43.33 billion by 2031 at 8.02% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Passenger Cars, Commercial Vehicles, Two-Wheelers, and Off-Highway Vehicles), Propulsion Type (Internal-Combustion Engine and Electrified Vehicles), Sales Channel (OEM/Direct, Dealer/Retail, and More), End User (Individual/Private, SME Fleets, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
South America Automotive Market Trends and Insights
OEM Investments in Regional Vehicle Platforms
In South America, growing sales of traditional and electrified vehicles and heightened investments from major players like Volkswagen AG and Stellantis NV have increased profitability. Stellantis alone invested EUR 5.6 billion, the most significant single commitment in regional history . Volkswagen AG allocated USD 580 million to an Argentina-based Amarok program tailored to local duty-cycle needs. At the same time, Toyota Motor and BMW Group announced multi-year expansions focusing on hybrid and flex-fuel drivetrains. Joint projects such as the GM-Hyundai collaboration covering five models and targeting 800,000 annual sales illustrate a pivot toward shared cost structures and accelerated product cadence. These localized platforms reduce currency risk, meet regional regulatory norms, and leverage Mercosur tariff preferences, collectively enhancing the competitiveness of the South American automotive market.
Post-Pandemic Rebound in GDP and Consumer Credit Availability
Regional GDP is projected to increase by 2.5% in 2025, up from 1.9% the previous year, which is expected to lift household incomes and stimulate automotive lending, even as benchmark rates remain elevated . Brazil's economy expanded by 3.4% in 2024, with an unemployment rate of 6.5%, creating a supportive backdrop for vehicle purchases. Argentina's reforms have cut monthly inflation to 2.8%, unlocking new credit channels for auto buyers, while Colombia's manufacturing output is growing annually, reinforcing the momentum in the South American automotive market. Although financing costs remain restrained, easing monetary conditions across most central banks should gradually revive loan accessibility. Stronger macroeconomic fundamentals are expected to translate into higher showroom traffic and order backlogs throughout 2025.
Elevated Financing Rates and Inflation-Driven Vehicle Prices
Brazil's Selic rate climbed to 14.25% in 2025, pushing automotive loan coupons as high as and squeezing affordability. Although Argentina's inflation has moderated, peso volatility keeps lending spreads wide, while regional currency fluctuations cloud import-price visibility. OEMs now offer tenures and subsidized rates, but credit penetration still lags pre-pandemic norms. Consequently, near-term volumes in the South American automotive market may undershoot potential until monetary conditions ease.
Other drivers and restraints analyzed in the detailed report include:
- Chinese OEM Green-Field EV Plants Using Mercosur Tariff Breaks
- Digitally Enabled Used-Car Platforms Boosting Trade-Ins
- Semiconductor Supply Volatility for Local Assembly
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars accounted for 73.68% of the South American automotive market size in 2025 and are projected to expand at a 11.95% CAGR through 2031, benefiting from rising urbanization and middle-class income gains. SUVs and crossovers lead the surge, prized for higher seating positions and perceived safety, whereas compact sedans preserve a foothold due to fuel efficiency at premium pump prices. Though smaller in unit terms, commercial vehicles underpin logistics in agriculture and mining corridors, with light pickups favored by Brazilian farms and heavy trucks powering Chilean copper exports. Two-wheelers are proliferating in congested megacities as cost-effective mobility, while off-highway equipment enjoys tailwinds from public works spending.
The passenger-car momentum is reinforced by Stellantis' plan to launch more than 40 new products by 2030, many of them on localized platforms geared to flexible-fuel drivetrains. Financing promotions aim to mitigate loan-rate headwinds that otherwise dampen showroom traffic. Meanwhile, used-car digital platforms improve trade-in liquidity, lowering the effective upgrade cost and sustaining turnover. The vehicle-type mix underscores how the South American automotive market balances personal-mobility aspirations with commercial transport imperatives.
Internal-combustion engines retained 72.95% of the South American automotive market in 2025; however, battery electrics are accelerating at a 11.15% CAGR as fiscal incentives and localized Chinese production narrow the price gaps. Brazil's E30 scheme provides a cost-parity hedge for flex-fuel engines, reducing gasoline imports and increasing domestic ethanol demand. Hybrids serve as a bridge technology, especially ethanol-compatible variants that achieve greater emission reductions compared to gasoline equivalents.
Diesel retains relevance in heavy-duty routes that span thousands of kilometers, while CNG finds niche use in municipal fleets where refueling networks exist. Fuel-cell exploration is nascent but gaining attention following Hyundai's USD 1.1 billion hydrogen roadmap for Brazil. As import tariffs on C-segment BEVs rise to 35% by 2026, localized motor and battery plants are expected to protect affordability and accelerate adoption, gradually shifting the propulsion landscape of the South American automotive market.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Hatchbacks
- Sedans
- SUVs and Crossovers
- MPVs
- Commercial Vehicles
- Light Commercial Pick-ups
- Light Commercial Vans
- Heavy Trucks
- Buses and Coaches
- Two-Wheelers
- Motorcycles
- Scooters/Mopeds
- Off-Highway Vehicles
- Agricultural Tractors
- Construction Equipment
- Passenger Cars
- By Propulsion Type
- Internal-Combustion (ICE)
- Gasoline
- Diesel
- Flexible-Fuel (Ethanol)
- Natural Gas (CNG/LNG)
- Electrified Vehicles
- Battery-Electric (BEV)
- Hybrid Electric (HEV)
- Plug-in Hybrid (PHEV)
- Fuel-Cell (FCEV)
- Internal-Combustion (ICE)
- By Sales Channel
- OEM / Direct Sales
- Dealer and Retail Sales
- Fleet and Corporate Sales
- Online Direct-to-Consumer
- By End User
- Individual / Private Consumers
- Small and Medium Enterprise Fleets
- Large Corporate Fleets
- Government and Municipal Fleets
- Mobility Operators (Ride-hailing, Car-sharing)
- By Country
- Brazil
- Argentina
- Chile
- Peru
- Colombia
- Ecuador
- Rest of South America
List of Companies Covered in this Report:
- Stellantis NV
- Volkswagen AG
- General Motors Company
- Toyota Motor Corporation
- Ford Motor Company
- Hyundai Motor Company
- Nissan Motor Co. Ltd.
- Honda Motor Co. Ltd.
- Renault S.A.
- Mercedes-Benz Group AG
- Kia Corporation
- BYD Company Limited
- Chery Automobile Co. Ltd.
- Great Wall Motor Co. Ltd.
- Geely Automobile Holdings
- BMW AG
- Volvo Car AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-Pandemic Rebound in GDP and Consumer Credit Availability
- 4.2.2 Expansion of Flexible-Fuel Incentives in Brazil
- 4.2.3 OEM Investments in Regional Vehicle Platforms
- 4.2.4 Chinese OEM Green-Field EV Plants Using Mercosur Tariff Breaks
- 4.2.5 Digitally Enabled Used-Car Platforms Boosting Trade-Ins.
- 4.2.6 Mining-Royalty Funded EV Purchase Subsidies
- 4.3 Market Restraints
- 4.3.1 Elevated Financing Rates and Inflation-Driven Vehicle Prices
- 4.3.2 Semiconductor Supply Volatility for Local Assembly
- 4.3.3 Port Congestion Delaying CKD Kits and Battery Imports
- 4.3.4 Consumer Distrust in Inter-City Charging-Network Reliability
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.1.1 Hatchbacks
- 5.1.1.2 Sedans
- 5.1.1.3 SUVs and Crossovers
- 5.1.1.4 MPVs
- 5.1.2 Commercial Vehicles
- 5.1.2.1 Light Commercial Pick-ups
- 5.1.2.2 Light Commercial Vans
- 5.1.2.3 Heavy Trucks
- 5.1.2.4 Buses and Coaches
- 5.1.3 Two-Wheelers
- 5.1.3.1 Motorcycles
- 5.1.3.2 Scooters/Mopeds
- 5.1.4 Off-Highway Vehicles
- 5.1.4.1 Agricultural Tractors
- 5.1.4.2 Construction Equipment
- 5.1.1 Passenger Cars
- 5.2 By Propulsion Type
- 5.2.1 Internal-Combustion (ICE)
- 5.2.1.1 Gasoline
- 5.2.1.2 Diesel
- 5.2.1.3 Flexible-Fuel (Ethanol)
- 5.2.1.4 Natural Gas (CNG/LNG)
- 5.2.2 Electrified Vehicles
- 5.2.2.1 Battery-Electric (BEV)
- 5.2.2.2 Hybrid Electric (HEV)
- 5.2.2.3 Plug-in Hybrid (PHEV)
- 5.2.2.4 Fuel-Cell (FCEV)
- 5.2.1 Internal-Combustion (ICE)
- 5.3 By Sales Channel
- 5.3.1 OEM / Direct Sales
- 5.3.2 Dealer and Retail Sales
- 5.3.3 Fleet and Corporate Sales
- 5.3.4 Online Direct-to-Consumer
- 5.4 By End User
- 5.4.1 Individual / Private Consumers
- 5.4.2 Small and Medium Enterprise Fleets
- 5.4.3 Large Corporate Fleets
- 5.4.4 Government and Municipal Fleets
- 5.4.5 Mobility Operators (Ride-hailing, Car-sharing)
- 5.5 By Country
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Chile
- 5.5.4 Peru
- 5.5.5 Colombia
- 5.5.6 Ecuador
- 5.5.7 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.4.1 Stellantis NV
- 6.4.2 Volkswagen AG
- 6.4.3 General Motors Company
- 6.4.4 Toyota Motor Corporation
- 6.4.5 Ford Motor Company
- 6.4.6 Hyundai Motor Company
- 6.4.7 Nissan Motor Co. Ltd.
- 6.4.8 Honda Motor Co. Ltd.
- 6.4.9 Renault S.A.
- 6.4.10 Mercedes-Benz Group AG
- 6.4.11 Kia Corporation
- 6.4.12 BYD Company Limited
- 6.4.13 Chery Automobile Co. Ltd.
- 6.4.14 Great Wall Motor Co. Ltd.
- 6.4.15 Geely Automobile Holdings
- 6.4.16 BMW AG
- 6.4.17 Volvo Car AB
7 Market Opportunities & Future Outlook

 拉丁美洲汽車產業的成長機會,2026年推動全球汽車市場發展的關鍵趨勢:2026 年展望
 撒哈拉以南非洲汽車產業:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)非洲汽車產業:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)北美汽車市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2034年汽車銷售市場預測-按車輛類型、驅動方式、所有權類型、價格範圍、自動化程度、銷售管道和地區分類的全球分析
 2026年全球汽車市場報告中國汽車市場展望(2026年)2026年東協汽車產業的成長機遇
 越南汽車塗料市場(2025)