


 |
市場調查報告書
商品編碼
2123413
英國設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)United Kingdom (UK) Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
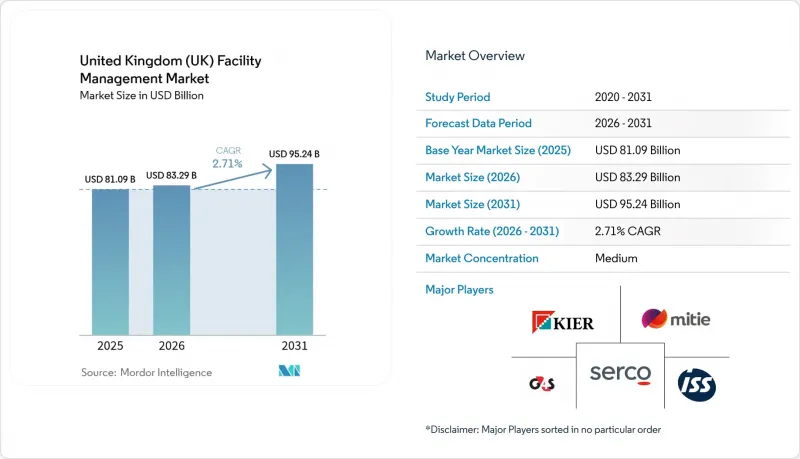
據 Mordor Intelligence 稱,2025 年英國物業管理市場價值為 810.9 億美元,預計到 2031 年將達到 952.4 億美元,而 2026 年為 832.9 億美元,預測期(2026-2031 年)的複合年成長率為 2.71%。
本報告按服務類型(硬性服務、軟性服務)、交付方式(內部交付、外包)和最終用戶行業(商業、酒店、公共基礎設施、醫療保健、工業/流程以及其他最終用戶行業)進行分類。市場預測以美元計價。
英國設施管理市場的趨勢與洞察
技術整合(物聯網、人工智慧、自動化)
人工智慧驅動的建築管理平台正在重新定義服務的交付方式。例如,智慧財產局在實施數位化工單入口網站後,將維護回應時間從14天縮短至幾秒鐘。智慧感測器即時傳輸人員佔用率、溫度和空氣品質數據,使服務供應商能夠從被動維護轉向預測性維護,降低能耗並提升員工舒適度。世邦魏理仕進軍超級大規模資料中心設施管理市場,凸顯了需要全天候分析監控的細分市場蘊藏的高利潤潛力。醫療保健和教育行業的客戶正在引領這一趨勢,因為法令遵循要求持續進行環境監測。隨著數位化儀錶板整合軟性服務和硬性服務,服務提供者將清潔、保全、辦公室支援和資產維護打包到資料豐富的合約中,從而能夠獲得更高的價格。
商業不動產的快速擴張
根據英國英國特許測量師學會 (RICS) 的數據,預計租戶需求將在 2025 年第一季轉正,倫敦市中心黃金地段的辦公大樓租金預計將以每年近 5% 的速度成長。工業資產的投資需求最強勁,受電子商務和近岸外包的推動,投資者需求淨成長 18%。隨著新開發項目的增加,對試運行、全生命週期資產管理和持續合規審計的需求也日益成長。與開發商及早合作的設施管理人員可以從智慧化、即用型建築的運作就獲得多年穩定的收入來源,這些建築還整合了 ESG(環境、社會和治理)儀錶板。同樣,物流行業的成長也推動了對高容量倉庫客製化設施管理方案的需求,這些方案結合了庫存追蹤技術、碼頭管理和先進的消防設備維護。
人手不足和技能缺口
自英國脫歐以來,飯店、清潔和餐飲業已出現13.2萬個工作機會的缺口,對設施管理(FM)人員配備帶來壓力。 2025年移民白皮書將技術純熟勞工簽證的要求提高到RQF 6級,限制了外籍員工在入門級設施管理職位上的招募。自2005年以來,雇主在培訓方面的投入下降了28%,而技能短缺恰逢建築開始採用先進數位系統之際。企業正在透過供電督導培訓項目來應對這項挑戰,例如Samsic JPC的12模組「下一代」項目,該項目專注於領導力和技術技能的培養。然而,高離職率和勞動力老化仍然限制著該產業的產能。
細分市場分析
到2025年,硬性服務將佔英國設施管理市場佔有率的60.12%,這主要得益於英國國民醫療服務體系(NHS)待完成的價值116億英鎊(31.9億美元)的維護項目以及能源採購合約(EPC)維修的緊迫期限。預計英國設施管理市場中硬性服務合約的規模將進一步擴大。這是因為仍有28%的商業房地產的EPC評級為D級或更低,因此需要加快機械、電氣和管道(MEP)系統的維修。 MEP和暖通空調(HVAC)領域正受益於旨在實現淨零排放的監管措施,這些措施要求到2035年將排放量減少47%至62%。資產數位化進一步增加了對預測性維護分析的需求,使服務提供者能夠在資產故障發生之前進行干預,同時滿足合規報告要求。
目前規模較小的軟性服務預計到2031年將以2.78%的複合年成長率成長,這主要得益於醫院級清潔標準和職場體驗的創新。更嚴格的感染控制法規增加了對機器人消毒系統和基於感測器的衛生規程的需求。共享辦公空間營運商需要智慧門禁系統,從而推動了保全服務的現代化。格倫費爾大廈火災後加強的消防安全措施增加了對整合警報測試和疏散規劃服務的需求。這些因素共同促使服務供應商轉向提供將卓越的軟性服務與數據驅動的合規性相結合的綜合解決方案。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 目前運轉率
- 主要設施管理業者的盈利指標
- 勞動指標 - 勞動參與率
- 按服務類型分類的設施管理市場佔有率(%)
- 以硬性服務分類的設施管理市場佔有率(%)
- 軟服務在設施管理市場佔有率(%)
- 主要都會區的都市化和人口成長
- 英國基礎設施計畫中的產業投資優先事項
- 與勞動和安全標準相關的監管因素
- 市場促進因素
- 商業不動產的快速擴張
- 技術整合(物聯網、人工智慧、自動化)
- 外包趨勢正在加速發展。
- 人們對職場體驗計畫和員工福祉越來越感興趣。
- 嚴格的能源效率和淨零排放法規
- 彈性辦公空間的興起催生了對敏捷設施管理(FM)合約的需求。
- 市場限制因素
- 勞動力短缺和技能缺口
- 營運成本上升給利潤率帶來了壓力。
- 供應商生態系統分散阻礙了服務標準化。
- 智慧建築系統中的資料安全問題
- 價值鏈分析
- PESTLE分析
- 市場准入者的法規和法律體制
- 宏觀經濟指標對FM需求的影響
- 波特五力分析
- 投資和資金籌措分析
第5章 市場規模與成長預測
- 按服務類型
- 硬服務
- 資產管理
- 機電及暖通空調服務
- 消防系統和安全
- 其他硬體維修服務
- 軟服務
- 辦公室支援和安全
- 清潔服務
- 餐飲服務
- 其他軟調頻服務
- 硬服務
- 按服務類型
- 內部
- 外包
- 單頻調頻
- 捆綁式調頻廣播
- 整合調頻
- 按最終用戶行業分類
- 商業(IT/電信、零售/倉儲等)
- 飯店餐飲業(飯店、餐廳、大型餐廳)
- 公共基礎設施(政府、教育、交通)
- 醫療保健(公立和私立機構)
- 工業和流程(製造業、能源業、採礦業)
- 其他終端用戶產業(多用戶住宅、娛樂、運動和休閒)
第6章 競爭情勢
- 市場集中度
- 策略舉措和夥伴關係
- 市佔率分析
- 公司簡介
- ISS UK
- Mitie Group PLC
- Serco Group PLC
- Kier Group PLC
- G4S Facilities Management UK Limited
- Sodexo Facilities Management Services
- Compass Group
- Equans
- VINCI Facilities Limited
- Aramark Facilities Services
- Andron Facilities Management
- CSM Facilities Management Group
- Orton Group
- Global Facilities.
- BGIS
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom facility management market size was valued at USD 81.09 billion in 2025 and estimated to grow from USD 83.29 billion in 2026 to reach USD 95.24 billion by 2031, at a CAGR of 2.71% during the forecast period (2026-2031).
This report is Segmented by Service Type (Hard Services, Soft Services), Offering Type (In-House, Outsourced), End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Healthcare, Industrial and Process, Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom (UK) Facility Management Market Trends and Insights
Technology Integration (IoT, AI, Automation)
AI-driven building-management platforms are redefining service delivery, with the Intellectual Property Office cutting maintenance response times from 14 days to seconds after launching a digital work-order portal. Smart sensors relay live occupancy, temperature, and air-quality data, letting providers shift from reactive to predictive maintenance while lowering energy use and elevating employee comfort. CBRE's entry into hyperscale data-center facilities management underscores the high-margin potential in segments that demand 24-hour analytical monitoring. Healthcare and education clients lead adoption because compliance regimes mandate continuous environmental monitoring. As digital dashboards merge soft and hard services, providers package cleaning, security, office support, and asset maintenance into data-rich contracts that command price premiums.
Rapid Commercial Real Estate Expansion
Royal Institution of Chartered Surveyors data show occupier demand turned positive in Q1 2025, and prime office rents in Central London are projected to rise nearly 5% in the year. Industrial assets register the strongest investment appetite, with an +18% net balance in investor demand, propelled by e-commerce and near-shoring. New developments increase demand for commissioning, lifecycle asset management, and ongoing compliance auditing. Facility managers partnering early with developers secure multi-year revenue streams in smart-ready buildings that integrate ESG dashboards from day one. Logistics growth similarly drives tailored FM packages that combine inventory tracking technologies, dock management, and advanced fire-suppression maintenance for high-throughput warehouses.
Labor Shortages and Skill Gaps
Hospitality, cleaning, and catering units face 132,000 job vacancies post-Brexit, straining FM rosters. The 2025 Immigration White Paper raises the Skilled Worker visa threshold to RQF Level 6, curtailing access to international staff for entry-level FM roles. Employer training investment has fallen 28% since 2005, creating a skills deficit just as buildings adopt sophisticated digital systems. Firms counteract with supervisor academies such as JPC by Samsic's 12-module Next Gen programme focusing on leadership and technical upskilling. Nonetheless, high turnover and an aging workforce continue to limit sector capacity.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Outsourcing Trend
- Rising Focus on Workplace Experience and Employee Well-being
- Margin Pressure from Rising Operational Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard services held 60.12% of United Kingdom facility management market share in 2025, anchored by the NHS's GBP 11.6 billion (USD 3.19 billion) maintenance backlog and stringent EPC upgrade timelines. The United Kingdom facility management market size for hard-service contracts is poised to expand as 28% of commercial properties still rate D or lower on EPC scale, forcing accelerated mechanical, electrical, and plumbing overhauls. MEP and HVAC segments benefit from regulatory pathways to net-zero that mandate 47%-62% emissions cuts by 2035. Asset digitization further lifts demand for predictive-maintenance analytics, letting providers intervene before asset failure while meeting compliance reporting needs.
Soft services, while smaller today, are forecast to grow 2.78% CAGR through 2031, propelled by hospital-grade cleaning standards and workplace-experience innovations. Heightened infection-control rules elevate the premium for robotic disinfection systems and sensor-verified hygiene protocols. Co-working operators require smart access control, driving security-service modernization. Fire-safety upgrades tied to post-Grenfell legislation amplify demand for integrated alarm testing and evacuation-planning services. Together, these forces shift provider offerings toward comprehensive packages that merge soft-service excellence with data-backed compliance.
Complete Report Scope:
- By Service Type
- Hard Services
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- Soft Services
- Office Support and Security
- Cleaning Services
- Catering Services
- Other Soft FM Services
- Hard Services
- By Offering Type
- In-house
- Outsourced
- Single FM
- Bundled FM
- Integrated FM
- By End-user Industry
- Commercial (IT and Telecom, Retail and Warehouses, etc.)
- Hospitality (Hotels, Eateries, Large-scale Restaurants)
- Institutional and Public Infrastructure (Govt, Education, Transportation)
- Healthcare (Public and Private Facilities)
- Industrial and Process (Manufacturing, Energy, Mining)
- Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
List of Companies Covered in this Report:
- ISS UK
- Mitie Group PLC
- Serco Group PLC
- Kier Group PLC
- G4S Facilities Management UK Limited
- Sodexo Facilities Management Services
- Compass Group
- Equans
- VINCI Facilities Limited
- Aramark Facilities Services
- Andron Facilities Management
- CSM Facilities Management Group
- Orton Group
- Global Facilities.
- BGIS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.1.1 Current Occupancy Rates
- 4.1.2 Profitability Rates of Major FM Players
- 4.1.3 Workforce Indicators - Labor Participation
- 4.1.4 Facility Management Market Share (%), by Service Type
- 4.1.5 Facility Management Market Share (%), by Hard Services
- 4.1.6 Facility Management Market Share (%), by Soft Services
- 4.1.7 Urbanization and Population Growth in Major Metros
- 4.1.8 Sector Investment Priorities in United Kingdom's Infrastructure Pipeline
- 4.1.9 Regulatory Drivers Specific to Labour and Safety Standards
- 4.2 Market Drivers
- 4.2.1 Rapid Commercial Real Estate Expansion
- 4.2.2 Technology Integration (IoT, AI, Automation)
- 4.2.3 Increasing Outsourcing Trend
- 4.2.4 Rising Focus on Workplace Experience and Employee Well-being
- 4.2.5 Stringent Energy-Efficiency and Net-Zero Regulations
- 4.2.6 Rise of Flexible Workspaces Requiring Agile FM Contracts
- 4.3 Market Restraints
- 4.3.1 Labor Shortages and Skill Gaps
- 4.3.2 Margin Pressure from Rising Operational Costs
- 4.3.3 Fragmented Supplier Ecosystem Hindering Service Standardization
- 4.3.4 Data-Security Concerns in Smart Building Systems
- 4.4 Value Chain Analysis
- 4.5 PESTEL Analysis
- 4.6 Regulatory and Legislative Framework for Market Entrants
- 4.7 Impact of Macroeconomic Indicators on FM Demand
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Services
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Hard Services
- 5.1.1.1 Asset Management
- 5.1.1.2 MEP and HVAC Services
- 5.1.1.3 Fire Systems and Safety
- 5.1.1.4 Other Hard FM Services
- 5.1.2 Soft Services
- 5.1.2.1 Office Support and Security
- 5.1.2.2 Cleaning Services
- 5.1.2.3 Catering Services
- 5.1.2.4 Other Soft FM Services
- 5.1.1 Hard Services
- 5.2 By Offering Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.2.2.1 Single FM
- 5.2.2.2 Bundled FM
- 5.2.2.3 Integrated FM
- 5.3 By End-user Industry
- 5.3.1 Commercial (IT and Telecom, Retail and Warehouses, etc.)
- 5.3.2 Hospitality (Hotels, Eateries, Large-scale Restaurants)
- 5.3.3 Institutional and Public Infrastructure (Govt, Education, Transportation)
- 5.3.4 Healthcare (Public and Private Facilities)
- 5.3.5 Industrial and Process (Manufacturing, Energy, Mining)
- 5.3.6 Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ISS UK
- 6.4.2 Mitie Group PLC
- 6.4.3 Serco Group PLC
- 6.4.4 Kier Group PLC
- 6.4.5 G4S Facilities Management UK Limited
- 6.4.6 Sodexo Facilities Management Services
- 6.4.7 Compass Group
- 6.4.8 Equans
- 6.4.9 VINCI Facilities Limited
- 6.4.10 Aramark Facilities Services
- 6.4.11 Andron Facilities Management
- 6.4.12 CSM Facilities Management Group
- 6.4.13 Orton Group
- 6.4.14 Global Facilities.
- 6.4.15 BGIS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Technology-led Integrated FM (IoT, BMS, AI-based Predictive Maintenance)
- 7.3 ESG-compliant FM Solutions Demand
- 7.4 Future Service-Model Shifts (Outcome-based Contracts)

 2026-2030年全球設施管理市場
 設施管理(FM)軟體:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)北美設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)亞太地區硬設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)硬設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)日本設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 Frost Radar™:泰國設施管理,2026 年中國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)