


 |
市場調查報告書
商品編碼
2123347
亞太地區自助倉儲:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Asia-Pacific Self Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
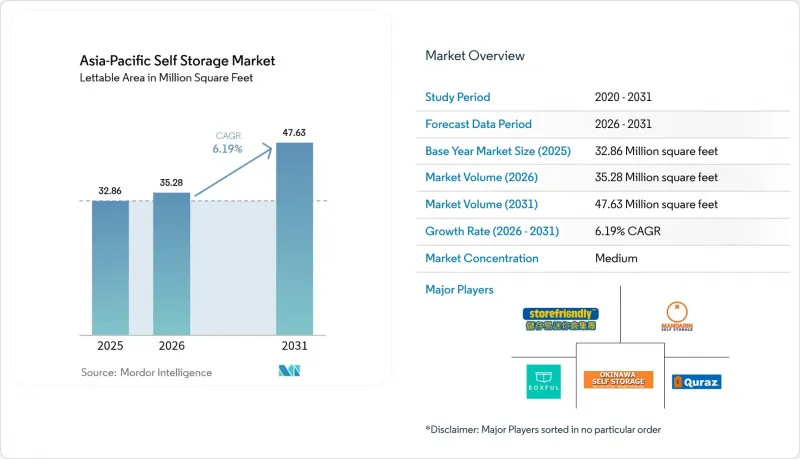
根據 Mordor Intelligence 預測,亞太地區的自助倉儲市場規模將從 2025 年的 3,286 萬平方英尺成長到 2026 年的 3,528 萬平方英尺,到 2031 年將達到 4,763 萬平方英尺,2026 年至 2031 年的複合年成長率為 6.19%。
本報告按最終用戶(個人、企業)、儲存容量(小型和中型單位(小於 40 平方英尺)、大型單位(40 平方英尺或以上)、其他)、儲存類型(空調、非空調)和所有權類型(自有、租賃)進行分類。市場預測以體積(百萬平方英尺)為單位。
亞太地區自助倉儲市場趨勢及洞察。
都市區住宅密度更高,公寓面積卻在縮小。
過去十年間,亞太地區主要城市的住宅平均占地面積下降了10%至15%。同時,預計到2024年,香港的房價收入比將達到25,深圳將達到32,居民別無選擇,只能租用外部儲物櫃來騰出居住空間。城市規劃部門仍然優先考慮建造高密度住宅大樓,以最大限度地增加單元數量而非單元面積,這導致家庭物品與公寓儲物空間長期不匹配。東京和新加坡的開發人員現在將地下儲物空間納入新建公寓,預計擁有儲物權的單元售價將會上漲。隨著個人生活空間的持續萎縮,對外部儲物櫃的需求幾乎以相同的速度成長,即使新的儲物設施不斷開放,運轉率仍然居高不下。這種結構性趨勢是亞太地區自助倉儲市場長期成長的最大驅動力。
中小企業跨境電履約爆炸性成長
到2025年,東南亞的線上銷售額將達到3,000億美元。此外,採用在地化履約的經銷商在限時搶購期間的銷售額最高可達平時的14倍,因為當日送達提高了轉換率。中小企業無力負擔多年期的倉庫租賃費用,因此他們選擇可根據促銷週期靈活擴展且全天候可用的模組化儲存單元。在越南,高階倉儲設施中40%的租戶是跨境經銷商,他們持有緩衝庫存以應對上游供應波動。營運商透過提供裝卸平台、小包裹揀選包裝區和全天候門房服務等來滿足這一需求,從而提升了這些客戶的消費佔有率。此細分市場的強勁表現將在中期內顯著推動亞太地區自助倉儲市場的發展。
適宜的都市區用地稀缺和價格飆升
2024年,新加坡工業用地運轉率達到89%,競標為爭取少數適合改建為倉儲設施的土地支付了創紀錄的溢價。這種情況導致租金收益率低於機構投資者的預期回報。香港也面臨類似的困境。 2024年,三塊適合興建自助倉儲的土地拍賣,中標價超過每平方英尺15,000港幣(1,920美元)。以這個價格,只有運轉率超過95%且租金比目前平均高出30%,這些設施才能獲利。在東京市中心,在住宅用地上新建自助倉儲設施幾乎是被禁止的,迫使開發商將目光投向較小的城市,但更長的通勤時間削弱了支撐亞太地區自助倉儲市場的便利性溢價。在中國,雖然土地供應量較大,但地方城市負責人優先考慮工業園區,導致自助倉儲申請者需要等待數月才能獲得酌情批准。由於土地供應緊張,最昂貴的大都會圈單元房開發速度正在放緩,儘管需求強勁,但仍拉低了基準成長率 1.1 個百分點。
細分市場分析
到2025年,個人用戶使用的占地面積將佔總使用面積的62.41%,而企業租戶預計到2031年將以平均每年6.72%的速度成長,超過住宅的成長速度。這種轉變正在擴大亞太地區的自助倉儲市場規模,因為跨境經銷商、現場服務承包商和微型品牌擴大將倉儲空間視為可變物流成本,而不是資本支出。越南的中小企業透過將緩衝庫存轉移到都市區配送區域內的多個儲物櫃,降低了高達20%的「最後一公里」配送成本。營運商正在合理地分類其設施,將帶有裝卸平台的樓層分配給企業使用,而將較高樓層分配給個人用戶,這種配置即使在零售業低迷時期也能保持穩定的運轉率。
個人客戶的需求趨勢也在改變。退休人士從郊區住宅搬到面積較小的公寓後,如今往往會簽訂多年契約,延長平均入住時間,降低解約率。同時,年輕的專業人士在因工作或留學搬遷到國外時,會將自助倉儲作為臨時存儲空間,因此運營商推出了包含搬家服務和三個月儲物櫃租賃的折扣套餐。透過運用動態定價工具,連鎖店可以調整價格,例如在假日等銷售高峰期逐步提高企業用戶的價格,在淡季降低個人用戶的價格。這種雙管齊下的策略提高了每平方英尺的收入,並幫助那些成功平衡兩大需求群體的營運商在亞太地區自助倉儲市場維持市場佔有率。
2025年,面積超過40平方英尺的大型儲物間佔新契約面積的48.37%,但小型儲物間的成長速度更快,年成長率達6.43%,這主要得益於電商企業和零工經濟從業人員對彈性空間使用的偏好。小型儲物間每平方英尺的租金比大型儲物間高出40-50%,因此營運商正在對現有設施進行分割以提高租金收入。在香港,倉庫內部的「箱中箱」維修可以在不改變建築外觀的情況下增加25%的儲物間數量,這在土地價格超過每平方英尺1900美元的地區極具吸引力。
根據馬尼拉和胡志明市的電商企業反映,其60%的庫存週轉率在30天內達到峰值,因此他們更傾向於在宅配中心附近設置多個20平方英尺的儲物櫃,而不是單一的中央倉庫。在新加坡,Work+Store推出的5平方英尺收納方案(每月80新元/60美元)目前運轉率高達90%,主要針對市中心的金融業專業人士,用於異地存放合規文件。這種靈活的空間配置允許租戶在無需完全騰空的情況下增減儲物空間,從而降低空置風險。這有助於確保更穩定的現金流,並促進亞太地區自助倉儲市場的發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 都市區住宅密度更高,公寓面積卻在縮小。
- 中小企業跨境電履約爆炸性成長
- 機構投資者正將大量資金投入將工業設施改造成自助倉儲。
- 靈活工作安排的普及和結合在家工作和辦公室辦公室的混合工作方式的興起。
- 政府對老舊工業地產改造的獎勵措施
- 對溫控專用儲存設施的需求日益成長
- 市場限制因素
- 城市適宜用地短缺,價格飛漲。
- 分區規劃、消防安全法規及危險物品法規的碎片化
- 新興市場消費者意識低落和文化抵觸情緒高漲
- 來自按需行動儲存和家庭收納技術的競爭日益激烈。
- 產業價值鏈分析
- 監理情勢
- 宏觀經濟因素的影響
- 波特五力分析
- 投資分析
- PESTLE分析
- 消費者在選擇自助倉儲設施時需要考慮的關鍵因素
- 香港市場動態
- 運轉率分析
- 平均租金趨勢
- 盈利分析
- 平均設施規模
第5章 市場規模及成長預測(單位)
- 最終用戶
- 個人
- 公司
- 按儲存容量
- 小型和中型單元(小於 40 平方英尺)
- 大型單元(40平方英尺或以上)
- 其他(置物櫃/兩層堆疊)
- 依儲存類型
- 空調控制型
- 非空調型
- 依所有權類型
- 擁有
- 租賃
- 按地區
- 日本
- 香港
- 台灣
- 新加坡
- 中國
- 馬來西亞
- 其他亞太國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- StorHub Group Pte. Ltd.
- Extra Space Asia Management Pte. Ltd.
- Boxful Holdings Limited
- Mandarin Self Storage Pte. Ltd.
- Storage King Pty Ltd
- Quraz Co., Ltd.
- Okinawa Self Storage Co., Ltd.
- UD Self Storage Co., Ltd.
- Far East Organization-Store-Y Self Storage
- Store Friendly Self Storage Group Limited
- National Storage Holdings Ltd.(REIT)
- Kennards Self Storage Pty Limited
- Keep-It-Safe Self Storage Sdn. Bhd.
- Cube Self Storage Limited
- SC Storage(Holdings)Limited
- Lock+Store Pte. Ltd.
- UrbanSpace Self Storage Ltd.
- Spacebox Self Storage Co., Ltd.
- My Storage Vietnam Co., Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Asia-Pacific self storage market size is expected to grow from 32.86 million square feet in 2025 to 35.28 million square feet in 2026 and is forecast to reach 47.63 million square feet by 2031 at 6.19% CAGR over 2026-2031.
This report is Segmented by End-User (Personal, and Business), Storage Size (Small and Medium Units (Less Than 40 Sq Ft), Large Units (Above 40 Sq Ft), and More), Storage Type (Climate-Controlled, and Non-Climate-Controlled), Ownership Pattern (Owned, and Leased). The Market Forecasts are Provided in Terms of Volume (Million Sq Ft).
Asia-Pacific Self Storage Market Trends and Insights
Densifying Urban Housing and Shrinking Apartment Sizes
Median floor areas in major Asia-Pacific cities have fallen by 10-15% over the past decade, while price-to-income multiples reached 25 in Hong Kong and 32 in Shenzhen in 2024, leaving residents with little choice but to rent off-site lockers to regain livable space. Planning agencies continue to favor high-density towers that maximize unit counts rather than unit sizes, locking in a long-run mismatch between household belongings and apartment capacity. Developers in Tokyo and Singapore now integrate storage basements into new condominiums, banking on higher sale prices for units with bundled storage rights. As personal living quarters shrink further, demand for external lockers scales almost one-for-one, which keeps occupancy high even as new facilities open. This structural trend contributes the single largest uplift to long-term growth in the Asia-Pacific self storage market.
Explosive Growth of SME Cross-Border E-Commerce Fulfillment
Southeast Asia's online sales reached USD 300 billion in 2025, and merchants using localized fulfillment sold up to 14 times more during flash-sales because one-day delivery boosts conversion rates. Small enterprises cannot justify multi-year warehouse leases, so they choose modular storage units with 24-hour access that scale with promotional cycles. In Vietnam, 40% of business tenants in premium facilities are cross-border sellers holding buffer stock to manage upstream volatility. Operators respond with loading docks, parcel pick-and-pack zones, and business-hour concierge services, deepening wallet share from these clients. The segment's outperformance adds meaningful lift to the Asia-Pacific self storage market during the medium term.
Scarcity and Escalating Price of Suitable Urban Land Parcels
Singapore's industrial space ran 89% full in 2024, leaving bidders to pay record premiums for the few blocks that can still convert to storage, a reality that compresses rental yields below institutional return targets. Hong Kong mirrors the squeeze: three storage-suitable plots came to auction in 2024, and the winning price exceeded HKD 15,000 (USD 1,920) per square foot, a level that only breakevens when facilities hold more than 95% occupancy at rents 30% above today's averages. Tokyo's inner wards ban most new self-storage on residential lots, so operators chase secondary cities, but longer drive times undercut the convenience premium that anchors the Asia-Pacific self storage market. China offers larger land banks yet local planners grant priority to manufacturing parks, leaving self-storage applicants waiting months for discretionary approvals. Tighter site supply slows unit roll-outs in the priciest metros, subtracting 1.1 percentage points from baseline growth even while demand remains firm.
Other drivers and restraints analyzed in the detailed report include:
- Institutional Capital Flooding into Industrial-to-Storage Conversions
- Rise of Flexible Work and Hybrid Home-Office Setups
- Patchwork Zoning, Fire-Safety and Hazardous Goods Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The segment captured 62.41% of total square footage from personal users in 2025, yet business tenants are expanding at a 6.72% compound clip to 2031, outpacing households. This pivot lifts the Asia-Pacific self storage market size because cross-border sellers, field-service contractors and micro-brands now treat storage nodes as variable logistics rather than capital expenditure. Small enterprises in Vietnam cut last-mile costs by up to 20% after shifting buffer inventory into multiple lockers located within urban delivery zones. Operators segment facilities accordingly, reserving loading-dock floors for businesses and upper levels for personal users, a mix that supports stable occupancy even during retail down-cycles.
Personal customers are also evolving. Retirees moving from suburban homes into smaller condominiums now sign multi-year contracts, lengthening average tenancy and reducing churn. Younger professionals, meanwhile, treat storage as episodic capacity during job relocations or overseas study, so operators offer discount bundles that combine moving services with three-month locker rentals. Dynamic pricing tools let chains nudge tariffs higher for business users during festival-driven sales peaks while softening rates for households in lull periods. This dual-track strategy deepens revenue per square foot, sustaining the Asia-Pacific self storage market share of operators that balance both demand pools.
Large rooms above 40 square feet commanded 48.37% of 2025 take-up, yet small and medium modules are growing faster at 6.43% a year as e-commerce merchants and gig workers favour agile footprints. Small lockers yield 40-50% higher rent per square foot than jumbo rooms, so operators subdivide legacy facilities to amplify revenue density. Box-in-box retrofits inside Hong Kong warehouses can raise total unit count by 25% without altering the external shell, an attractive tactic where land prices eclipse USD 1,900 per square foot.
E-retailers in Manila and Ho Chi Minh City report that 60% of stock turns inside 30 days, so they prefer several 20-square-foot lockers scattered near courier depots instead of one big central store. Work+Store's 5-square-foot option in Singapore, priced at SGD 80 (USD 60) a month, now runs 90% full among downtown finance professionals who store compliance files off-site. The granular mix tempers vacancy risk because tenants can scale space up or down without total move-outs, locking in stickier cash flows that reinforce the Asia-Pacific self storage market.
Complete Report Scope:
- By End-User
- Personal
- Business
- By Storage Size
- Small and Medium Units (Less Than 40 Sq Ft)
- Large Units (Above 40 Sq Ft)
- Other Storage Sizes (Lockers / Double-Stacked)
- By Storage Type
- Climate-Controlled
- Non-Climate-Controlled
- By Ownership Pattern
- Owned
- Leased
- By Geography
- Japan
- Hong Kong
- Taiwan
- Singapore
- China
- Malaysia
- Rest of Asia Pacific
List of Companies Covered in this Report:
- StorHub Group Pte. Ltd.
- Extra Space Asia Management Pte. Ltd.
- Boxful Holdings Limited
- Mandarin Self Storage Pte. Ltd.
- Storage King Pty Ltd
- Quraz Co., Ltd.
- Okinawa Self Storage Co., Ltd.
- UD Self Storage Co., Ltd.
- Far East Organization - Store-Y Self Storage
- Store Friendly Self Storage Group Limited
- National Storage Holdings Ltd. (REIT)
- Kennards Self Storage Pty Limited
- Keep-It-Safe Self Storage Sdn. Bhd.
- Cube Self Storage Limited
- SC Storage (Holdings) Limited
- Lock+Store Pte. Ltd.
- UrbanSpace Self Storage Ltd.
- Spacebox Self Storage Co., Ltd.
- My Storage Vietnam Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Densifying Urban Housing and Shrinking Apartment Sizes
- 4.2.2 Explosive Growth of SME Cross-Border E-Commerce Fulfillment
- 4.2.3 Institutional Capital Flooding into Industrial-to-Self-Storage Conversions
- 4.2.4 Rise of Flexible Work and Hybrid Home-Office Setups
- 4.2.5 Government Incentives for Adaptive Reuse of Aging Industrial Stock
- 4.2.6 Growing Demand for Climate-Controlled Specialty Storage
- 4.3 Market Restraints
- 4.3.1 Scarcity and Escalating Price of Suitable Urban Land Parcels
- 4.3.2 Patchwork Zoning, Fire-Safety and Hazardous Goods Regulations
- 4.3.3 Low Consumer Awareness and Cultural Reluctance in Emerging Markets
- 4.3.4 Increasing Competition from On-Demand Mobile Storage and Home-Organization Tech
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 PESTEL Analysis
- 4.10 Key Considerations of Consumers While Selecting a Self-Storage Facility
- 4.11 Market Dynamics in Hong Kong
- 4.11.1 Analysis of Occupancy Rates
- 4.11.2 Average Rental Trends
- 4.11.3 Profitability Analysis
- 4.11.4 Average Facility Size
5 MARKET SIZE AND GROWTH FORECASTS (UNIT)
- 5.1 By End-User
- 5.1.1 Personal
- 5.1.2 Business
- 5.2 By Storage Size
- 5.2.1 Small and Medium Units (Less Than 40 Sq Ft)
- 5.2.2 Large Units (Above 40 Sq Ft)
- 5.2.3 Other Storage Sizes (Lockers / Double-Stacked)
- 5.3 By Storage Type
- 5.3.1 Climate-Controlled
- 5.3.2 Non-Climate-Controlled
- 5.4 By Ownership Pattern
- 5.4.1 Owned
- 5.4.2 Leased
- 5.5 By Geography
- 5.5.1 Japan
- 5.5.2 Hong Kong
- 5.5.3 Taiwan
- 5.5.4 Singapore
- 5.5.5 China
- 5.5.6 Malaysia
- 5.5.7 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 StorHub Group Pte. Ltd.
- 6.4.2 Extra Space Asia Management Pte. Ltd.
- 6.4.3 Boxful Holdings Limited
- 6.4.4 Mandarin Self Storage Pte. Ltd.
- 6.4.5 Storage King Pty Ltd
- 6.4.6 Quraz Co., Ltd.
- 6.4.7 Okinawa Self Storage Co., Ltd.
- 6.4.8 UD Self Storage Co., Ltd.
- 6.4.9 Far East Organization - Store-Y Self Storage
- 6.4.10 Store Friendly Self Storage Group Limited
- 6.4.11 National Storage Holdings Ltd. (REIT)
- 6.4.12 Kennards Self Storage Pty Limited
- 6.4.13 Keep-It-Safe Self Storage Sdn. Bhd.
- 6.4.14 Cube Self Storage Limited
- 6.4.15 SC Storage (Holdings) Limited
- 6.4.16 Lock+Store Pte. Ltd.
- 6.4.17 UrbanSpace Self Storage Ltd.
- 6.4.18 Spacebox Self Storage Co., Ltd.
- 6.4.19 My Storage Vietnam Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 德國自助倉儲:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)新加坡自助倉儲:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)越南自助倉儲:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)歐洲自助倉儲:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)美國自助倉儲:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)自助倉儲:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 城市按需儲存服務市場預測至2034年-按服務類型、儲存格式、預訂模式、儲存容量、服務期限、最終用戶和地區分類的全球分析
 自助倉儲市場規模、佔有率、趨勢和預測:按儲存單元規模、最終用途和地區分類,2026-2034 年
 2026年全球自助倉儲市場報告
 自助倉儲市場:2026-2032年全球市場預測(按單位類型、租賃期限、單位面積、存取方式及最終用戶分類)