


 |
市場調查報告書
商品編碼
2122558
石膏板:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Gypsum Board - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,石膏板市場規模預計將在 2026 年達到 179.2 億平方公尺,高於 2025 年的 168.9 億平方公尺,預計到 2031 年將達到 240.7 億平方公尺。
預計從 2026 年到 2031 年,其複合年成長率將達到 6.08%。
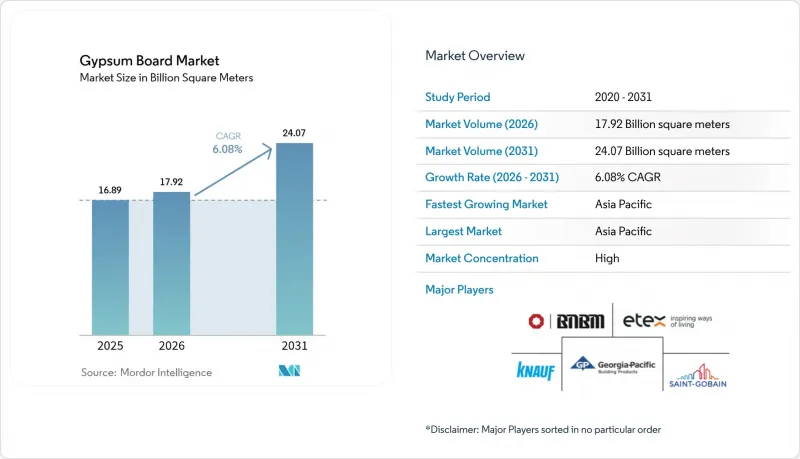
本報告按產品類型(牆板、天花板和成品板)、原料(天然石膏、合成(脫硫)石膏和再生石膏)、應用領域(住宅、商業、公共和工業)以及地區(亞太地區、北美、歐洲、南美以及中東和非洲)進行細分。市場預測以銷售量(單位)為基礎。
全球石膏板市場趨勢及洞察
亞太地區住宅建設快速成長
快速的都市區化進程正推動開發人員轉向高密度住宅開發,而石膏板系統相比濕抹灰工藝,有助於縮短室內施工時間。儘管中國2024年的水泥總產量下降了10%,但由於開發人員專注於加快室內施工以確保現金流,牆板的銷售仍然強勁。印度政府主導的住宅計畫帶來了穩定的地基需求,而東南亞的大型企劃則指定在學校和交通樞紐中使用石膏板,看重其久經考驗的防火性能。全部區域的勞動力短缺問題,也使得工廠預製板更具吸引力,因為它可以減少現場施工。
在成熟市場,房屋翻新和改造的浪潮正在加速發展。
預計到2025年,美國的房屋維修支出將達到5,090億美元,扭轉先前兩年的下滑趨勢。由於美國40%的住宅建於1970年以前,牆體更換直接推高了石膏板的需求,因為這符合更嚴格的防火和隔熱標準。住宅平均花費4,700美元進行室內維修,其中防黴防潮板材位列購買清單之首。歐盟類似的維修規定也推動了高性能板材(兼具隔熱和隔音功能)的訂單。這些趨勢使得石膏板的需求即使在經濟放緩時期也能保持穩定。
天然石膏和能源價格波動
2024年,美國天然石膏產量達2,200萬噸,但單位成本因礦井深度和運輸距離的不同而有顯著差異。由於煅燒過程嚴重依賴天然氣,石膏板價格極易受到燃料價格波動的影響。隨著燃煤發電廠的關閉導致合成石膏供應減少,製造商被迫從更遠的礦床採購原料,從而推高了運輸成本並增加了成本風險。雖然節能窯爐和區域倉儲中心在一定程度上緩解了這種影響,但原物料價格的波動仍在短期內抑製石膏板市場的成長。
細分市場分析
到2025年,牆板在石膏板市場中仍將佔據59.62%的佔有率。這主要得益於牆板在住宅室內裝修市場中,成本和是否符合建築規範是選擇牆板的關鍵因素。同時,預計到2031年,預製裝飾板的複合年成長率將達到7.39%,比石膏板市場的整體成長率高出1個百分點以上。
目前,在高階市場,具有增強的防黴性、防潮性和抗衝擊性的石膏板,例如 PURPLE XP,更受青睞。雖然這些板材比標準 X 型板材貴 20-30%,但它們常用於廚房、浴室和醫療機構走廊等場所,這些場所的停工成本會造成重大損失。製造商正致力於透過將這些特性與工廠預塗漆相結合來獲得更高的利潤率。隨著承包商對「預塗漆」交付的需求日益成長,預塗漆產品預計將在石膏板市場中擴大市場佔有率。
區域分析
預計到2025年,亞太地區將佔全球石膏板出貨量的46.10%,這主要得益於中國房地產建設的巨大未充分利用以及印度的「全民住宅」計畫。儘管存在政治和信貸風險的擔憂,但預計到2031年,該地區仍將以7.31%的複合年成長率持續主導石膏板市場出貨量,並將繼續保持領先地位。
北美市場以翻新需求為支撐,保持穩定。歐洲市場趨勢受監管主導,儘管宏觀經濟指標疲軟,但RE2020及類似框架正在推動對碳最佳化設計的需求。這三大區域構成競爭格局,而南美、中東和非洲仍是成長前沿,人均滲透率較低,為石膏板市場的未來成長留下了空間。
製造商正透過環境產品聲明 (EPD) 來凸顯自身優勢,並經常使用回收材料以滿足競標要求。儘管建築業產出成長速度低於亞太地區,但注重環境、社會和治理 (ESG) 的溢價策略正在抵消銷售成長放緩的影響,並支撐石膏板市場的利潤成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 亞太地區住宅建設快速成長
- 在成熟市場,房屋翻新和改造的浪潮正在加速發展。
- 過渡到輕質高強度石膏板解決方案
- 政府對防火、隔音和節能建築提供誘因
- 合成(FGD)石膏的供應狀況,該產品具有成本優勢。
- 市場限制因素
- 天然石膏和能源價格波動
- 纖維水泥及其他替代板材的採用率不斷提高
- 強制性的碳中和要求導致人們對產品中的碳含量進行了更嚴格的審查。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 牆板
- 天花板
- 預裝飾板
- 按成分
- 天然石膏
- 合成(FGD)石膏
- 再生石膏
- 透過使用
- 住宅
- 商業的
- 對機構而言
- 產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 泰國
- 馬來西亞
- 印尼
- 越南
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 土耳其
- 北歐的
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 奈及利亞
- 埃及
- 卡達
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- BNBM
- Etex Group
- Everest Industries Limited
- Georgia-Pacific Gypsum LLC
- Global Gypsum Board Co LLC(Gypcore)
- Holcim
- Jason New Materials
- Knauf Group
- National Gypsum Services Company
- Osman Group
- PABCO Gypsum
- Saint-Gobain
- Shandong Taihe Dongxin Co.,Ltd
- VANS Gypsum
- Volma
- Winstone Wallboards Limited
- YOSHINO GYPSUM CO.,LTD.
第7章 市場機會與未來展望
According to Mordor Intelligence, gypsum board market size in 2026 is estimated at 17.92 Billion square meters, growing from 2025 value of 16.89 Billion square meters with 2031 projections showing 24.07 Billion square meters, growing at 6.08% CAGR over 2026-2031.
This report is Segmented by Product Type (Wall Board, Ceiling Board, and Pre-Decorated Board), Raw Material (Natural Gypsum, Synthetic (FGD) Gypsum, and Recycled Gypsum), Application (Residential, Commercial, Institutional, and Industrial), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Units).
Global Gypsum Board Market Trends and Insights
Surging Residential Construction in APAC
Rapid urban migration pushes developers toward high-density housing, and gypsum board systems help shorten interior fit-out cycles compared with wet plaster. Although China's overall cement output fell 10% in 2024, wallboard volumes remained resilient because developers focused on accelerating finishing work to unlock cash flows. India's government-backed housing schemes add steady baseline demand, while Southeast Asian megaprojects specify gypsum for its proven fire resistance in schools and transit hubs. Labor shortages across the region strengthen the appeal of factory-finished boards that reduce on-site trades.
Accelerating Renovation and Remodeling Wave in Mature Markets
Renovation outlays in the United States climbed to USD 509 billion in 2025, reversing two years of contraction. Forty percent of U.S. dwellings pre-date 1970, so wall replacements align with tighter fire and insulation codes, directly lifting gypsum demand. Homeowners spent an average USD 4,700 on interior upgrades, with mold- and moisture-resistant boards ranking high on shopping lists. Similar retrofit mandates in the EU catalyze orders for high-performance panels that combine thermal and acoustic gains. These dynamics sustain a stable volume base for the gypsum board market during economic slowdowns.
Volatile Natural Gypsum and Energy Prices
Mined gypsum output touched 22 million tons in the United States during 2024, but unit costs varied widely by mine depth and haulage distance. Calcination relies heavily on natural gas, making board pricing sensitive to fuel swings. As decommissioning of coal plants removes synthetic supply, mills draw from deposits located farther afield, inflating freight bills and amplifying cost risk. Energy-efficient kilns and regional warehouse hubs partly soften the blow, yet input volatility still trims the gypsum board market growth trajectory in the near term.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Lightweight and High-Strength Drywall Solutions
- Government Incentives for Fire, Sound, and Energy-Efficient Buildings
- Rising Penetration of Fibre-Cement and Other Panel Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wall board retained 59.62% gypsum board market share in 2025, sustained by universal acceptance in residential interiors where cost and code compliance drive specification. Pre-decorated panels, however, are forecast to post 7.39% CAGR to 2031, a speed more than one percentage point above the overall gypsum board market.
Premium segments now favor mold-, moisture- or impact-modified boards such as PURPLE XP, priced at a 20-30% uplift over generic Type X, yet often selected for kitchens, baths, and healthcare corridors where downtime is costly. Manufacturers bundle these attributes with factory coatings to seize higher-margin value capture. As contractors increasingly pursue "paint-ready" delivery, pre-decorated formats are poised to widen their share within the gypsum board market.
Complete Report Scope:
- By Product Type
- Wall Board
- Ceiling Board
- Pre-decorated Board
- By Raw Material
- Natural Gypsum
- Synthetic (FGD) Gypsum
- Recycled Gypsum
- By Application
- Residential
- Commercial
- Institutional
- Industrial
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Thailand
- Malaysia
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Turkey
- Nordics
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Qatar
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific claimed 46.10% of 2025 shipments, thanks to China's massive real-estate backlog and India's Housing for All program. Regional growth at 7.31% CAGR through 2031 ensures the gypsum board market remains volume-weighted to this geography despite political and credit risk clouds.
North America embodies renovation-driven steadiness. Europe's pathway is more regulation-led, as RE2020 and similar frameworks reinforce demand for carbon-optimized designs despite slower macro indicators. Together, the three regions shape the competitive map, while South America, and Middle-East and Africa remain opportunity frontiers where lower per-capita penetration leaves headroom for future gypsum board market growth.
Manufacturers differentiate through environmental product declarations, often bundling recycled content to meet tender prerequisites. Although construction output is flatter than Asia-Pacific, premium ESG-minded pricing offsets slower unit growth, safeguarding revenue expansion inside the gypsum board market.
- BNBM
- Etex Group
- Everest Industries Limited
- Georgia-Pacific Gypsum LLC
- Global Gypsum Board Co LLC (Gypcore)
- Holcim
- Jason New Materials
- Knauf Group
- National Gypsum Services Company
- Osman Group
- PABCO Gypsum
- Saint-Gobain
- Shandong Taihe Dongxin Co.,Ltd
- VANS Gypsum
- Volma
- Winstone Wallboards Limited
- YOSHINO GYPSUM CO.,LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Residential Construction in APAC
- 4.2.2 Accelerating Renovation and Remodeling Wave in Mature Markets
- 4.2.3 Shift Toward Lightweight and High-Strength Drywall Solutions
- 4.2.4 Government Incentives for Fire, Sound, and Energy-Efficient Buildings
- 4.2.5 Cost-Advantaged Synthetic (FGD) Gypsum Availability
- 4.3 Market Restraints
- 4.3.1 Volatile Natural Gypsum and Energy Prices
- 4.3.2 Rising Penetration of Fibre-Cement and Other Panel Alternatives
- 4.3.3 Carbon-Neutral Mandates Raising Embodied-Carbon Scrutiny
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Wall Board
- 5.1.2 Ceiling Board
- 5.1.3 Pre-decorated Board
- 5.2 By Raw Material
- 5.2.1 Natural Gypsum
- 5.2.2 Synthetic (FGD) Gypsum
- 5.2.3 Recycled Gypsum
- 5.3 By Application
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Institutional
- 5.3.4 Industrial
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Thailand
- 5.4.1.6 Malaysia
- 5.4.1.7 Indonesia
- 5.4.1.8 Vietnam
- 5.4.1.9 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Turkey
- 5.4.3.8 Nordics
- 5.4.3.9 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Nigeria
- 5.4.5.4 Egypt
- 5.4.5.5 Qatar
- 5.4.5.6 South Africa
- 5.4.5.7 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 BNBM
- 6.4.2 Etex Group
- 6.4.3 Everest Industries Limited
- 6.4.4 Georgia-Pacific Gypsum LLC
- 6.4.5 Global Gypsum Board Co LLC (Gypcore)
- 6.4.6 Holcim
- 6.4.7 Jason New Materials
- 6.4.8 Knauf Group
- 6.4.9 National Gypsum Services Company
- 6.4.10 Osman Group
- 6.4.11 PABCO Gypsum
- 6.4.12 Saint-Gobain
- 6.4.13 Shandong Taihe Dongxin Co.,Ltd
- 6.4.14 VANS Gypsum
- 6.4.15 Volma
- 6.4.16 Winstone Wallboards Limited
- 6.4.17 YOSHINO GYPSUM CO.,LTD.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 歐洲石膏板:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)石膏板襯紙:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)石膏板襯裡:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)中東和非洲石膏板市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)亞太地區石膏板市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 石膏板市場:全球市場預測(2026-2032年)石膏板市場-2026-2032年全球市場預測
 石膏板市場規模、佔有率和成長分析:按產品類型、最終用途、分銷管道、厚度、表面處理和地區分類-2026-2033年產業預測
 石膏板市場-全球產業規模、佔有率、趨勢、機會、預測:按類型、厚度、應用、地區和競爭格局分類,2021-2031年
 2026年全球石膏板懸吊天花板市場報告