


 |
市場調查報告書
商品編碼
2121861
合約包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Contract Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,合約包裝市場預計到 2026 年價值 861.6 億美元,高於 2025 年的 796.9 億美元,預計到 2031 年將達到 1272.8 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 8.12%。
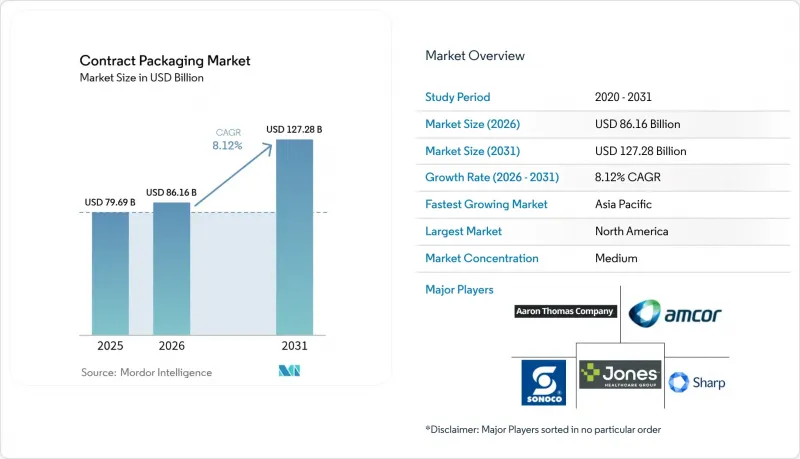
本報告按材料類型(塑膠、紙/紙板、其他)、包裝類型(初級包裝、二級包裝、三級包裝)、服務類型(配製/混合、填充/組裝、其他)、最終用戶行業(食品、飲料、製藥、其他)和地區(北美、南美、其他)進行細分。市場預測以美元計價。
全球合約包裝市場趨勢及洞察
利用外包取得競爭優勢
儘管製藥公司正日益加大對藥物研發的投入,但他們卻依賴合約包裝供應商來完成監管嚴格的包裝作業。美國食品藥物管理局(FDA)於2024年發布的複雜產品指南收緊了驗證、容器和密封系統完整性以及文件記錄方面的要求,促使生物製藥企業將包裝工作外包給像Catalent這樣的專業公司。 Catalent已在德國投資2,300萬歐元(約2,713萬美元)建造了一條自動化臨床供應鏈。歐洲藥品管理局(EMA)關於先進治療藥物的法規進一步加劇了這一局面,該法規將合規風險和技術創新的責任轉移到了合約包裝供應商身上,從而縮短了申辦企業的產品上市時間,並使其免於昂貴的設施升級。
電子商務導致SKU數量爆炸性成長
直接面對消費者的分銷管道需要小批量生產、頻繁更換包裝設計,以及專為宅配網路而非托盤零售量身定做的保護性包裝設計。靈活的生產單元和數位化工單系統使合約包裝商能夠在不增加設置成本的情況下提高每班次的換線次數。食品品牌正利用這種彈性來生產季節性口味和限量版產品,同時利用同一條生產線來生產符合線上零售商減排目標的環保材料。現代工作流程軟體收集可追溯性資料並將其與企業資源計劃 (ERP) 系統整合,以滿足審計要求並降低召回風險。
嚴格遵守跨境法規
由於美國食品藥物管理局 (FDA) 和歐洲的法規存在差異,供應商被迫創建重複的驗證方案、標籤格式和審計追蹤。 PPWR 設計標準可能與美國食品接觸標準相衝突,導致庫存管理和配方變更重複。中小企業難以資金籌措必要的品管團隊、ERP 模組和序列化基礎設施,這限制了它們參與全球競標。
細分市場分析
2025年,塑膠憑藉著成熟的供應鏈,佔銷售額的54.78%。然而,由於回收材料的分配和品牌推廣活動,生物基材料和複合材料正以9.12%的複合年成長率加速成長。這種轉變推動了擠出成型設備升級、相容劑技術以及無需多層複合即可維持保存期限的阻隔塗層的需求。隨著PPWR(聚丙烯薄膜包裝法規)最後期限的臨近,預計植物來源聚合物在合約包裝市場中的佔有率將擴大,這將使擁有配方專業知識的供應商獲得價格優勢。
技術複雜性正在拉大競爭對手之間的差距。擁有內部實驗室的供應商可以快速進行遷移測試、密封強度測試和保存期限測試,從而縮短核准週期。預計到2024年,可生物分解解決方案的專利申請量將增加34%,凸顯了快速創新,並表明在材料領域保持領先地位對於維持獲利能力至關重要。
預計到2025年,初級包裝將佔銷售額的56.89%,複合年成長率為8.96%,主要歸因於FDA和EMA對接觸面驗證的嚴格要求。合約包裝佔據主導市場佔有率的原因在於其對容器和密封系統的完整性要求,以及對提取物和浸出物的檢測,而這些檢測對於小規模內部團隊而言往往不具備經濟可行性。
由於全球瓦楞紙板和紙箱加工能力的不斷提升,二級包裝的利潤率面臨壓力,但從防篡改、品牌訊息和序列化等方面來看,它仍然至關重要。三級包裝正隨著自動化而不斷發展,機器人堆垛機和倉儲機器人正在推動符合人體工學的重新設計,從而提高空間利用率。
區域分析
北美地區得益於成熟的醫藥外包模式和先進自動化技術的應用,預計到2025年將佔全球銷售額的38.55%。亞太地區的合約包裝市場正以11.03%的複合年成長率快速成長,主要得益於中國包裝產量成長8.7%以及相關製造業扶持措施。此外,印度疫苗產量的激增以及日本醫療設備認證制度的改革也進一步推動了該地區的需求。
歐洲的成長主要依賴對《塑膠包裝廢棄物法規》(PPWR) 的遵守,這推動了對可回收材料和數位化追溯基礎設施的投資。南美、中東和非洲擁有長期成長機遇,而這些機會取決於物流現代化和法規協調統一。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 利用外包取得競爭優勢
- 電子商務導致SKU數量爆炸性成長
- 新型生物製藥包裝的醫藥外包
- 透過自動化和機器人技術降低單位成本
- 基於永續性的基質轉型
- 利用近岸外包降低地緣政治風險
- 市場限制因素
- 嚴格遵守跨境法規
- 與我們自己的包裝生產線競爭
- 樹脂和能源價格波動
- 目標再生材料含量與供應量之間的差異
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 依材料類型
- 塑膠
- 紙張和紙板
- 金屬
- 玻璃
- 生物基複合材料
- 按包裝類型
- 初級包裝
- 二級包裝
- 三級包裝
- 按服務類型
- 配製/混合
- 填充和組裝
- 包裝和標籤
- 物流履約
- 其他
- 按最終用戶行業分類
- 食物
- 飲料
- 製藥
- 化妝品和個人護理
- 產業
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 越南
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Sonoco Products Company
- Aaron Thomas Company, Inc.
- Jones Healthcare Group Inc.
- Sharp Packaging Services LLC
- Pharma Tech Industries Inc.
- Reed-Lane Inc.
- Multipack Solutions LLC
- UNICEP Packaging LLC
- Stamar Packaging Inc.
- Budelpack Poortvliet BV
- Complete Co-Packing Services Ltd.
- Catalent Inc.
- PCI Pharma Services
- CCL Industries Inc.
- Smurfit WestRock
- Green Packaging Asia Ltd.
- Nulogy Corporation
- Graphic Packaging Holding Co.
- AptarGroup Inc.
- DHL Supply Chain(Co-Packing Division)
第7章 市場機會與未來展望
According to Mordor Intelligence, contract packaging market size in 2026 is estimated at USD 86.16 billion, growing from 2025 value of USD 79.69 billion with 2031 projections showing USD 127.28 billion, growing at 8.12% CAGR over 2026-2031.
This report is Segmented by Material Type (Plastics, Paper and Paperboard, and More), Packaging Type (Primary, Secondary, and Tertiary), Service Type (Formulation and Blending, Filling and Assembly, and More), End-User Industry (Food, Beverage, Pharmaceutical, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Contract Packaging Market Trends and Insights
Outsourcing to Gain Competitive Advantage
Pharmaceutical manufacturers increasingly direct capital toward drug discovery while relying on pharmaceutical contract packaging providers for highly regulated packaging tasks. FDA guidance on combination products released in 2024 intensified validation, container-closure integrity, and documentation demands, encouraging biologics producers to outsource to specialists such as Catalent, which invested EUR 23 million (USD 27.13 million) in an automated clinical-supply line in Germany. European Medicines Agency rules for advanced therapy medicinal products heighten the complexity further, prompting contract packagers to shoulder compliance risk and technology refresh, shortening launch timelines for sponsors and freeing them from costly facility upgrades.
Explosive SKU Proliferation from E-commerce
Direct-to-consumer channels require shorter runs, frequent artwork variations, and protective designs tuned for parcel networks rather than palletized retail. Flexible manufacturing cells and digital job tickets allow contract packagers to execute more changeovers per shift without inflating set-up costs. Food brands exploit this agility for seasonal flavors and limited editions, while the same lines accommodate eco-friendly substrates that align with online retailers' emissions goals. Modern workflow software captures traceability data and routes it into enterprise resource planning systems, meeting audit requirements and reducing recall risk.
Stringent Cross-border Regulatory Compliance
Divergent FDA and European rules compel providers to duplicate validation protocols, label formats, and audit trails. PPWR design standards occasionally clash with U.S. food-contact thresholds, obliging dual inventory or reformulation. Smaller firms struggle to fund the necessary quality teams, enterprise resource planning modules, and serialization infrastructure, limiting their participation in global bids.
Other drivers and restraints analyzed in the detailed report include:
- Pharma Outsourcing for Novel Biologics Packaging
- Automation and Robotics Lowering Per-unit Cost
- Competition from In-house Packaging Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics retained 54.78% of revenue in 2025 thanks to entrenched supply chains, but recycled-content quotas and brand commitments accelerate a 9.12% CAGR for bio-based and composite materials. The shift calls for extrusion upgrades, compatibilizer know-how, and barrier coatings that preserve shelf life without multilayer laminates. Contract packaging market size allocations to plant-based polymers will expand as PPWR deadlines near, giving providers with formulary expertise a pricing premium.
Technical complexity widens competitive gaps. Providers with on-site laboratories conduct migration, seal-strength, and shelf-life tests swiftly, shortening approval cycles. Patent filings for biodegradable solutions rose 34% in 2024, underscoring rapid innovation and signaling that material leadership will be pivotal for margin defense.
Primary packaging accounted for 56.89% of 2025 revenue and is set for a 8.96% CAGR owing to stringent contact-surface validations required by the FDA and EMA. The contract packaging market share premium arises from container-closure integrity, extractables, and leachables testing, which smaller in-house teams often cannot execute economically.
Secondary packs face margin compression as corrugate and carton converting capacities rise globally, yet remain critical for tamper evidence, brand messaging, and serialization. Tertiary packs evolve with automation; robotic palletizers and warehouse robots drive ergonomic redesigns that improve cube utilization.
Complete Report Scope:
- By Material Type
- Plastics
- Paper and Paperboard
- Metal
- Glass
- Bio-based and Composites
- By Packaging Type
- Primary
- Secondary
- Tertiary
- By Service Type
- Formulation and Blending
- Filling and Assembly
- Packaging and Labeling
- Fulfillment and Logistics
- Other Service Types
- By End-User Industry
- Food
- Beverage
- Pharmaceutical
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America contributed 38.55% of 2025 sales, underpinned by mature pharmaceutical outsourcing and advanced automation adoption. The contract packaging market size in Asia-Pacific is accelerating at 11.03% CAGR, propelled by China's 8.7% packaging output growth and pro-manufacturing policies. India's vaccine output surge and Japan's reform of medical device approvals further lift regional demand.
Europe's growth centers on PPWR compliance, spurring investment in recyclable substrates and digital traceability infrastructure. South America and the Middle East and Africa represent long-horizon opportunities contingent on logistics upgrades and regulatory harmonization.
- Amcor plc
- Sonoco Products Company
- Aaron Thomas Company, Inc.
- Jones Healthcare Group Inc.
- Sharp Packaging Services LLC
- Pharma Tech Industries Inc.
- Reed-Lane Inc.
- Multipack Solutions LLC
- UNICEP Packaging LLC
- Stamar Packaging Inc.
- Budelpack Poortvliet BV
- Complete Co-Packing Services Ltd.
- Catalent Inc.
- PCI Pharma Services
- CCL Industries Inc.
- Smurfit WestRock
- Green Packaging Asia Ltd.
- Nulogy Corporation
- Graphic Packaging Holding Co.
- AptarGroup Inc.
- DHL Supply Chain (Co-Packing Division)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Outsourcing to gain competitive advantage
- 4.2.2 Explosive SKU proliferation from e-commerce
- 4.2.3 Pharma outsourcing for novel biologics packaging
- 4.2.4 Automation and robotics lowering per-unit cost
- 4.2.5 Sustainability-led substrate shifts
- 4.2.6 Near-shoring to mitigate geopolitical risk
- 4.3 Market Restraints
- 4.3.1 Stringent cross-border regulatory compliance
- 4.3.2 Competition from in-house packaging lines
- 4.3.3 Volatile resin and energy prices
- 4.3.4 Mismatch between recycled-content goals and supply
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (Value)
- 5.1 By Material Type
- 5.1.1 Plastics
- 5.1.2 Paper and Paperboard
- 5.1.3 Metal
- 5.1.4 Glass
- 5.1.5 Bio-based and Composites
- 5.2 By Packaging Type
- 5.2.1 Primary
- 5.2.2 Secondary
- 5.2.3 Tertiary
- 5.3 By Service Type
- 5.3.1 Formulation and Blending
- 5.3.2 Filling and Assembly
- 5.3.3 Packaging and Labeling
- 5.3.4 Fulfillment and Logistics
- 5.3.5 Other Service Types
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceutical
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Sonoco Products Company
- 6.4.3 Aaron Thomas Company, Inc.
- 6.4.4 Jones Healthcare Group Inc.
- 6.4.5 Sharp Packaging Services LLC
- 6.4.6 Pharma Tech Industries Inc.
- 6.4.7 Reed-Lane Inc.
- 6.4.8 Multipack Solutions LLC
- 6.4.9 UNICEP Packaging LLC
- 6.4.10 Stamar Packaging Inc.
- 6.4.11 Budelpack Poortvliet BV
- 6.4.12 Complete Co-Packing Services Ltd.
- 6.4.13 Catalent Inc.
- 6.4.14 PCI Pharma Services
- 6.4.15 CCL Industries Inc.
- 6.4.16 Smurfit WestRock
- 6.4.17 Green Packaging Asia Ltd.
- 6.4.18 Nulogy Corporation
- 6.4.19 Graphic Packaging Holding Co.
- 6.4.20 AptarGroup Inc.
- 6.4.21 DHL Supply Chain (Co-Packing Division)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 合約包裝和履約服務:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)美國合約套裝:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)藥品和醫療設備無菌包裝服務:市場佔有率分析、產業趨勢和統計數據以及成長預測(2025-2030 年)歐洲合約包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 合約包裝市場:2026-2032年全球市場預測(按包裝類型、服務類型、包裝材料、合約類型和最終用途行業分類)電子商務包裝準備與合規包裝服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026-2030年全球合約包裝市場
 合約包裝市場規模、佔有率、趨勢和預測:按包裝類型、材料、服務、最終用途行業和地區分類,2026-2034 年
 合約包裝和履約服務市場-全球產業規模、佔有率、趨勢、機會、預測:按服務類型、最終用戶、地區和競爭格局分類,2021-2031年
 合約包裝市場規模、佔有率和趨勢分析報告:按材料、包裝類型、最終用途、地區和細分市場預測(2026-2033 年)