


 |
市場調查報告書
商品編碼
2121272
歐洲合約包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Contract Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
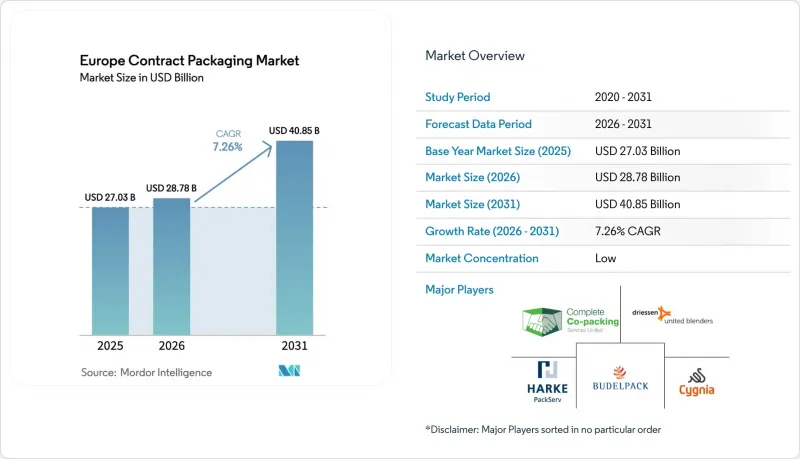
根據 Mordor Intelligence 預測,歐洲合約包裝市場預計將從 2025 年的 270.3 億美元成長到 2026 年的 287.8 億美元,到 2031 年達到 408.5 億美元,2026 年至 2031 年的複合年預計成長率為 7.26%。
本報告按服務類型(一級包裝、二級包裝和三級包裝)、包裝形式(硬質包裝和軟質包裝)、技術(傳統手動生產線、半自動生產線和全自動/機器人生產線)、終端用戶行業(食品、製藥等)以及國家/地區進行細分。市場預測以美元計價。
歐洲合約包裝市場的趨勢與洞察
電子商務訂單履約量增加
隨著食品雜貨、保健品和高階飲品轉向直銷模式,2025年線上零售小包裹運輸量激增。提供「揀貨、包裝和訂單」服務的合約包裝公司訂單量實現兩位數成長,促使包裝箱尺寸標準化、引入按需標籤印表機,並在最後階段增加客製化單元。中型企業選擇外包而非自建生產線,理由是外包可以帶來季節性柔軟性並避免資本投資。小包裹處理速度的提升使得自動化稱重、檢測和貼標模組成為承運商合規的必要條件。位於德國、荷蘭和法國小包裹分揀中心附近的供應商則受惠於最後一公里配送費用的降低。
DTC品牌正在快速成長。
到2025年,超過480個新的DTC品牌推出了區域網路商店,目標市場涵蓋健康、美容和環保家居護理等細分領域。這些創辦人傾向於使用數量可變的瓦楞紙箱和網紅套裝,這些套裝需要小批量組裝,並附帶組裝說明和QR碼插頁。能夠整合二次包裝、履約和退貨處理的代工包裝商簽訂了多年期契約,其中包括定期補貨。訂閱盒策展人也加速了對插頁印刷和數據驅動個性化的需求,使得小批量推出的前置作業時間縮短至三天或更短。在私募股權資金的支持下,採用即時訂單狀態API的代工包裝商獲得了更多回頭客。
歐盟嚴格的「包裝廢棄物指令」目標
修訂後的指令要求生產商在2030年將人均包裝廢棄物減少15%,並達到65%的回收率。這些要求促使品牌商減少過度包裝,從而直接減少了透過合約包裝公司處理的商品數量。此外,即將實施的生態調節費(將對不可回收的包裝形式收費)迫使聯合包裝公司改造設備,以適應拉伸接受度有限、厚度更薄的新型基材。合規性的監測和報告增加了行政負擔,尤其對於中小規模企業而言。雖然這些法規加速了創新,但由於加工商仍在等待關於再生材料含量的最終規範,因此也延緩了投資。
細分市場分析
預計到2025年,二次包裝將佔歐洲合約包裝市場佔有率的41.23%,並實現最高的組裝量。這一主導地位反映了零售商和電商企業對條碼紙盒、安全封條和促銷重疊包裝的持續需求。隨著品牌組合中SKU數量的增加,預計到2026年,對自動化裝盒和收縮商品搭售系統的需求將持續成長。由於訂單重複性高、勞動密集度高以及在最後階段包裝差異化的空間,二次包裝工作流程仍然是一個極具吸引力的領域。供應商正在透過改造機器人取放設備來提高生產線的柔軟性,這些設備可以在30分鐘內切換包裝規格,從而能夠在服務多個客戶的車間內運作。
包括堆疊和拉伸食品包裝在內的三級物流流程預計將以 8.34% 的複合年成長率成長,超過所有其他服務等級。這一成長趨勢與整合倉庫管理的日益普及以及全通路零售商青睞的混合 SKU 托盤配置的轉變相吻合。配備視覺引導工具的機器人驅動托盤單元有助於提高生產效率並改善工作環境。合約包裝公司正在銷售可減少停機時間的預測性維修儀表板,這吸引了面臨即時補貨壓力的快速消費品 (FMCG) 客戶。因此,預計三級物流業務量將逐步蠶食內部物流的佔有率,進一步強化歐洲合約包裝市場轉移至專業履約夥伴的趨勢。
預計到2025年,玻璃瓶、鋁罐和高密度聚苯乙烯瓶等硬質容器將主導歐洲合約包裝市場,佔52.32%的市場佔有率。飲料填充、個人保健產品填充和藥品泡殼包裝均依賴硬質容器系統來確保產品保護和劑量精準。由於進入門檻高,擁有無塵室和低溫灌裝設備的合約包裝公司能夠保持穩定的銷售量。此外,德國的玻璃瓶回收系統提高了填充線的運轉率。品牌擁有者仍然青睞硬質包裝,因為優質化,並且在閉合迴路中具有實際和可回收性。
同時,軟性包裝材料預計將成為成長最快的品類,2026年至2031年的複合年成長率將達到8.84%。可重複密封的包裝袋、自立吸嘴和小袋能夠減少材料用量和運輸重量,並符合零售商的永續發展標準。為酸性食品和藥粉提供安全防遷移薄膜的合約包裝公司正在簽訂多年期訂單。數位包裝袋印刷技術的引入,使得小批量生產能夠根據地區和語言差異進行客製化,從而增強了靈活的行銷策略。因此,預計軟性包裝將縮小與硬質包裝之間的差距,進一步豐富歐洲合約包裝市場的整體格局。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務訂單履約量增加
- DTC(直接面對消費者)品牌的激增
- 零售商轉向「即買即用」包裝。
- 單材料基板的永續成長
- 在小批量生產中引入數位印刷
- 英國脫歐後供應鏈近岸外包
- 市場限制因素
- 歐盟的《包裝廢棄物指令》設定了嚴格的目標。
- 西歐人事費用上升
- 由於內部包裝業務而產生的競爭
- 取得回收的PCR材料的途徑有限。
- 產業價值鏈分析
- 監理情勢
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按服務類型
- 初級包裝
- 裝瓶和灌裝
- 袋裝包裝
- 罐頭
- 吸塑包裝
- 其他主要包裝
- 二級包裝
- 卡特寧
- 標籤
- 收縮包裝
- 其他二級包裝
- 三級包裝
- 托盤堆疊
- 商品搭售
- 其他三級包裝
- 初級包裝
- 按包裝類型
- 硬包裝
- 軟包裝
- 透過技術
- 傳統手動線
- 半自動生產線
- 全自動/機器人驅動生產線
- 按最終用戶行業分類
- 飲料
- 食物
- 製藥
- 化妝品和個人護理
- 其他終端用戶產業
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Budelpack Poortvliet BV
- Cygnia Logistics Ltd
- Complete Co-Packing Services Ltd
- Driessen United Blenders BV
- Harke PackServ GmbH
- Kompak Co-Making and Co-Packing
- Marvinpac SA
- NOMI Co-Packing
- Boughey Distribution Ltd
- Total Pack BV
- DHL Supply Chain
- Staci Group
- Sonoco Display and Packaging
- WePack Ltd
- Flexicon Europe Ltd
- MSK Pharmalogistic GmbH
- Groupe LPR(Logistic Packaging Resources)
- Famar SA
- PharmaPac UK Ltd
- Tjoapack Netherlands BV
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe contract packaging market size is expected to increase from USD 27.03 billion in 2025 to USD 28.78 billion in 2026 and reach USD 40.85 billion by 2031, growing at a CAGR of 7.26% over 2026-2031.
This report is Segmented by Service Type (Primary Packaging, Secondary Packaging, and Tertiary Packaging), Packaging Format (Rigid Packaging, and Flexible Packaging), Technology (Conventional Manual Lines, Semi-Automated Lines, and Fully Automated/Robotics-Enabled Lines), End-User Industry (Food, Pharmaceuticals, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Contract Packaging Market Trends and Insights
Rising E-commerce Fulfilment Volumes
Online retail parcels jumped throughout 2025 as grocery, health supplements, and premium beverages migrated to direct shipment models. Contract packers that offer pick, fill, and ship services witnessed double-digit order growth, prompting them to standardize box sizes, install print-on-demand labelers, and add late-stage customization cells. Medium enterprises opted to outsource instead of building captive lines, citing the need for seasonal flexibility and avoiding capital outlay. Higher parcel velocity has made automated weigh-check-label modules essential for maintaining carrier compliance. Providers located near parcel sortation centers in Germany, the Netherlands, and France are benefiting from lower last-mile fees.
Proliferation of DTC Brands
More than 480 new DTC labels opened regional web shops in 2025, targeting niche markets in health, beauty, and eco-friendly home care. These founders prefer variable-count cartons and influencer kits that must be assembled in small batches, accompanied by kitting instructions and QR-enabled inserts. Contract packers able to combine secondary packaging, fulfillment, and returns handling gained multi-year contracts that include periodic product restaging. Subscription-box curators also accelerated demand for insert printing and data-driven personalization, resulting in lead times of three days or less for short runs. As private-equity inflows sustain this launch cycle, co-packers that embed real-time order-status APIs are capturing repeat volumes.
Stringent EU Packaging Waste Directive Targets
The revised directive requires producers to reduce packaging waste by 15% per capita by 2030 and to achieve 65% recycling rates. Such mandates prompt brands to reduce over-packaging, thereby directly reducing the volume flowing through contract packers. Additionally, forthcoming eco-modulation fees penalize non-recyclable formats, forcing co-packers to requalify equipment for new substrates and thinner gauges with limited stretch tolerance. Compliance monitoring and reporting add administrative overhead, especially for small and mid-size facilities. While the rule accelerates innovation, it simultaneously delays investment as converters await definitive specifications for recycled content.
Other drivers and restraints analyzed in the detailed report include:
- Retailer Shift to Shelf-Ready Packaging Formats
- Growth of Sustainable Mono-Material Substrates
- Rising Labour Costs in Western Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Secondary packaging generated the highest volume of assemblies, capturing 41.23% of the Europe contract packaging market share in 2025. The dominance reflects ongoing retailer and e-commerce requirements for bar-coded cartons, security seals, and promotional over-wraps. In 2026, demand for automated cartoning and shrink bundling systems continues to climb as brand portfolios expand their SKU counts. Secondary workflows remain attractive due to recurring orders, high labor content, and the scope for late-stage pack differentiation. Providers are bolstering line flexibility, retrofitting robotic pick-and-place units that switch formats within 30 minutes to serve multi-client halls.
Tertiary operations, encompassing palletizing and stretch-hooding, are forecast to outpace all other service tiers with an 8.34% CAGR. The upswing aligns with wider adoption of integrated warehouse management and the transition to mixed-SKU pallet configurations favored by omnichannel retailers. Robotics-enabled pallet cells equipped with vision-guided tooling support higher output and ergonomic relief. Contract packers are marketing predictive-maintenance dashboards that lower downtime, appealing to fast-moving consumer goods customers under just-in-time restock pressure. Consequently, tertiary volumes are expected to chip away at in-house logistics, reinforcing the Europe contract packaging market narrative of specialized fulfillment partners.
Rigid formats, including glass bottles, aluminum cans, and high-density polyethylene jugs, led with a 52.32% share of the Europe contract packaging market size in 2025. Beverage filling, personal-care bottling, and pharma blistering rely on rigid systems due to product protection and dosing accuracy. Co-packers owning clean-room and cold-fill infrastructure enjoy high barriers to entry, leading to steady throughput. Moreover, returnable glass loops in Germany expand bottling line utilization. Brand owners remain keen on rigid packs for premiumization as well as real and perceived recyclability in closed loops.
Conversely, flexible substrates are set to be the fastest-growing category, advancing at an 8.84% CAGR during 2026-2031. Re-closable pouches, stand-up spouts, and sachets reduce material usage and shipping weight, appealing to retailers' sustainability scorecards. Contract packers that certify migration-safe films for acidic foods and pharma powders are landing multi-year volumes. Integration of digital pouch printing allows shorter runs tied to geographic and language variations, bolstering agile marketing programs. Thus, flexible share is predicted to narrow the gap with rigid formats, reinforcing diversification across the Europe contract packaging market.
Complete Report Scope:
- By Service Type
- Primary Packaging
- Bottling and Filling
- Pouching
- Canning
- Blister Packaging
- Other Primary Packaging
- Secondary Packaging
- Cartoning
- Labeling
- Shrink Wrapping
- Other Secondary Packaging
- Tertiary Packaging
- Palletizing
- Bundling
- Other Tertiary Packaging
- Primary Packaging
- By Packaging Format
- Rigid Packaging
- Flexible Packaging
- By Technology
- Conventional Manual Lines
- Semi-Automated Lines
- Fully Automated / Robotics-Enabled Lines
- By End-user Industry
- Beverages
- Food
- Pharmaceuticals
- Cosmetics and Personal Care
- Other End-user Industries
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Budelpack Poortvliet BV
- Cygnia Logistics Ltd
- Complete Co-Packing Services Ltd
- Driessen United Blenders BV
- Harke PackServ GmbH
- Kompak Co-Making and Co-Packing
- Marvinpac SA
- NOMI Co-Packing
- Boughey Distribution Ltd
- Total Pack BV
- DHL Supply Chain
- Staci Group
- Sonoco Display and Packaging
- WePack Ltd
- Flexicon Europe Ltd
- MSK Pharmalogistic GmbH
- Groupe LPR (Logistic Packaging Resources)
- Famar SA
- PharmaPac UK Ltd
- Tjoapack Netherlands BV
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising E-commerce Fulfilment Volumes
- 4.2.2 Proliferation of DTC (Direct-to-Consumer) Brands
- 4.2.3 Retailer Shift to Shelf-Ready Packaging Formats
- 4.2.4 Growth of Sustainable Mono-Material Substrates
- 4.2.5 Adoption of Digital Printing for Short-Runs
- 4.2.6 Near-shoring of Supply Chains Post-Brexit
- 4.3 Market Restraints
- 4.3.1 Stringent EU Packaging Waste Directive Targets
- 4.3.2 Rising Labour Costs in Western Europe
- 4.3.3 Competition from In-house Packaging Operations
- 4.3.4 Limited Access to Recycled PCR Material
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Primary Packaging
- 5.1.1.1 Bottling and Filling
- 5.1.1.2 Pouching
- 5.1.1.3 Canning
- 5.1.1.4 Blister Packaging
- 5.1.1.5 Other Primary Packaging
- 5.1.2 Secondary Packaging
- 5.1.2.1 Cartoning
- 5.1.2.2 Labeling
- 5.1.2.3 Shrink Wrapping
- 5.1.2.4 Other Secondary Packaging
- 5.1.3 Tertiary Packaging
- 5.1.3.1 Palletizing
- 5.1.3.2 Bundling
- 5.1.3.3 Other Tertiary Packaging
- 5.1.1 Primary Packaging
- 5.2 By Packaging Format
- 5.2.1 Rigid Packaging
- 5.2.2 Flexible Packaging
- 5.3 By Technology
- 5.3.1 Conventional Manual Lines
- 5.3.2 Semi-Automated Lines
- 5.3.3 Fully Automated / Robotics-Enabled Lines
- 5.4 By End-user Industry
- 5.4.1 Beverages
- 5.4.2 Food
- 5.4.3 Pharmaceuticals
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Other End-user Industries
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Budelpack Poortvliet BV
- 6.4.2 Cygnia Logistics Ltd
- 6.4.3 Complete Co-Packing Services Ltd
- 6.4.4 Driessen United Blenders BV
- 6.4.5 Harke PackServ GmbH
- 6.4.6 Kompak Co-Making and Co-Packing
- 6.4.7 Marvinpac SA
- 6.4.8 NOMI Co-Packing
- 6.4.9 Boughey Distribution Ltd
- 6.4.10 Total Pack BV
- 6.4.11 DHL Supply Chain
- 6.4.12 Staci Group
- 6.4.13 Sonoco Display and Packaging
- 6.4.14 WePack Ltd
- 6.4.15 Flexicon Europe Ltd
- 6.4.16 MSK Pharmalogistic GmbH
- 6.4.17 Groupe LPR (Logistic Packaging Resources)
- 6.4.18 Famar SA
- 6.4.19 PharmaPac UK Ltd
- 6.4.20 Tjoapack Netherlands BV
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 合約包裝和履約服務:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)合約包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)美國合約套裝:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)藥品和醫療設備無菌包裝服務:市場佔有率分析、產業趨勢和統計數據以及成長預測(2025-2030 年)
 合約包裝市場:2026-2032年全球市場預測(按包裝類型、服務類型、包裝材料、合約類型和最終用途行業分類)電子商務包裝準備與合規包裝服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026-2030年全球合約包裝市場
 合約包裝市場規模、佔有率、趨勢和預測:按包裝類型、材料、服務、最終用途行業和地區分類,2026-2034 年
 合約包裝和履約服務市場-全球產業規模、佔有率、趨勢、機會、預測:按服務類型、最終用戶、地區和競爭格局分類,2021-2031年
 合約包裝市場規模、佔有率和趨勢分析報告:按材料、包裝類型、最終用途、地區和細分市場預測(2026-2033 年)