


 |
市場調查報告書
商品編碼
2121639
北美油漆和塗料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)North America Paints And Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,北美油漆和塗料市場預計到 2026 年價值 429 億美元,高於 2025 年的 418.2 億美元,預計到 2031 年將達到 487.8 億美元。
預計 2026 年至 2031 年的複合年成長率為 2.59%。
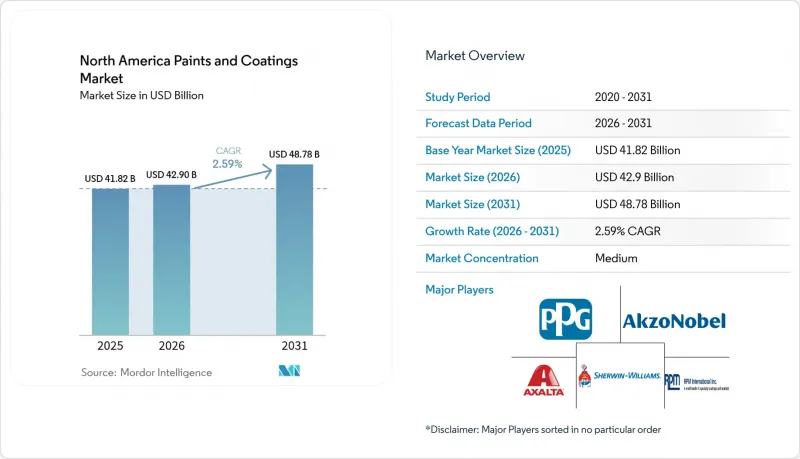
本報告按樹脂類型(丙烯酸樹脂、醇酸樹脂、環氧樹脂、聚氨酯及其他樹脂)、技術(水性塗料、溶劑型塗料、紫外光固化塗料)、終端用戶產業(建築、汽車、防護塗料、一般工業、運輸、包裝)和地區(美國、加拿大、墨西哥)進行細分。市場預測以美元(USD)為單位。
北美油漆和塗料市場趨勢及洞察
商業和公共設施建設迅速增加
2024年,商業支出達到1800億美元,直接推動了對符合嚴格室內空氣品質要求的高品質建築塗料的需求成長。隨著抗菌塗料逐漸成為標準配置,光是醫療機構大量使用塗料的計畫就達到了120億美元。物流中心、資料中心和教育設施的維修週期持續推動阻燃和靜電耗散塗料的高利潤訂單。低排放法規,例如南海岸空氣品質管理區規定的50克/公升VOC(揮發性有機化合物)上限,進一步提升了消費者對先進水性產品的偏好。因此,預計這些因素將確保北美塗料市場建築行業的強勁需求。
快速過渡到低VOC水性技術
目前,美國已有18個州實施了低於聯邦標準的VOC(揮發性有機化合物)排放限制,加速了水性塗料在各應用領域的普及。建築塗料產品享有15-20%的溢價,儘管溶劑用量激增,但仍緩解了利潤率壓力。混合化學技術將水性塗料的便利清潔與溶劑級耐久性結合,應用於防護領域,幫助供應商獲得長期工業合約。監管趨勢正在有效地鞏固更高的產品規格,並推高北美油漆和塗料市場的平均售價。
石化原料價格波動劇烈
二氧化鈦價格季度波動高達25%,丙烯酸單體價格飆升30%,這正在擾亂中小企業的採購預算,並對其合約利潤率構成壓力。墨西哥灣沿岸的天氣災害和煉油廠的維修週期造成的供應鏈中斷進一步加劇了價格波動。 2024年颶風「貝裡爾」對德克薩斯石化設施的影響凸顯了該產業對營運中斷的脆弱性。已實施避險計畫並擁有自身樹脂生產能力的製造商能夠保障盈利,這正在加速北美塗料市場的產業重組。
細分市場分析
丙烯酸體系在建築和汽車塗料領域兼具成本、耐候性和保色性方面的卓越平衡,預計到2025年將佔據北美塗料市場佔有率的37.12%。該細分市場也憑藉著生物基原料的創新取得了初步成功,在滿足永續性要求的同時,又不犧牲性能。儘管聚氨酯塗料的絕對市佔率較小,但預計其成長率最高,到2031年複合年成長率將達到2.95%,主要得益於OEM組件對高耐磨性的需求。環氧樹脂在船舶和基礎設施應用中仍然至關重要,因為在這些應用中,耐化學性比初始成本更為重要。雖然更嚴格的VOC法規導致醇酸樹脂的使用量下降,但改質醇酸-水性混合樹脂在小眾裝飾和底漆應用中仍然保持著重要地位。將丙烯酸樹脂的彈性與聚氨酯樹脂的硬度相結合的混合化學技術,為北美塗料市場提供差異化產品提供了一個極具前景的領域。
在工業維護和資產保護項目中,由於極端溫度和化學品侵蝕,矽酮和氟聚合物等細分市場產品價格居高不下,但在總銷售額中的佔有率仍然有限。聚酯樹脂正在粉末塗料領域站穩腳跟,不斷提升其零VOC(揮發性有機化合物)的宣稱,並為鋁擠壓產品提供長達25年的外牆質保。因此,當設施業主計算總營運成本時,樹脂的選擇往往優先考慮生命週期價值而非商品價格。擁有涵蓋多種技術的研發能力的供應商享有新進業者難以複製的服務型競爭優勢,這進一步加劇了北美塗料產業整體競爭的兩極化。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 商業和公共建築數量迅速成長
- 快速轉向低VOC水性技術
- OEM廠商對高性能粉末塗料的需求
- 人工智慧驅動的色彩匹配平台正在加速重新粉刷的周期。
- 美國製造業回歸美國本土,提振了防腐蝕的需求。
- 市場限制因素
- 石化原料價格波動劇烈
- 美國、加拿大和墨西哥對揮發性有機化合物(VOC)的監管規定嚴格且各不相同。
- 工業塗料業熟練施工人員人手不足
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依樹脂類型
- 丙烯酸樹脂
- 阿爾基多
- 環氧樹脂
- 聚酯纖維
- 聚氨酯
- 其他樹脂類型
- 透過技術
- 水溶液
- 溶劑型
- 粉末塗裝
- 紫外線固化塗層
- 按最終用戶行業分類
- 建築學
- 車
- 樹
- 保護塗層
- 一般工業
- 運輸
- 包裝
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- 3M
- Akzo Nobel NV
- Axalta Coating Systems
- BASF
- Beckers Group
- Behr Process LLC
- Benjamin Moore & Co.
- Cloverdale Paint Inc.
- Dunn-Edwards Corporation
- Hempel A/S
- Jotun
- Kansai Paint Co., Ltd
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- The Sherwin-Williams Company
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America paints and Coatings Market size in 2026 is estimated at USD 42.9 billion, growing from 2025 value of USD 41.82 billion with 2031 projections showing USD 48.78 billion, growing at 2.59% CAGR over 2026-2031.
This report is Segmented by Resin Type (Acrylics, Alkyd, Epoxy, Polyurethane, and Other Resin Types), Technology (Water-Borne, Solvent-Borne, and UV-Cured Coating), End-User Industry (Architectural, Automotive, Protective Coating, General Industrial, Transportation, and Packaging), and Geography (United States, Canada, and Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Paints And Coatings Market Trends and Insights
Surge in Commercial and Institutional Construction
Commercial outlays reached USD 180 billion in 2024, translating directly into greater demand for premium architectural coatings that meet strict indoor-air requirements. Healthcare builds alone represented USD 12 billion in coating-intensive projects as antimicrobial finishes became baseline specifications. Renovation cycles across logistics hubs, data centers, and educational facilities sustain high-margin orders for fire-retardant and static-dissipative paints. Low-emission mandates such as the South Coast Air Quality Management District cap of 50 g/L VOC further shift preference toward advanced water-borne lines. The driver, therefore, locks in steady architectural pull for the North American paints and coatings market.
Rapid Shift to Low-VOC Water-borne Technologies
Eighteen U.S. states now enforce VOC limits below federal thresholds, accelerating water-borne adoption across all usage classes. Architectural variants fetch 15-20% price premiums, cushioning margin pressure even as solvent inputs spike. Hybrid chemistries marry water clean-up with solvent-level endurance in protective segments, helping suppliers capture long-cycle industrial contracts. The regulatory tide effectively institutionalizes higher specification, lifting average selling prices within the North American paints and coatings market.
Volatile Petrochemical Raw-material Prices
Titanium dioxide swings of 25% per quarter and acrylic-monomer spikes of 30% keep procurement budgets unstable, eroding contractual margins for smaller players. Supply chain disruptions from Gulf Coast weather events and refinery maintenance cycles amplify price volatility, with Hurricane Beryl's 2024 impact on Texas petrochemical facilities demonstrating the sector's vulnerability to operational disruptions. Manufacturers with hedging programs and integrated resin capacity can shield profitability, hastening consolidation within the North American paints and coatings market.
Other drivers and restraints analyzed in the detailed report include:
- OEM Demand for High-performance Powder Coatings
- AI-driven Color-matching Platforms Accelerating Repaint Cycles
- Stringent and Diverging VOC Regulations Across North America
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acrylic systems occupied 37.12% of the North American paints and coatings market share in 2025, benefiting from balanced cost, weatherability, and color retention across architectural and automotive finishes. The sub-segment also captures early wins from bio-based feedstock innovation, meeting sustainability mandates without sacrificing performance. While smaller in absolute terms, polyurethane grades log the fastest 2.95% CAGR through 2031 on demand for high-abrasion durability in OEM assemblies. Epoxies stay indispensable in marine and infrastructure applications where chemical resistance outweighs initial cost concerns. Alkyd displacement accelerates as VOC norms tighten, yet modified alkyd-water hybrids prolong relevance in niche trim and primer roles. Blended chemistries that marry acrylic elasticity with polyurethane hardness present fertile ground for differentiated offerings inside the North American paints and coatings market.
In industrial maintenance and asset-protection projects, silicone and fluoropolymer niches command premium pricing due to extreme heat or chemical exposures, although their aggregate revenue share remains modest. Polyester resins gain ground in powder lines, reinforcing the zero-VOC narrative while delivering 25-year facade warranties for aluminum extrusions. Resin choice therefore centers less on commodity cost and more on life-cycle value as facility owners calculate total operating expense. Suppliers with cross-technology R&D capacity enjoy a service moat that newcomers struggle to replicate, reinforcing competitive stratification throughout the North American paints and coatings industry.
Complete Report Scope:
- By Resin Type
- Acrylics
- Alkyd
- Epoxy
- Polyester
- Polyurethane
- Other Resin Types
- By Technology
- Water-borne
- Solvent-borne
- Powder Coating
- UV-cured Coating
- By End-user Industry
- Architectural
- Automotive
- Wood
- Protective Coating
- General Industrial
- Transportation
- Packaging
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- 3M
- Akzo Nobel N.V.
- Axalta Coating Systems
- BASF
- Beckers Group
- Behr Process LLC
- Benjamin Moore & Co.
- Cloverdale Paint Inc.
- Dunn-Edwards Corporation
- Hempel A/S
- Jotun
- Kansai Paint Co., Ltd
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- The Sherwin-Williams Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Commercial and Institutional Construction
- 4.2.2 Rapid Shift to Low-VOC Water-borne Technologies
- 4.2.3 OEM Demand for High-performance Powder Coatings
- 4.2.4 AI-driven Color-matching Platforms Accelerating Repaint Cycles
- 4.2.5 Reshoring of US Manufacturing Boosting Anti-corrosion Demand
- 4.3 Market Restraints
- 4.3.1 Volatile Petrochemical Raw-material Prices
- 4.3.2 Stringent and Diverging VOC Regulations Across US/Canada/Mexico
- 4.3.3 Skilled-applicator Labor Shortage in Industrial Coatings
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Rivalry Among Existing Firms
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Acrylics
- 5.1.2 Alkyd
- 5.1.3 Epoxy
- 5.1.4 Polyester
- 5.1.5 Polyurethane
- 5.1.6 Other Resin Types
- 5.2 By Technology
- 5.2.1 Water-borne
- 5.2.2 Solvent-borne
- 5.2.3 Powder Coating
- 5.2.4 UV-cured Coating
- 5.3 By End-user Industry
- 5.3.1 Architectural
- 5.3.2 Automotive
- 5.3.3 Wood
- 5.3.4 Protective Coating
- 5.3.5 General Industrial
- 5.3.6 Transportation
- 5.3.7 Packaging
- 5.4 By Country
- 5.4.1 United States
- 5.4.2 Canada
- 5.4.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 3M
- 6.4.2 Akzo Nobel N.V.
- 6.4.3 Axalta Coating Systems
- 6.4.4 BASF
- 6.4.5 Beckers Group
- 6.4.6 Behr Process LLC
- 6.4.7 Benjamin Moore & Co.
- 6.4.8 Cloverdale Paint Inc.
- 6.4.9 Dunn-Edwards Corporation
- 6.4.10 Hempel A/S
- 6.4.11 Jotun
- 6.4.12 Kansai Paint Co., Ltd
- 6.4.13 Nippon Paint Holdings Co., Ltd.
- 6.4.14 PPG Industries, Inc.
- 6.4.15 RPM International Inc.
- 6.4.16 The Sherwin-Williams Company
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 東協油漆和塗料市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)中東油漆和塗料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)美國油漆和塗料:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)南美洲油漆和塗料市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 木榨油市場:全球市場預測(2026-2032)建築塗料市場:2026-2032年全球市場預測(依樹脂類型、技術、塗料類型、最終用途、通路和應用分類)
 全球油漆和塗料市場印度油漆和塗料市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)塗料市場:2026-2032年全球市場預測(依樹脂類型、技術、產品類型、基材、終端用戶產業及通路分類)
 建築塗料市場規模、佔有率和成長分析:按產品類型、技術、應用、最終用途、分銷管道和地區分類-產業預測,2026-2033年