


 |
市場調查報告書
商品編碼
2121503
歐洲農業曳引機和機械:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Europe Agricultural Tractor Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
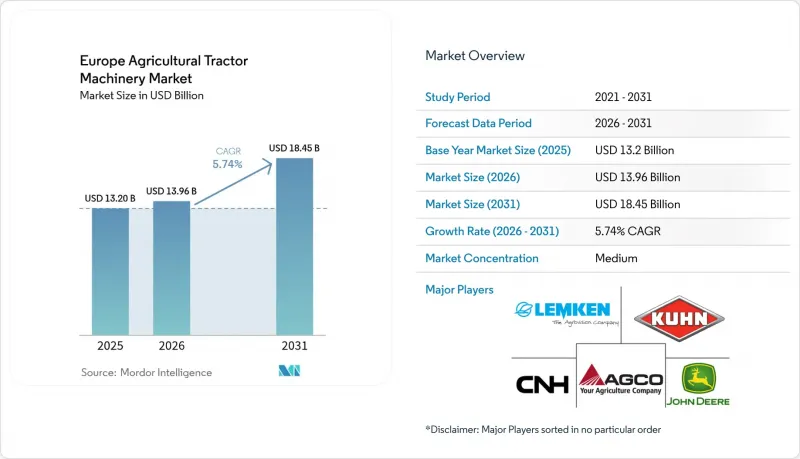
2025 年歐洲農業曳引機和機械市場價值 132 億美元,預計到 2031 年將達到 184.5 億美元,而 2026 年為 139.6 億美元,預測期(2026-2031 年)複合年成長率為 5.74%。
本報告依機械類型(犁地機械、播種機械等)及地區(德國、法國、義大利等)分類。市場預測以貨幣價值(美元)表示。
歐洲農業曳引機和機械市場趨勢及洞察
歐盟通用農業政策(CAP)(2025-2027 年框架)下的精密農業補貼
強制性生態補貼計畫確保25%的直接補貼用於證實能提高投入效率的項目,迫使農民購買變數播種機、相容ISOBUS的噴霧器和產量測繪感測器。法國、德國和波蘭正在推進此類設備的升級。這種推廣也加速了數據共用。在Terrena合作社,到2024年,38%的成員將為其農業設備安裝遙測系統,進而延長設備使用壽命15%。認證要求有利於符合ISO 11783標準的品牌,小規模供應商則被排除在補貼資格之外,因此需求集中在少數大規模遠端資訊處理生態系統中。
西歐和北歐的勞動力短缺正在加速對自動化的需求。
2024年,德國農業部門的全職員工人數較前一年減少了12%。荷蘭園藝業也面臨類似的勞動力短缺問題,加速了機器人播種機和視覺引導噴藥機的應用。迪爾公司報告稱,2024年其「See and Spray」(即視噴)系統在歐洲的出貨量成長了47%。丹麥農業公司透過引進15台全天候運作的自主割草機和壓扁機,將乾草收割的運作人事費用降低了30%。因此,歐洲農業曳引機和機械市場正朝著配備自主功能的動力農具方向發展,與傳統被動式農具的差距日益擴大。
經銷商自 2023 年以來累積的庫存將抑制新訂單,直至 2026 年。
2024年初,歐洲經銷商的農機庫存相當於9.2個月的用量,而通常情況下為5.5個月。 BayWa公司未售出的耕作和播種設備庫存累計3.4億歐元(約3.6億美元),並將其2025年的採購計畫削減了22%。法國經銷商InVivo也同樣將新訂單減少了18%,並將業務重心轉向翻新二手設備。儘管製造商已將付款期限延長至180天並提案寄售服務,但利潤率的壓力使得經銷商不願購買新機型,減緩了歐洲農用曳引機、機械和設備市場的短期成長。
細分市場分析
在歐洲農業曳引機和機械市場,犁地和中耕機械預計在2025年佔總銷售額的45.30%。受交通管制和即時可變施肥演算法推廣的推動,播種機預計到2031年將以7.66%的複合年成長率成長。法國合作社Axereal報告稱,透過在8.5萬公頃土地上實施GPS分區控制,每公頃種子成本降低了12%。
播種機械市場成長最為迅速,主要得益於政府提供的環保補貼,這些補貼專門獎勵減少種子浪費。萊姆肯公司(Lemken)的電動計量式「Azlit」播種機售價高出28%,但在500公頃或以上的農場,這筆投資可以在三個種植季內收回成本。乾草和飼料機械在歐洲牧場上仍然廣泛使用,但需求取決於酪農和牛數量的穩定性。其他專用機械的市場仍較為分散。這個細分市場反映出,補貼和數據驅動能力正在將更廣泛的歐洲農業曳引機、機械和設備市場的利潤轉移到動力驅動、軟體定義的機械。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟通用農業政策(CAP)下精密農業補貼(2025-2027財政年度)
- 在西歐和北歐,勞動力短缺正在加速對自動化的需求。
- 第五階段排放氣體法規鼓勵作業機具改造和更換,以提高動力輸出效率。
- 交通管制下農業的擴張增加了對輕便、寬幅耕作工具的需求。
- 地中海國家葡萄園和果園機械化程度的迅速提高
- 新興的電動曳引機生態系統需要低牽引力的 ISOBUS 相容農具。
- 市場限制因素
- 自 2023 年以來,經銷商庫存過剩一直抑制著新訂單,這種情況將持續到 2026 年。
- 東歐分散的小規模農田上智慧農機設備的高購買成本
- 複雜的互通性標準(ISOBUS、TIM)正在減緩中型農場的採用。
- 商品價格波動加劇了自由裁量權投資設備的農民的融資惡化。
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按機器類型
- 犁地和間耕機械
- 犁
- 光環
- 旋耕機和耕耘機
- 其他犁地和間耕機械
- 播種機
- 播種機
- 播種機
- 撒佈器
- 其他種植機械
- 乾草和飼料機械
- 收割機和調節器
- 打包機
- 其他乾草和飼料機械
- 噴霧器
- 其他類型
- 犁地和間耕機械
- 國家
- 德國
- 法國
- 義大利
- 英國
- 西班牙
- 荷蘭
- 波蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Deere & Company
- CNH Industrial NV
- AGCO Corporation
- Kubota Corporation(Kubota Corporation)
- CLAAS KGaA mbH
- Kuhn Group(Bucher Industries AG)
- Lemken GmbH & Co. KG
- SDF Group
- Mahindra & Mahindra Ltd
- Tractors and Farm Equipment Ltd
- Amazonen-Werke H. Dreyer SE
- Pottinger Landtechnik GmbH
- Vaderstad AB
- Maschio Gaspardo SpA
- Salford Group(Linamar Corporation)
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe agricultural tractor machinery market size was valued at USD 13.2 billion in 2025 and estimated to grow from USD 13.96 billion in 2026 to reach USD 18.45 billion by 2031, at a CAGR of 5.74% during the forecast period (2026-2031).
This report is Segmented by Machinery Type (Plowing and Cultivating Machinery, Planting Machinery, and More) and by Geography (Germany, France, Italy, and More). Market Forecasts are Provided in Terms of Value (USD).
Europe Agricultural Tractor Machinery Market Trends and Insights
Precision-Farming Subsidies Under the EU Common Agricultural Policy (2025-2027 Tranche)
Mandatory eco-schemes now channel 25% of direct payments into proven input-efficiency projects, pushing farms to buy variable-rate planters, ISOBUS sprayers, and yield-mapping sensors. France, Germany, and Poland are moving toward such upgrades. Adoption lifts data-sharing, cooperative Terrena saw 38% of members stream implement telemetry in 2024, extending equipment life by 15%. Certification requirements favor ISO 11783-compliant brands and squeeze fringe suppliers out of subsidy eligibility, consolidating demand around a few large telematics ecosystems.
Labor Shortages Accelerating Automation Demand in Western and Northern Europe
Full-time farm employment in Germany fell 12% year on year in 2024. Horticulture in the Netherlands faces similar gaps, spurring take-up of robotic planters and vision-guided sprayers. Deere and Company reported a 47% jump in European shipments of its See and Spray system during 2024. Danish Agro deployed 15 autonomous mower-conditioner units that cut hay harvest labor costs by 30% while running day and night. The Europe agricultural tractor machinery market, therefore, tilts toward powered implements with embedded autonomy, widening the gap with legacy passive tools.
Dealer Over-Inventory Amassed Since 2023 Suppressing Fresh Orders through 2026
European dealers carried 9.2 months of implement supply at the start of 2024 versus a normal 5.5 months. BayWa posted EUR 340 million (USD 360 million) in unsold tillage and seeding stock, then cut 2025 purchase plans by 22%. French distributor InVivo similarly trimmed new orders 18% and pivoted to refurbishing used assets. Manufacturers extended payment terms to 180 days and offered consignment, but the margin squeeze still discourages dealers from stocking incremental models, slowing near-term growth in the Europe agricultural tractor machinery market.
Other drivers and restraints analyzed in the detailed report include:
- Stage V Emissions Rules Propelling Retrofit and Replacement of PTO-Efficient Implements
- Growth of Controlled-Traffic Farming Boosting Demand for Lightweight, Wide-Working-Width Tillage Tools
- High Capital Cost for Smart Implements on Fragmented Small Holdings in Eastern Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plowing and cultivating machinery tools secured 45.30% of 2025 revenue in the Europe agricultural tractor machinery market. Planting machinery, aided by controlled-traffic mandates and real-time variable-rate algorithms, will grow at a 7.66% CAGR through 2031. French cooperative Axereal documented a 12% reduction in seed cost per hectare after rolling out GPS section control across 85,000 hectares.
Planting machinery capture the fastest expansion because eco-scheme payments specifically reward reductions in seed waste. Lemken's electric-meter Azurit planter sells at a 28% premium yet pays back within three seasons on farms above 500 hectares. Haying and forage machinery continue to serve the continent's grassland but hinge on stable dairy and beef herds. Other specialty implements remain fragmented. The segment illustrates how subsidy rules and data capability shift profits toward powered, software-defined machines within the wider Europe agricultural tractor machinery market size.
Complete Report Scope:
- By Machinery Type
- Plowing and Cultivating Machinery
- Plows
- Harrows
- Rotovators and Cultivators
- Other Plowing and Cultivating Machinery
- Planting Machinery
- Seed Drills
- Planters
- Spreaders
- Other Planting Machinery
- Haying and Forage Machinery
- Mowers and Conditioners
- Balers
- Other Haying and Forage Machinery
- Sprayers
- Other Types
- Plowing and Cultivating Machinery
- By Country
- Germany
- France
- Italy
- United Kingdom
- Spain
- Netherlands
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Deere & Company
- CNH Industrial N.V.
- AGCO Corporation
- Kubota Corporation (Kubota Corporation)
- CLAAS KGaA mbH
- Kuhn Group (Bucher Industries AG)
- Lemken GmbH & Co. KG
- SDF Group
- Mahindra & Mahindra Ltd
- Tractors and Farm Equipment Ltd
- Amazonen-Werke H. Dreyer SE
- Pottinger Landtechnik GmbH
- Vaderstad AB
- Maschio Gaspardo S.p.A.
- Salford Group (Linamar Corporation)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Precision-farming subsidies under the EU Common Agricultural Policy (CAP) (2025-2027 tranche)
- 4.2.2 Labor shortages accelerating automation demand in Western and Northern Europe
- 4.2.3 Stage V emissions rules driving retrofit and replacement of PTO-efficient implements
- 4.2.4 Growth of controlled-traffic farming boosting demand for lightweight, wide-working-width tillage tools
- 4.2.5 Surge in vineyard/orchard mechanization in Mediterranean countries
- 4.2.6 Emerging electric-tractor ecosystem requiring low-draw, ISOBUS-ready implements
- 4.3 Market Restraints
- 4.3.1 Dealer over-inventory since 2023 suppressing fresh orders through 2026
- 4.3.2 High capital cost for smart implements on fragmented small holdings in Eastern Europe
- 4.3.3 Complex interoperability standards (ISOBUS, TIM) delaying adoption among mid-size farms
- 4.3.4 Volatile commodity prices lowering farmers cash flow for discretionary equipment
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Threat of Substitutes
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Bargaining Power of Suppliers
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Machinery Type
- 5.1.1 Plowing and Cultivating Machinery
- 5.1.1.1 Plows
- 5.1.1.2 Harrows
- 5.1.1.3 Rotovators and Cultivators
- 5.1.1.4 Other Plowing and Cultivating Machinery
- 5.1.2 Planting Machinery
- 5.1.2.1 Seed Drills
- 5.1.2.2 Planters
- 5.1.2.3 Spreaders
- 5.1.2.4 Other Planting Machinery
- 5.1.3 Haying and Forage Machinery
- 5.1.3.1 Mowers and Conditioners
- 5.1.3.2 Balers
- 5.1.3.3 Other Haying and Forage Machinery
- 5.1.4 Sprayers
- 5.1.5 Other Types
- 5.1.1 Plowing and Cultivating Machinery
- 5.2 By Country
- 5.2.1 Germany
- 5.2.2 France
- 5.2.3 Italy
- 5.2.4 United Kingdom
- 5.2.5 Spain
- 5.2.6 Netherlands
- 5.2.7 Poland
- 5.2.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Deere & Company
- 6.4.2 CNH Industrial N.V.
- 6.4.3 AGCO Corporation
- 6.4.4 Kubota Corporation (Kubota Corporation)
- 6.4.5 CLAAS KGaA mbH
- 6.4.6 Kuhn Group (Bucher Industries AG)
- 6.4.7 Lemken GmbH & Co. KG
- 6.4.8 SDF Group
- 6.4.9 Mahindra & Mahindra Ltd
- 6.4.10 Tractors and Farm Equipment Ltd
- 6.4.11 Amazonen-Werke H. Dreyer SE
- 6.4.12 Pottinger Landtechnik GmbH
- 6.4.13 Vaderstad AB
- 6.4.14 Maschio Gaspardo S.p.A.
- 6.4.15 Salford Group (Linamar Corporation)
7 Market Opportunities and Future Outlook

 2026年全球農業曳引機機械市場報告
 越南農業曳引機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)非洲農業曳引機機械:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)中國農業曳引機市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)德國農業曳引機機械:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)亞太地區農業曳引機:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)北美農業曳引機:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)南美洲農業曳引機市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)美國農業曳引機機械:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)2026年全球果園曳引機市場報告