


 |
市場調查報告書
商品編碼
2116329
美國零售第三方物流:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)US Retail 3PL - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,美國零售 3PL 市場在 2026 年的價值將達到 571.7 億美元,高於 2025 年的 555.9 億美元,預計到 2031 年將達到 657.9 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 2.84%。
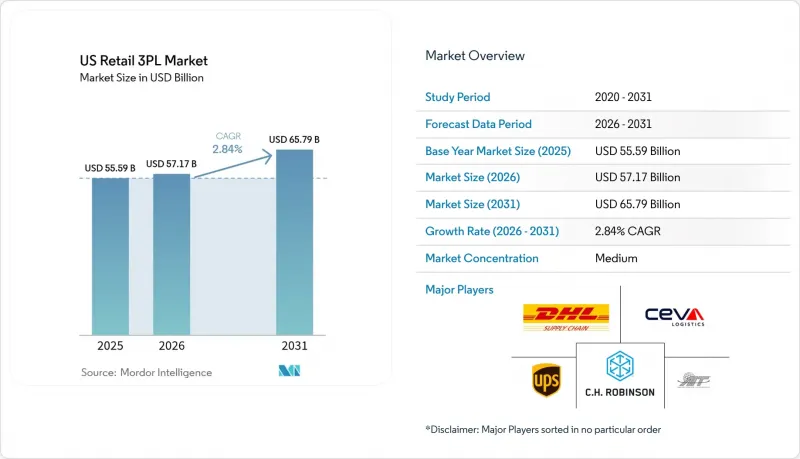
本報告按服務(例如,國內運輸管理)、產品(例如,食品飲料、個人護理和家居用品)、分銷管道(例如,超市/大賣場/便利商店、百貨公司)、物流模式(例如,輕資產、重資產)和地區(例如,東北部、中西部)進行分類。市場預測以美元計價。
美國零售第三方物流市場趨勢與洞察
超本地化當日送達正在徹底改變城市物流。
為了履行當日送達的承諾,零售商爭相獲取必要的倉儲空間,到2024年,美國主要大都會地區的倉庫空置率降至多年來的最低水準。第三方物流公司簽署的大規模租賃協議佔所有工業地產交易的35%,反映出企業正策略性地向都市區中心轉移,以縮短從下單到交付的時間。在人口密集的都市區,最後一公里配送的平均成本達到每件包裹10.10美元,較去年同期成長12%。這促使企業對人工智慧驅動的路線最佳化工具進行大規模投資,以減少里程和司機的工作時間。擁有獨特微型倉配模式的供應商可以減少長途運輸的拆分,降低分批出貨的機率,並從要求當日送達保證的全通路零售商獲得更高的價格。
生鮮食品和食材自煮包的網路購買正在推動低溫運輸。
2024年,美國消費者加快了線上食品雜貨購物的步伐,推動了對能夠靈活切換冷凍、冷藏和常溫區域的溫控倉儲空間的需求。 Lineage Logistics和Americold等領先的物流整合公司透過併購擴大了其網路,獲得了投資高密度自動化系統的資金,從而提高了溫度控制精度並降低了能源成本。將基於路線的遠端資訊處理技術與即時貨物監控相結合的第三方物流公司,正在與需要在大都會圈中心地帶提供兩小時以內送達服務的食材自煮包供應商簽訂多年期合約。
疫情後電子商務的正常化
2025年第一季,國內貨運量再次萎縮,貨運指數年減13.8%,導致部分第三方物流網路出現運力過剩。為了在需求復甦前維持獲利,營運商正加大力度整合微型倉配中心、轉租閒置的轉運站,並專注於服務交付成本分析。
細分市場分析
預計到2025年,零售第三方物流市場中,國內運輸管理將佔最大佔有率,佔銷售額的46.35%,而增值倉儲和配送預計將以3.65%的複合年成長率成長。零售商對庫存延遲、套件組裝以及面向直接消費者(DTC)配送的揀貨包裝工作流程的需求不斷成長,推動了多溫控和高週轉率倉庫資產的重要性。隨著全通路庫存策略的日益普及,增值倉儲和配送在零售第三方物流市場的佔有率預計將會擴大。將機器人、自動化倉庫系統(AS/RS)和即時倉庫執行軟體結合的供應商能夠縮短週期時間,從而為客戶帶來可衡量的銷售成長。零售商倉庫營運的外包率已從43%上升至65%,凸顯了營運策略的轉變,這使得第三方物流公司在投資下一代履約編配時獲得了優勢。相較之下,儘管運輸管理對於長途補貨仍然至關重要,但隨著合約競標週期加劇,托運人尋求最佳化運輸方式以應對低迷的貨運指數,其利潤率面臨壓力。然而,那些增加採購平台和基於API的競標視覺化功能的貨運仲介業者可以從小規模托運人那裡獲得更多市場佔有率。在整個預測期內,零售第三方物流市場的資本配置方式預計將不再由純粹的資產管理主導,而是由服務差異化主導。
國內運輸管理專家正在重組其運營,以提供端到端的控制塔可視性,並與倉庫管理系統和退貨網路同步。由於預計到2024年,標準整車貨運經紀的利潤率仍將維持在個位數低位,因此供應商正在加速進軍高附加價值領域,例如交叉轉運提貨、共乘配送和出庫小包裹分揀。隨著合約貨運價格趨於穩定,採用數位化貨物匹配和預測定價演算法的輕資產仲介可以維持其市場佔有率。同時,採用「貨到人 (GTP)」機器人技術的增值倉儲 (VAWD) 創新者可以將揀貨員的生產力提高到人工作業區域的3-4倍,從而在不相應增加人員配置的情況下實現更高的處理能力。此外,由於冷藏設施的公用事業費用目前佔倉庫總支出的12%,因此投資節能型冷凍設備至關重要。透過整合可再生能源供應合約和電池儲能,總營運成本可降低 200 至 300 個基點,從而使生鮮食品合約的競標更具競爭力。
到2025年,食品飲料業將佔銷售額的27.60%,這反映了其全年高周轉率以及對溫控處理的需求。同時,時尚生活產業預計將以5.28%的複合年成長率在所有產品類型中位居榜首,這主要得益於電子商務的快速滲透、季節性SKU週轉以及快速庫存週轉的重要性。由於服裝退貨率徘徊在近50%的水平,逆向物流正在從成本中心轉變為加值服務,從而提高了能夠在48小時內完成服裝分揀、熨燙和重新包裝的合作夥伴公司的利潤率。市場對能夠透過衣架運輸、RFID托盤追蹤以及個人化客製化和刺繡等附加價值服務來最佳化設施佈局以適應服裝工作流程的專家的需求日益成長。
食品飲料產業將繼續成為固定資產部署的支柱產業,尤其是在人口稠密的沿海大都會圈,低溫運輸中心更是如此。配備彈性分區貨架系統的多租戶設施使供應商能夠根據產品種類的變化調整溫度區域。個人護理和家居護理產品需要嚴格的批次追溯,這推動了對符合現行良好生產規範 (GMP) 認證的第三方物流 (3PL) 供應商的需求。家具物流中心採用「白手套」服務模式處理超大尺寸的 SKU 和最後一公里配送團隊,員工接受過上門組裝訓練。同時,在電子和家電產業,第三方物流供應商必須整合安全籠、保稅區和鋰電池合規協議。每個子部門都蘊藏著尚未開發的市場,擁有品類專業知識和全國性業務佈局的新興參與企業可以開拓這些市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對主要大都會圈超本地化當日送達服務的期望
- 在線購買生鮮食品和食材自煮包正迅速流行起來。
- 時尚商品退貨率飆升,推動了專業逆向物流的發展。
- 門市自履約(BOPIS/門市出貨)正在徹底改變補貨流程。
- 在旺季期間,「突發事件」導致對備用容量的需求激增,需求彈性較大。
- 市場限制因素
- 疫情後非必需零售業電子商務成長率正常化。
- 消費者對不斷上漲的物價感到疲倦,這抑制了高價商品的網路購買和倉儲需求。
- 對「綠色通道」的懷疑:買家會避開擁有長途配送網路的零售商。
- 價值供應鏈分析
- 行業政策和法規
- 物流業的技術進步
- 波特五力模型
- 地緣政治事件對市場的影響
第5章 市場規模及成長預測(價值,10億美元)
- 按服務
- 國內運輸管理
- 道路運輸
- 鐵路運輸
- 空運
- 水運
- 國際運輸管理
- 道路運輸
- 鐵路運輸
- 空運
- 水運
- 加值倉儲與物流 (VAWD)
- 國內運輸管理
- 依產品
- 食品/飲料
- 個人護理和居家護理
- 時尚與生活方式(配件、服裝、鞋履)
- 家具
- 電子設備及電器產品
- 其他產品
- 透過分銷管道
- 超市/大賣場/便利商店和百貨公司
- 專賣店
- 線上
- 其他頻道
- 透過物流模型
- 輕資產(託管)
- 資產密集型(公司自有車輛和倉庫)
- 混合
- 按地區
- 東北
- 中西部
- 西南
- 東南
- 西方
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- DHL Supply Chain
- CEVA Logistics
- AIT Worldwide Logistics
- United Parcel Service, Inc.
- CH Robinson Worldwide, Inc.
- Kuehne+Nagel International AG
- FedEx Logistics, Inc.
- GXO Logistics, Inc.
- Expeditors International of Washington, Inc.
- CJ Logistics America, LLC
- Hub Group, Inc.
- ShipMonk LLC
- XPO Logistics, Inc.
- Ryder System, Inc.
- Geodis Americas, LLC
- NFI Industries
- Radial, Inc.
- Saddle Creek Logistics Services
- Ingram Micro Commerce and Lifecycle Services
- Americold Logistics, LLC
- Lineage Logistics Holdings, LLC
- Stord, Inc.
第7章 市場機會與未來展望
第8章附錄
- 總體經濟指標
- 外貿統計數據
- 主要出口目的地和進口來源
According to Mordor Intelligence, the US retail 3PL market size in 2026 is estimated at USD 57.17 billion, growing from 2025 value of USD 55.59 billion with 2031 projections showing USD 65.79 billion, growing at 2.84% CAGR over 2026-2031.
This report is Segmented by Service (Domestic Transportation Management and More), by Product (Food and Beverages, Personal and Household Care and More), by Distribution Channel (Super/Hyper/Convenience and Department Stores and More), by Logistics Model (Asset-Light, Asses-Heavy and More), by Geography (Northeast, Midwest and More). The Market Forecasts are Provided in Terms of Value (USD).
US Retail 3PL Market Trends and Insights
Hyper-local Same-day Delivery Reshapes Urban Logistics
Warehouse vacancy in primary U.S. metros fell to multi-year lows in 2024 as retailers raced to secure infill space required to meet same-day promises. Large-format leases signed by 3PLs accounted for 35% of total industrial activity, reflecting a strategic shift toward urban nodes that compress order-to-door times. The average last-mile delivery cost in dense urban zones reached USD 10.10 per package, up 12% year-over-year, prompting heavy investment in AI-driven routing tools that compress mileage and driver hours. Providers with proprietary micro-fulfillment designs can cut line-haul splits, reduce split-shipments, and capture premium pricing from omnichannel retailers searching for guaranteed same-day coverage.
Online Fresh-Food and Meal-Kit Purchases Drive Cold-Chain Expansion
U.S. consumers accelerated adoption of online grocery baskets in 2024, increasing demand for temperature-controlled square footage that can flex between frozen, chilled, and ambient zones. Major consolidators such as Lineage Logistics and Americold scaled networks through M&A, unlocking capital for high-density automation that sharpens temperature precision and trims energy cost curves. 3PLs bundling route-level telematics and real-time load monitoring are securing multi-year contracts from meal-kit providers that require two-hour delivery windows in metro cores.
Post-pandemic E-commerce Normalization
Domestic freight volumes contracted again in Q1 2025, with shipment indices down 13.8% year-over-year, leaving some 3PL networks over-capacitated. Operators are consolidating micro-fulfillment footprints, sub-leasing unused cross-docks, and doubling down on cost-to-serve analytics to defend margins until demand rebounds.
Other drivers and restraints analyzed in the detailed report include:
- Fashion Returns Accelerate Specialized Reverse Logistics
- Store-based Fulfillment Alters Replenishment Flow
- Consumer Inflation Fatigue
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Value-Added Warehousing and Distribution generated the fastest 3.65% CAGR outlook, even though Domestic Transportation Management accounted for the single-largest 46.35% revenue slice within the Retail third-party logistics market in 2025. Rising retailer appetite for inventory postponement, kitting, and direct-to-consumer pick-and-pack workflows elevates multi-temperature and high-velocity warehousing assets. The Retail third-party logistics market size allocated to VAWD is projected to widen its share as omni-inventory strategies gain traction. Providers combining robotics, automated storage and retrieval systems, and real-time warehouse execution software deliver cycle-time reductions that translate into measurable sell-through gains for clients. Retailers increased their outsourced warehousing penetration from 43% to 65%, underscoring a strategic handoff that favors 3PLs investing in next-generation fulfillment orchestration. In contrast, Transportation Management remains pivotal for long-haul replenishment yet faces margin compression as contract bid cycles intensify and shippers pursue mode optimization to counter softer freight indices. Still, freight brokerages that add procurement platforms and API-based tender visibility can capture incremental wallet share from smaller shippers. Over the forecast horizon, service differentiation rather than pure asset control is expected to reshape how the Retail third-party logistics market allocates capital.
Domestic Transportation Management specialists are re-positioning to provide end-to-end control tower visibility that syncs with warehouse management systems and returns networks. Standard truckload brokerage margins averaged in the low single digits during 2024, spurring providers to bolt on value-add segments such as cross-dock consolidation, pool distribution, and outbound parcel sortation. As contract rates stabilize, asset-light brokers that embed digital freight matching and predictive pricing algorithms can defend their share. Meanwhile, VAWD innovators that deploy goods-to-person robotics can lift picker productivity by 3-4 x relative to manual zones, enabling higher throughput without proportional headcount increases. Energy-efficient refrigeration investments are also critical because utility costs now account for 12% of total warehouse expense for chilled facilities. Integrating renewable power agreements and battery storage can carve 200-300 basis points off total operating costs, enhancing competitive bids for fresh-food contracts.
Foods and Beverages commanded 27.60% revenue in 2025, reflecting the category's year-round velocity and temperature-sensitive handling needs. Yet Fashion and Lifestyle is slated for a 5.28% CAGR, the steepest among product silos, underpinned by surging e-commerce penetration, seasonal SKU turnover, and return-to-stock speed imperatives. Apparel returns hovering near 50% convert reverse logistics from cost center to premium service, widening margin pools for partners that can grade, steam, and re-package apparel within 48 hours. Garment-on-hanger transport, RFID pallet tracking, and value-added services such as personalization or embroidery amplify the need for specialists capable of tailoring facility layouts to apparel workflows.
Foods and Beverages will continue to anchor fixed-asset deployment, particularly in cold-chain nodes accessible to high-density coastal metros. Multi-tenant facilities equipped with zone-flexing racking systems allow providers to adjust temperature bands as product mix shifts. Personal and Household Care products require strict batch-lot traceability, driving demand for 3PLs certified under current good manufacturing practices. Furniture logistics centers handle outsized SKUs and white-glove final-mile crews trained in in-home assembly, while Electronics and Appliances push 3PLs to integrate secure cages, bonded zones, and lithium battery compliance protocols. Each sub-sector presents addressable white-space for niche entrants that pair category expertise with national reach.
Complete Report Scope:
- By Service
- Domestic Transportation Management
- Roadways
- Railways
- Airways
- Waterways
- International Transportation Management
- Roadways
- Railways
- Airways
- Waterways
- Value-Added Warehousing and Distribution (VAWD)
- Domestic Transportation Management
- By Product
- Foods and Beverages
- Personal and Household Care
- Fashion and Lifestyle (accessories, apparel, footwear)
- Furniture
- Electronics and Household Appliances
- Other Products
- By Distribution Channel
- Super/Hyper/Convenience and Department Stores
- Specialty Stores
- Online
- Other Channels
- By Logistics Model
- Asset-Light (Management-Based)
- Asset-Heavy (Own Fleet and Warehouses)
- Hybrid
- By Geography
- Northeast
- Midwest
- Southwest
- Southeast
- West
List of Companies Covered in this Report:
- DHL Supply Chain
- CEVA Logistics
- AIT Worldwide Logistics
- United Parcel Service, Inc.
- C.H. Robinson Worldwide, Inc.
- Kuehne + Nagel International AG
- FedEx Logistics, Inc.
- GXO Logistics, Inc.
- Expeditors International of Washington, Inc.
- CJ Logistics America, LLC
- Hub Group, Inc.
- ShipMonk LLC
- XPO Logistics, Inc.
- Ryder System, Inc.
- Geodis Americas, LLC
- NFI Industries
- Radial, Inc.
- Saddle Creek Logistics Services
- Ingram Micro Commerce and Lifecycle Services
- Americold Logistics, LLC
- Lineage Logistics Holdings, LLC
- Stord, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hyper-local same-day delivery expectation in major metros
- 4.2.2 Rapid penetration of online fresh-food and meal-kit purchases
- 4.2.3 Soaring fashion return rates driving specialized reverse logistics
- 4.2.4 Store-based fulfillment (BOPIS / ship-from-store) reshaping replenishment flows
- 4.2.5 Peak-season "flash event" surges demanding elastic overflow capacity
- 4.3 Market Restraints
- 4.3.1 Post-pandemic normalization of e-commerce growth rates in discretionary retail
- 4.3.2 Consumer inflation fatigue curbing high-ticket online purchases and warehousing demand
- 4.3.3 "Green-miles" skepticism-buyers avoiding retailers with long-haul fulfillment footprints
- 4.4 Value / Supply-Chain Analysis
- 4.5 Industry Policies and Regulations
- 4.6 Technological Developments in Logistics industry
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Geopolitical Events on the Market
5 Market Size and Growth Forecasts (Value, USD Bn)
- 5.1 By Service
- 5.1.1 Domestic Transportation Management
- 5.1.1.1 Roadways
- 5.1.1.2 Railways
- 5.1.1.3 Airways
- 5.1.1.4 Waterways
- 5.1.2 International Transportation Management
- 5.1.2.1 Roadways
- 5.1.2.2 Railways
- 5.1.2.3 Airways
- 5.1.2.4 Waterways
- 5.1.3 Value-Added Warehousing and Distribution (VAWD)
- 5.1.1 Domestic Transportation Management
- 5.2 By Product
- 5.2.1 Foods and Beverages
- 5.2.2 Personal and Household Care
- 5.2.3 Fashion and Lifestyle (accessories, apparel, footwear)
- 5.2.4 Furniture
- 5.2.5 Electronics and Household Appliances
- 5.2.6 Other Products
- 5.3 By Distribution Channel
- 5.3.1 Super/Hyper/Convenience and Department Stores
- 5.3.2 Specialty Stores
- 5.3.3 Online
- 5.3.4 Other Channels
- 5.4 By Logistics Model
- 5.4.1 Asset-Light (Management-Based)
- 5.4.2 Asset-Heavy (Own Fleet and Warehouses)
- 5.4.3 Hybrid
- 5.5 By Geography
- 5.5.1 Northeast
- 5.5.2 Midwest
- 5.5.3 Southwest
- 5.5.4 Southeast
- 5.5.5 West
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global overview, Market overview, Core Segments, Financials, Strategy, Rank/Share, Products and Services, Recent Developments)
- 6.4.1 DHL Supply Chain
- 6.4.2 CEVA Logistics
- 6.4.3 AIT Worldwide Logistics
- 6.4.4 United Parcel Service, Inc.
- 6.4.5 C.H. Robinson Worldwide, Inc.
- 6.4.6 Kuehne + Nagel International AG
- 6.4.7 FedEx Logistics, Inc.
- 6.4.8 GXO Logistics, Inc.
- 6.4.9 Expeditors International of Washington, Inc.
- 6.4.10 CJ Logistics America, LLC
- 6.4.11 Hub Group, Inc.
- 6.4.12 ShipMonk LLC
- 6.4.13 XPO Logistics, Inc.
- 6.4.14 Ryder System, Inc.
- 6.4.15 Geodis Americas, LLC
- 6.4.16 NFI Industries
- 6.4.17 Radial, Inc.
- 6.4.18 Saddle Creek Logistics Services
- 6.4.19 Ingram Micro Commerce and Lifecycle Services
- 6.4.20 Americold Logistics, LLC
- 6.4.21 Lineage Logistics Holdings, LLC
- 6.4.22 Stord, Inc.
7 Market Opportunities and Future Outlook
8 Appendix
- 8.1 Macroeconomic Indicators
- 8.2 External Trade Statistics
- 8.3 Key Export Destinations and Import Origins

 第三方物流(3PL) 市場:依服務類型、運輸方式、最終用戶和地區分類
 零售第三方物流:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)英國第三方物流(3PL):市場佔有率分析、產業趨勢與統計數據以及成長預測 (2026-2031)印度第三方物流:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)德國第三方物流(3PL):市場佔有率分析、產業趨勢與統計及成長預測 (2026-2031)法國第三方物流(3PL):市場佔有率分析、產業趨勢與統計及成長預測 (2026-2031)
 LLM精細化服務市場規模、佔有率、成長及全球產業分析、區域趨勢及2026年至2034年預測
 第三方化學品分銷市場:全球市場預測,2026-2032年第三方物流軟體市場:全球市場預測,2026-2032年第三方物流市場-2026-2032年全球市場預測