


 |
市場調查報告書
商品編碼
2163365
Camera Link HS介面組件:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031年)Camera Link HS Interface Components - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
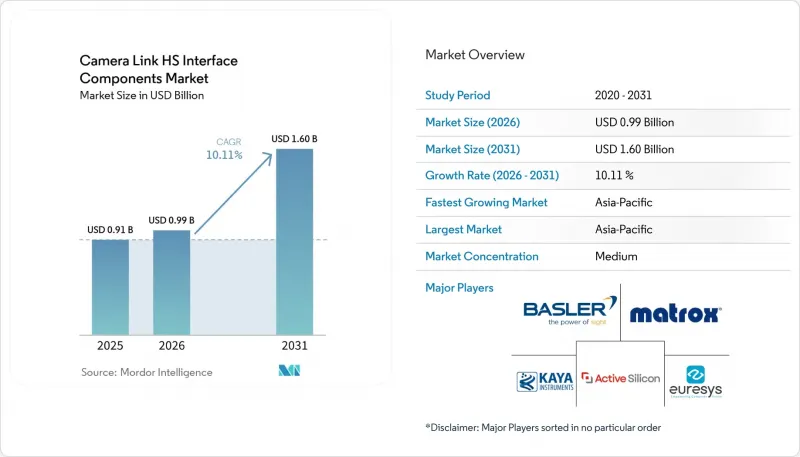
根據 Mordor Intelligence 預測,Camera Link HS 介面組件市場規模預計將在 2025 年達到 9.1 億美元,2026 年達到 9.9 億美元,到 2031 年達到 16 億美元,2026 年至 2031 年的複合年成長率為 10.11%。
全球Camera Link HS介面組件市場趨勢與洞察
對高解析度、高影格速率機器視覺的需求日益成長。
像素尺寸小、解析度高的相機感測器對感測器與影像擷取系統之間的介面提出了很高的要求。在需要持續高資料傳輸速率的生產環境中,並行LVDS Camera Link系統變得不切實際。 2026年8月,Teledyne DALSA推出了Falcon4-CLHS M8200-Scientific,它配備了8192 x 8192像素的感測器,像素尺寸為2.5微米,最高影格速率可達65 fps。其公佈的規格參數滿足生命科學和測量領域大尺寸成像所需的處理容量要求。當使用者不僅需要高頻寬,還需要可預測的影像傳輸,Camera Link HS介面組件市場將受益匪淺。此外,CLHS資料包化允許對感興趣區域進行逐幀更改,從而使單一相機能夠處理同一生產線上的各種檢測任務。該標準對GenICam和訊息協議的支持,使得系統建構者能夠整合來自不同供應商的設備。
半導體和電子設備測試的擴展
半導體檢測設備需要在保持先進製造製程所需吞吐量的同時,檢測出更精細的表面缺陷。 2026年3月,安拓創新(Onto Innovation)發布了「蜻蜓G5」(Dragonfly G5)檢測系統,將缺陷檢測靈敏度提升至150奈米,吞吐量更是上一代設備的五倍。先進的封裝、環柵(GoA)結構和高頻寬記憶體堆疊需要寬廣的影像覆蓋範圍和精確的測量。這推動了Camera Link HS介面組件市場的發展,因為攝影機和影像擷取卡的選擇通常在偵測平台的設計階段就已確定。安裝在製造工廠的設備在其整個運作期間都能滿足對替換零件的需求。日本工業影像協會(JIA)是Camera Link HS標準的相關組織之一,致力於提高日本設備供應商對此標準的認知度。中國供應商也在開發協議棧,以減少對進口組件的依賴。
過渡到 CoaXPress 和高速乙太網路替代方案
CoaXPress v2.0 透過四個 micro-BNC 連接聚合高達 50 Gbps 的頻寬,並可透過同一根同軸電纜供電。這減少了工廠環境中的安裝工作量,否則這些環境需要單獨的電源基礎設施。 2026 年 4 月,Basler 發布了一款基於光纖的 CoaXPress TDI 視覺系統,該系統將 imaFlex 2 Dual 100 幀採集卡與一台 500 kHz、16K 線速的攝影機相結合。 Emergent Vision Technologies 也於 2026 年 6 月開始出貨配備 QSFP28 光纖介面的 100GigE 攝影機。這些方案在支援乙太網路調度和優先考慮透過電纜供電的系統中具有競爭力。同時,在低抖動和長距離光纖傳輸至關重要的領域,Camera Link HS 介面組件市場仍佔有一席之地。
細分市場分析
2025年,CLHS相機在Camera Link HS介面組件市場佔據35.87%的佔有率。這一佔有率反映了面陣掃描和線陣掃描相機的高昂單價,以及通常先更換相機後更換影像擷取卡的設備升級順序。 Teledyne DALSA的Falcon4-CLHS系列相機解析度從280萬像素到6700萬像素不等,其最快配置的影格速率可達1200 fps。 Linea HS2 8K相機於2026年6月發布,它採用背照式TDI CMOS感測器,線速率高達1 MHz,可在低光照環境下實現高速成像。影像擷取卡是下一個重要的元件,因為它將相機連接到主機系統並支援FPGA處理。 KAYA Instruments、Gidel、BitFlow和Euresys等公司提供支援影像擷取和預處理的可程式平台。
CLHS FPGA IP 核能和開發套件市場預計將在 2026 年至 2031 年間以 13.27% 的複合年成長率成長。 A3 的 VHDL-93 IP 核支援在 Altera、Xilinx 和 Microsemi FPGA 平台上進行 CLHS 開發,從而減少對專有晶片組的依賴。 Camera Link HS 介面組件產業還包括電纜、光組件、介面板、夾層卡、訊號轉換器、訊號增程器、模擬器和測試設備。訊號轉換器和增程器在電纜長度超過 300 公尺的航太和科學系統中至關重要。相機模擬器可讓工程師在採購相機之前使用受控資料模式測試資料採集流程,從而降低整合多個硬體和軟體供應商的系統中的檢驗風險。更廣泛的元件選擇使用戶能夠建立基於通用CLHS 介面的系統。
到2025年,M協議的市佔率將達到62.53%。其部署記錄主要基於在長度不超過15公尺的CX4銅纜線路上運行的3.125–5 Gbps的設計。其8b/10b編碼方案相對容易在注重成本的FPGA設計中實現。許多測試設備供應商在10 Gbps光纖部署高成本較高時就採用了M協定。這種部署基礎持續支撐著M協定在設備替換和升級專案中的需求。此外,它還為設備所有者提供了一個適用於中端應用的熟悉介面。
X協議預計在2026年至2031年間將以13.83%的複合年成長率成長。 A3 CLHS v1.2規範支援使用相同的IP核心和商用SFP28、QSFP28和MPO光學模組,實現從10 Gbps到25 Gbps的過渡。其64b/66b編碼和前向糾錯能力使其適用於科學儀器、大規模工廠佈局和航太成像中的長距離光纖鏈路。 A3也描述了一種使用相同核心並透過橋接至128位元SerDes輸入,實現每通道50 Gbps傳輸速率的方法。這將使供應商能夠在不完全重新設計介面的情況下提高容量。該協定對確定性光纖鏈路的適用性凸顯了其在Camera Link HS介面組件市場中的地位。
區域分析
2026年,亞太地區佔Camera Link HS介面組件銷售額的39.81%,成為該地區市佔率最大的區域市場。預計到2031年,該地區將以12.47%的複合年成長率成長,成長速度在所有地區中位居榜首。這一地位反映了該地區主要半導體和電子產品生產基地的集中,包括中國、韓國、台灣和日本。新的製造能力和對先進封裝技術的投資正在推動對檢測系統的需求。泰萊視覺解決方案公司在2026年3月於上海舉行的中國國際視覺技術展覽會(Vision China)上發布了採用CLHS技術的成像產品。此次發布重點介紹了晶圓測量、顯示器檢測和工廠自動化等應用。
在Camera Link HS介面組件市場,北美和歐洲佔據了剩餘銷售額的大部分,這主要得益於科學成像、航太、國防和專業系統整合等領域的需求。北美採購的例子是,NASA戈達德太空飛行中心採用BitFlow公司的Axion-CL影像擷取卡,用於對其InGaAs短波紅外線相機進行地面輻射測試。歐洲擁有高度集中的機器視覺生態系統,其中包括Silicon Software、Euresys以及德國的設備供應商。 EMVA已聯合認可CLHS標準,促進了歐洲檢測設備開發商對該標準的採用。 Gidel在斯圖加特舉行的VISION 2026航太與國防創新之旅上展示了其FantoVision FPGA平台。
在南美洲,巴西的汽車零件供應商和阿根廷的電子組裝企業已率先採用了CLHS。中東和非洲是Camera Link HS介面組件市場的新興採購區域,沙烏地阿拉伯和阿拉伯聯合大公國等國防企業對機載監視和遠端偵察系統有需求。這些系統可能需要超過300公尺的光纖鏈路。該市場面臨這些地區合格整合商短缺的挑戰。本機系統建置商可能需要外部支援來試運行和檢驗。 A3的VHDL IP核和產品註冊計劃使開發人員能夠建立CLHS產品而無需依賴專有協議,從而逐步提高本地實施能力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對高解析度、高影格速率機器視覺的需求日益成長。
- 半導體和電子設備測試領域的擴展
- 人工智慧驅動的工業自動化和邊緣處理的成長
- 確定性低延遲成像鏈路的廣泛應用
- 航太和國防領域對抗輻射性和遠端成像的要求
- 可重複使用的開放式 CLHS IP 核降低了設計和採用的門檻。
- 市場限制因素
- 向CoaXPress和高速乙太網路替代技術過渡
- 高昂的系統整合和檢驗成本
- 原生 CLHS 攝影機和認證整合商數量有限。
- 介面晶片組的過時以及對專有韌體的依賴
- 宏觀經濟因素對市場的影響
- 產業供應鏈分析
- 科技趨勢
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 依組件類型
- CLHS相機
- CLHS 幀抓取器
- CLHS介面板與夾層卡
- CLHS電纜和光纖組件
- CLHS訊號轉換器和增程器
- CLHS FPGA IP 核子和開發套件
- CLHS相機模擬器和測試設備
- 根據協議
- M協定
- X協定
- 按頻道數
- 單通道
- 雙通道
- 多通道
- 按最終用戶行業分類
- 工業自動化和機械製造商
- 電子和半導體製造商
- 汽車製造商和一級供應商
- 醫療設備與生命科學相關組織
- 航太和國防相關組織
- 研究機構和大學
- 系統整合商和合約測試服務提供商
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Teledyne Digital Imaging, Inc.
- Matrox Electronic Systems Ltd.
- BitFlow, Inc.
- Euresys SA
- Active Silicon Limited
- KAYA Instruments Ltd.
- Gidel Ltd.
- Basler AG
- Imperx, Inc.
- Pleora Technologies Inc.
- Adimec Advanced Image Systems BV
- Silicon Software GmbH
- Photonfocus AG
- Vieworks Co., Ltd.
- JAI A/S
- Allied Vision Technologies GmbH
- EPIX, Inc.
- Hefei I-TEK Opto-Electronics Co., Ltd.
- Beijing JoinHope Image Technology Co., Ltd.
- Beijing Daheng Image Vision Co., Ltd.
- NED Image Technology Co., Ltd.
- IO Industries Inc.
- Optronis GmbH
- Mikrotron GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the camera link HS interface components market size is projected to be USD 0.91 billion in 2025, USD 0.99 billion in 2026, and reach USD 1.60 billion by 2031, expanding at a CAGR of 10.11% from 2026 to 2031.
Global Camera Link HS Interface Components Market Trends and Insights
Rising Demand for High-Resolution, High-Frame-Rate Machine Vision
Camera sensors with smaller pixels and higher resolutions place greater strain on the interface between the sensor and the acquisition system. Parallel LVDS Camera Link systems become less practical when production environments require sustained high data transfer rates. Teledyne DALSA launched the Falcon4-CLHS M8200-Scientific in August 2026 with an 8,192 X 8,192 sensor, 2.5-micrometer pixels, and frame rates up to 65 fps. Its stated specifications demonstrate the throughput requirement for large-format imaging in life sciences and metrology. The Camera Link HS Interface Components Market benefits when users require predictable image transfer rather than only high bandwidth. CLHS packetization also allows the region of interest to vary from frame to frame, enabling a single camera to support varied inspection tasks on the same line. The standard's GenICam and message protocol support helps system builders pair equipment from different vendors.
Expansion of Semiconductor and Electronics Inspection
Semiconductor inspection equipment must identify smaller surface defects while maintaining the throughput needed in advanced manufacturing. Onto Innovation introduced the Dragonfly G5 inspection system in March 2026, with defect sensitivity down to 150 nm and throughput up to 5 times higher than predecessor tools. Advanced packaging, gate-all-around structures, and high-bandwidth memory stacks require wide image coverage and precise measurements. This supports the Camera Link HS Interface Components Market because camera and frame-grabber choices are often set when an inspection platform is designed. Equipment installed in fabrication plants can sustain demand for replacement components during its operating life. The Japan Industrial Imaging Association remains one of the organizations associated with the Camera Link HS standard, helping to raise its visibility among Japanese equipment suppliers. Chinese suppliers are also developing protocol stacks to reduce reliance on imported components.
Migration to CoaXPress and High-Speed Ethernet Alternatives
CoaXPress v2.0 can aggregate up to 50 Gbps over 4 Micro-BNC connections and deliver power over the same coaxial cable. This can reduce installation work in factory environments that would otherwise require separate power infrastructure. Basler introduced a CoaXPress-over-Fiber TDI vision system in April 2026, including the imaFlex 2 Dual 100 frame grabber and a 500 kHz, 16K-line-rate camera. Emergent Vision Technologies also began shipping 100GigE cameras with QSFP28 fiber interfaces in June 2026. These alternatives can compete for systems that accept Ethernet scheduling behavior or prioritize power over cable. The Camera Link HS Interface Components Market retains its position where low jitter and long fiber reach are essential.
Other drivers and restraints analyzed in the detailed report include:
- Growth of AI-Enabled Industrial Automation and Edge Processing
- Increasing Adoption of Deterministic, Low-Latency Imaging Links
- High System Integration and Validation Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
CLHS cameras held 35.87% of the Camera Link HS Interface Components Market share in 2025. Their position reflected the high unit value of area-scan and line-scan cameras and the usual order of equipment upgrades, where cameras are replaced before frame grabbers. Teledyne DALSA's Falcon4-CLHS family covers resolutions from 2.8 megapixels to 67 megapixels and frame rates up to 1,200 fps in its fastest configuration. The Linea HS2 8K camera, released in June 2026, combines a backside-illuminated TDI CMOS sensor with a maximum line rate of 1 MHz for low-light, high-speed imaging. Frame grabbers are the next major component group because they connect cameras to host systems and can support FPGA processing. KAYA Instruments, Gidel, BitFlow, and Euresys offer programmable platforms that can support acquisition and preprocessing.
CLHS FPGA IP cores and development kits are projected to expand at a 13.27% CAGR between 2026 and 2031. A3's VHDL-93 IP core supports CLHS development on Altera, Xilinx, and Microsemi FPGA platforms and can reduce dependency on proprietary chipsets. The Camera Link HS Interface Components Industry also includes cables, optical assemblies, interface boards, mezzanine cards, signal converters, range extenders, simulators, and test equipment. Signal converters and range extenders are relevant in aerospace and scientific systems where cable runs exceed 300 meters. Camera simulators allow engineers to test acquisition pipelines using controlled data patterns before procuring cameras. This can reduce validation risk in systems that integrate multiple hardware and software suppliers. The broader component set gives users options to build systems around a common CLHS interface.
M Protocol held 62.53% of protocol revenue in 2025. Its installed base was built around designs that operated at 3.125-5 Gbps over copper CX4 runs up to 15 meters. Its 8b/10b encoding can be simpler to implement in cost-sensitive FPGA designs. Many inspection equipment suppliers adopted the M Protocol when 10 Gbps fiber deployments were more expensive. This installed base continues to support demand for M Protocol in replacement and upgrade programs. It also gives equipment owners a familiar interface for modest-distance applications.
X Protocol is projected to expand at a 13.83% CAGR from 2026 to 2031. The A3 CLHS v1.2 specification supports migration from 10 Gbps to 25 Gbps with the same IP core and commercial SFP28, QSFP28, and MPO optical modules. It's 64b/66b encoding and forward error correction suit long fiber links in scientific instruments, large factory layouts, and aerospace imaging. A3 has also described a path toward 50 Gbps per lane using the same core with a bridge to a 128-bit SerDes input. This may help suppliers improve capacity without a full interface redesign. The protocol's suitability for deterministic fiber links supports its role in the Camera Link HS Interface Components Market.
Complete Report Scope:
- By Component Type
- CLHS Cameras
- CLHS Frame Grabbers
- CLHS Interface Boards and Mezzanine Cards
- CLHS Cables and Optical Assemblies
- CLHS Signal Converters and Range Extenders
- CLHS FPGA IP Cores and Development Kits
- CLHS Camera Simulators and Test Equipment
- By Protocol
- M Protocol
- X Protocol
- By Channel Count
- Single-Channel
- Dual-Channel
- Multi-Channel
- By End-User Industry
- Industrial Automation and Machine Builders
- Electronics and Semiconductor Manufacturers
- Automotive Manufacturers and Tier Suppliers
- Medical Device and Life Sciences Organizations
- Aerospace and Defense Organizations
- Research Institutes and Universities
- System Integrators and Contract Inspection Providers
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of the Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific accounted for 39.81% of revenue in 2026, the largest regional share in the Camera Link HS Interface Components Market. The region is projected to expand at a 12.47% CAGR through 2031, the fastest rate among regions. Its position reflects the locations of major semiconductor and electronics production centers in China, South Korea, Taiwan, and Japan. New fabrication capacity and advanced packaging investment support demand for inspection systems. Teledyne Vision Solutions presented CLHS-equipped imaging products at Vision China in Shanghai in March 2026. The presentation addressed applications including wafer metrology, display inspection, and factory automation.
North America and Europe accounted for much of the remaining revenue in the Camera Link HS Interface Components Market due to their scientific imaging, aerospace, defense, and specialized integration activities. North American procurement includes BitFlow's Axion-CL frame grabber selection by NASA's Goddard Space Flight Center for ground-based radiation testing of an InGaAs shortwave infrared camera. Europe has a concentrated machine vision ecosystem that includes Silicon Software, Euresys, and equipment suppliers in Germany. EMVA co-ratified the CLHS standard, which supports its use among European inspection equipment developers. Gidel presented its FantoVision FPGA platform during the aerospace and defense innovation tour at VISION 2026 in Stuttgart.
South America has early adoption of CLHS in Brazil's automotive supplier base and in Argentine electronics assembly operations. The Middle East and Africa are emerging procurement areas in the Camera Link HS Interface Components Market, with defense demand in Saudi Arabia and the UAE for airborne surveillance and long-range reconnaissance systems. These systems can require fiber links exceeding 300 meters. The market faces a shortage of qualified integrators in these regions. Local system builders may need external support for commissioning and validation. A3's VHDL IP core and product registration program give developers a route to build CLHS products without proprietary protocol dependencies. This can gradually improve local implementation capability.
- Teledyne Digital Imaging, Inc.
- Matrox Electronic Systems Ltd.
- BitFlow, Inc.
- Euresys SA
- Active Silicon Limited
- KAYA Instruments Ltd.
- Gidel Ltd.
- Basler AG
- Imperx, Inc.
- Pleora Technologies Inc.
- Adimec Advanced Image Systems B.V.
- Silicon Software GmbH
- Photonfocus AG
- Vieworks Co., Ltd.
- JAI A/S
- Allied Vision Technologies GmbH
- EPIX, Inc.
- Hefei I-TEK Opto-Electronics Co., Ltd.
- Beijing JoinHope Image Technology Co., Ltd.
- Beijing Daheng Image Vision Co., Ltd.
- NED Image Technology Co., Ltd.
- IO Industries Inc.
- Optronis GmbH
- Mikrotron GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for High-Resolution, High-Frame-Rate Machine Vision
- 4.2.2 Expansion of Semiconductor and Electronics Inspection
- 4.2.3 Growth of AI-Enabled Industrial Automation and Edge Processing
- 4.2.4 Increasing Adoption of Deterministic, Low-Latency Imaging Links
- 4.2.5 Radiation-Hard and Long-Reach Imaging Requirements in Aerospace and Defense
- 4.2.6 Reusable Open CLHS IP Cores Lowering Design-In Barriers
- 4.3 Market Restraints
- 4.3.1 Migration to CoaXPress and High-Speed Ethernet Alternatives
- 4.3.2 High System Integration and Validation Costs
- 4.3.3 Limited Availability of Native CLHS Cameras and Qualified Integrators
- 4.3.4 Interface Chipset Obsolescence and Specialized Firmware Dependency
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component Type
- 5.1.1 CLHS Cameras
- 5.1.2 CLHS Frame Grabbers
- 5.1.3 CLHS Interface Boards and Mezzanine Cards
- 5.1.4 CLHS Cables and Optical Assemblies
- 5.1.5 CLHS Signal Converters and Range Extenders
- 5.1.6 CLHS FPGA IP Cores and Development Kits
- 5.1.7 CLHS Camera Simulators and Test Equipment
- 5.2 By Protocol
- 5.2.1 M Protocol
- 5.2.2 X Protocol
- 5.3 By Channel Count
- 5.3.1 Single-Channel
- 5.3.2 Dual-Channel
- 5.3.3 Multi-Channel
- 5.4 By End-User Industry
- 5.4.1 Industrial Automation and Machine Builders
- 5.4.2 Electronics and Semiconductor Manufacturers
- 5.4.3 Automotive Manufacturers and Tier Suppliers
- 5.4.4 Medical Device and Life Sciences Organizations
- 5.4.5 Aerospace and Defense Organizations
- 5.4.6 Research Institutes and Universities
- 5.4.7 System Integrators and Contract Inspection Providers
- 5.4.8 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of the Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market RankandShare, Products and Services, Recent Developments)
- 6.4.1 Teledyne Digital Imaging, Inc.
- 6.4.2 Matrox Electronic Systems Ltd.
- 6.4.3 BitFlow, Inc.
- 6.4.4 Euresys SA
- 6.4.5 Active Silicon Limited
- 6.4.6 KAYA Instruments Ltd.
- 6.4.7 Gidel Ltd.
- 6.4.8 Basler AG
- 6.4.9 Imperx, Inc.
- 6.4.10 Pleora Technologies Inc.
- 6.4.11 Adimec Advanced Image Systems B.V.
- 6.4.12 Silicon Software GmbH
- 6.4.13 Photonfocus AG
- 6.4.14 Vieworks Co., Ltd.
- 6.4.15 JAI A/S
- 6.4.16 Allied Vision Technologies GmbH
- 6.4.17 EPIX, Inc.
- 6.4.18 Hefei I-TEK Opto-Electronics Co., Ltd.
- 6.4.19 Beijing JoinHope Image Technology Co., Ltd.
- 6.4.20 Beijing Daheng Image Vision Co., Ltd.
- 6.4.21 NED Image Technology Co., Ltd.
- 6.4.22 IO Industries Inc.
- 6.4.23 Optronis GmbH
- 6.4.24 Mikrotron GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 視覺檢測設備市場:全球市場預測,2026-2032年
 2034年機器視覺半導體市場預測-全球半導體元件、感測器類型、半導體技術、應用、最終用戶和區域分析機器視覺和機器人市場預測至2034年——全球視覺技術、視覺能力、機器人類型、引導方法、最終用戶和地區分析
 橡膠分析設備市場規模、佔有率和成長分析:按儀器類型、測試類型、應用、最終用戶、操作方法和地區分類 - 產業預測,2026-2033 年
 固定式工業掃描
 機器視覺系統租賃:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)機器視覺軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)緊湊型機器視覺系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 全球機器視覺市場:機會與策略展望(至2035年)歐洲機器視覺系統:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)