


 |
市場調查報告書
商品編碼
2155010
緊湊型機器視覺系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Compact Machine Vision Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
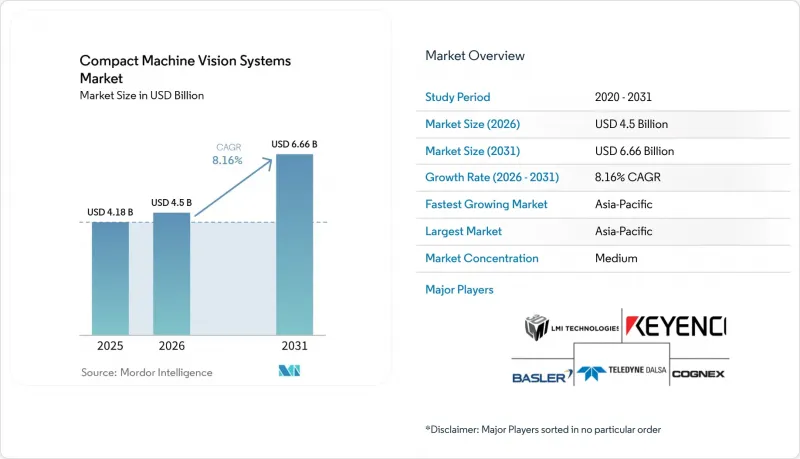
根據 Mordor Intelligence 預測,緊湊型機器視覺系統市場規模將從 2025 年的 41.8 億美元和 2026 年的 45 億美元成長到 2031 年的 66.6 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 8.16%。
全球緊湊型機器視覺系統市場趨勢與洞察
擴大工廠自動化規模並引進工業4.0
緊湊型機器視覺系統市場正受惠於工廠投資將檢測流程更靠近生產設備。 2026年1月,中國發布了由八個部會聯合製定的「人工智慧+製造」指南,呼籲在整條生產線上採用機器視覺和無人智慧檢測技術。該指南的目標是到2027年實現1000家人工智慧旗艦企業和500個標竿製造項目。這項政策方向將視覺設備融入更廣泛的工業現代化計畫,並支持超越短期生產週期的需求。 2026年的一項系統性研究表明,利用深度學習的機器視覺將成為工業4.0品管工作流程的核心。該研究還發現,基於變壓器的方法可以在保持生產速度的同時,更好地處理複雜形狀的缺陷,從而進一步推動人工智慧賦能的緊湊型平台的應用。
對「零缺陷」和可追溯性的需求日益成長。
隨著品管成為供應商和合規性的必要條件,緊湊型機器視覺系統市場正蓬勃發展。汽車和醫療設備供應商越來越需要將偵測影像、缺陷座標和生產條件與序號零件關聯起來的記錄。 2026 年的一項調查重點介紹了一種適用於多 SKU 灌裝生產線的緊湊型單攝影機自動化光學檢測站。該系統整合了缺陷檢測、尺寸測量和條碼驗證功能,同時保持了生產速度。它還能產生符合良好生產規範 (GMP) 要求的「品質 4.0」可追溯性記錄。這些功能使得緊湊型系統能夠有效地應用於需要在同一生產單元內完成檢測、記錄和利用有限占地面積的製造商。
整合與校對的複雜性
整合和校準仍然是緊湊型系統廣泛應用的主要障礙。製造商必須管理相機、鏡頭、照明和軟體配置的初始部署和持續維護。有證據表明,在 32 度C的環境溫度下,鏡頭座的熱位移會導致位置誤差在 4 小時後超過 ±0.012 毫米。此外,有些視覺感測器在連續生產負載下每運作7-15 小時就需要重新校準。如果 NPU 編譯器與特定作業系統緊密綁定,則軟體更新可能會很困難。因此,緊湊型機器視覺系統市場更傾向於選擇那些擁有完善的連接文件、適用於製造執行系統 (MES) 的原生插件以及清晰支援體系的供應商。
細分市場分析
到2025年,智慧相機將佔據輕巧機器視覺系統市場38.89%的佔有率。這一佔有率得益於光學元件、影像感測器、處理功能和通訊介面在單一裝置中的整合。這種架構在許多日常應用中無需單獨的運算設備。智慧相機廣泛應用於穩定生產線中的缺陷檢測和條碼讀取。其部署基礎也得益於與現有工業軟體環境的兼容性。視覺感測器價格更低,能夠處理簡單的合格/不合格判斷任務。視覺控制器則支援對人工智慧吞吐量、模組化相機或靈活照明配置要求更高的應用。為了滿足這些需求,康耐視推出了採用NVIDIA Jetson技術、處理能力高達157 TOPS、並支援模組化相機和照明的「In-Sight 6900」控制器。
預計到2031年,嵌入式視覺系統將以9.19%的複合年成長率成長。這一發展與人工智慧推理向應用特定模組的轉變密切相關,這些模組可以安裝在整合到機器人單元和輸送機設備中的位置。緊湊型機器視覺系統市場規模的成長主要受空間有限且需要本地處理的生產環境所驅動。 2026年7月,三菱電機和SONY半導體解決方案公司宣布成立「先進視覺解決方案」公司,該公司將直接在影像感測器上進行人工智慧分析。這項計畫中的合資企業將結合SONY的影像感測器和邊緣人工智慧技術以及三菱電機在工廠自動化方面的專業知識。感測器端處理減少了感測器和處理器之間的通訊。此外,IEC 62061的安全需求正在影響嵌入式系統的設計,因為確定性容錯在機械應用中至關重要。線掃描相機和3D飛行時間(ToF)相機在卷材偵測和揀選等領域仍發揮特殊作用。
預計到2025年,2D視覺系統將佔銷售額的69.19%,成為緊湊型機器視覺系統市場的核心影像格式。其技術成熟、成本低廉且被整合商廣泛接受,使其在表面檢測、程式碼讀取和尺寸測量等領域中廣泛應用。邊緣學習軟體正在擴展2D系統可處理的外觀和紋理變化識別任務範圍。為了滿足這些偵測需求,康耐視已將ViDi邊緣學習功能整合到其In-Sight 3900系統中。3D系統應用於汽車車身本體組裝、機器人揀選和電子元件安裝等對深度資訊要求極高的領域。隨著元件成本的下降,結構光和飛行時間(ToF)系統為這些操作提供了支援。在生產任務中,如果2D成像無法提供空間訊息,3D系統將繼續發揮至關重要的作用。
預計到2031年,頻譜和高光譜影像系統將以10.12%的複合年成長率成長。這些系統的優點在於它們不僅能夠辨識表面外觀,還能辨識材料特性。 Specim公司推出的SpecimONE系統是一款用於工業分類和品管的線上高光譜遙測平台。其線掃描方法能夠以適合輸送機運行的速度捕捉多個頻譜波段。這使得食品、製藥和回收過程中化學物質的即時識別成為可能。 2025年的科學研究表明,將高光譜影像與化學計量學相結合,可以作為一種過程分析技術(PAT)工具,用於線上藥物監測。這種監測方式符合FDA在相關資料中概述的過程分析技術指南。因此,緊湊型機器視覺系統市場能夠為需要材料級資訊的檢測作業提供支援。
區域分析
預計到2025年,亞太地區將佔據緊湊型機器視覺系統市場39.87%的佔有率,並將以8.65%的複合年成長率持續成長至2031年。中國家用電子電器、新能源汽車和半導體生產的集中度是推動該地區需求的主要因素。 2026年1月發布的「AI+製造」政策指南呼籲在生產線上引入機器視覺和無人智慧檢測技術。日本和韓國在高階電子和汽車應用領域仍佔有重要地位。 2026年7月發布的「先進視覺解決方案」指南強調了日本對用於製造自動化的感測器端AI視覺技術的興趣。
在北美和歐洲,受監管生產場所對嵌入式人工智慧系統和偵測平台的需求正在推動市場發展。在北美,製造業回流導致檢測需求增加,而熟練勞動力供應依然緊張。德國擁有汽車、機械和醫療設備製造業基地,是歐洲採用此技術的先驅。歐盟機械法規正在影響用於安全關鍵型機械的視覺系統的選擇。 Basler 的超緊湊型 25x30 毫米視覺感測器反映了歐洲機械製造商對易於整合組件的需求。隨著設備供應商將這些組件整合到其原始機器設計中,緊湊型機器視覺系統市場正在受益。
南美洲、中東和非洲仍處於應用初期。在巴西和阿根廷,食品、飲料和包裝生產行業的需求正在成長,自動化檢測在這些行業中日益受到關注。沙烏地阿拉伯和阿拉伯聯合大公國(阿拉伯聯合大公國)正在建立工業和製藥生產能力,包括自動化檢測基礎設施,作為其「2030願景」計畫的一部分。南非在汽車組裝行業的應用方面處於該地區領先地位,國際OEM工廠正在實施視覺引導的品管系統。在這些全部區域,高昂的系統成本仍然是一個主要障礙。隨著硬體成本的下降和本地系統整合能力的提升,緊湊型機器視覺系統市場有望進一步擴大其市場佔有率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大工廠自動化規模並引進工業4.0
- 對「零缺陷」和「可追溯性」的需求日益成長
- 檢驗和品管崗位人手不足
- 嵌入式人工智慧推理可實現低延遲測試。
- 減少多產品生產線中設備的安裝面積
- 透過邊緣處理降低視覺資料的頻寬
- 市場限制因素
- 整合和校準的複雜性
- 高性能緊湊型系統的初始成本
- 機器視覺整合商和人工智慧專家短缺
- 小型機殼的熱學和光學限制
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 視覺感測器
- 智慧型相機
- 嵌入式視覺系統
- 視覺控制器
- 其他產品類型
- 按成像類型
- 2D視覺系統
- 3D視覺系統
- 頻譜和高光譜影像系統
- 透過使用
- 檢測和缺陷檢測
- 測量與計量
- 識別和代碼讀取
- 引導和定位
- 其他用途
- 按最終用戶行業分類
- 車
- 電子和半導體
- 食品/飲料
- 醫療和藥品
- 物流與零售
- 包裝
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- ASEAN
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cognex Corporation
- KEYENCE CORPORATION
- Basler AG
- Teledyne DALSA, Inc.
- Omron Corporation
- Allied Vision Technologies GmbH
- LMI Technologies Inc.
- IDS Imaging Development Systems GmbH
- HIKROBOT
- Vision Components GmbH
- VITRONIC Dr.-Ing. Stein Bildverarbeitungssysteme GmbH
- Euresys SA
- JAI A/S
- SVS-Vistek GmbH
- Chromasens GmbH
- SICK AG
- Baumer Holding AG
- Datalogic SpA
- LUCID Vision Labs Inc.
- Emergent Vision Technologies Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the compact machine vision systems market size is projected to expand from USD 4.18 billion in 2025 and USD 4.50 billion in 2026 to USD 6.66 billion by 2031, registering a CAGR of 8.16% between 2026 and 2031.
Global Compact Machine Vision Systems Market Trends and Insights
Expanding Factory Automation and Industry 4.0 Adoption
The compact machine vision systems market benefits from factory investments that place inspection closer to production equipment. China issued an eight-ministry AI plus Manufacturing directive in January 2026 that called for machine vision and unmanned intelligent inspection across production lines. The directive also targeted 1,000 flagship AI enterprises and 500 benchmark manufacturing deployments by 2027. This policy direction embeds vision equipment in wider industrial modernization plans and supports demand beyond short-term production cycles. A 2026 systematic review identified deep-learning machine vision as a central part of Industry 4.0 quality-control workflows. The review also found that transformer-based approaches can improve the handling of complex defect shapes at production speed, supporting adoption of AI-capable compact platforms.
Rising Zero-Defect and Traceability Requirements
The compact machine vision systems market gains support as quality control becomes a supplier and compliance requirement. Automotive and medical-device suppliers increasingly need records that link inspection images, defect coordinates, and production conditions to serialized parts. A 2026 study described a compact single-camera automated optical inspection station for mixed-SKU bottling lines. The system combined defect detection, dimensional measurement, and barcode confirmation at production speed. It also generated Quality 4.0 traceability records suited to good manufacturing practice requirements. These capabilities make compact installations relevant where manufacturers need inspection, documentation, and limited floor-space use in the same production cell.
Integration and Calibration Complexity
Integration and calibration remain material barriers to broader deployment of compact systems. Manufacturers must manage the initial installation and the continuing maintenance of camera, lens, lighting, and software settings. The supplied evidence notes that temperature-related lens-mount movement can create positional errors above +-0.012 mm after 4 hours at 32°C ambient conditions. It also notes that some vision sensors need recalibration every 7-15 operating hours under continuous production load. Software updates can add difficulty when NPU compilers are tied closely to particular operating systems. The compact machine vision systems market consequently favors suppliers that offer documented connectivity, native manufacturing-execution-system plugins, and defined support arrangements.
Other drivers and restraints analyzed in the detailed report include:
- Labor Shortages in Inspection and Quality Roles
- Embedded AI Inference Enabling Low-Latency Inspection
- Upfront Cost for High-Performance Compact Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Smart cameras held 38.89% of the compact machine vision systems market share in 2025. Their position reflects the combination of optics, an image sensor, processing, and communication interfaces in one device. This structure removes the need for separate computing equipment in many routine applications. Smart cameras are widely used for defect detection and code reading on stable production lines. Their installed base is also supported by compatibility with established industrial software environments. Vision sensors serve simpler pass-fail tasks at lower price points. Vision controllers support more demanding applications that require high AI throughput, modular cameras, or flexible lighting arrangements. Cognex positioned its In-Sight 6900 controller for this need with NVIDIA Jetson technology, up to 157 TOPS, and modular camera and lighting support.
Embedded vision systems are projected to expand at a 9.19% CAGR through 2031. Their development is linked to AI inference moving onto application-specific modules that can be placed in robotic cells and conveyor-integrated positions. The compact machine vision systems market size for this category is supported by production settings where space is restricted and local processing is needed. Mitsubishi Electric and Sony Semiconductor Solutions announced Advanced Vision Solutions in July 2026 to develop AI analysis directly on the image sensor. The planned venture combines Sony image-sensor and edge-AI capabilities with Mitsubishi Electric factory-automation expertise. On-sensor processing can reduce communication between the sensor and processor. IEC 62061 safety requirements also influence embedded system design because deterministic fault responses are important in machinery applications. Line-scan cameras and 3D time-of-flight cameras retain specialized roles in web inspection and bin-picking.
2D vision systems held 69.19% of revenue in 2025, making them the core imaging format for the compact machine vision systems market. Their technical maturity, lower cost, and broad integrator familiarity support use in surface inspection, code reading, and dimensional gauging. Edge-learning software is expanding the range of variable-appearance and texture-discrimination tasks that 2D systems can address. Cognex included ViDi Edge Learning capabilities in the In-Sight 3900 for these types of inspection needs. 3D systems serve automotive body-in-white assembly, robotic bin-picking, and electronics placement where depth information is important. Structured-light and time-of-flight systems support this work as component costs fall. The category remains relevant where a production task needs spatial information that a 2D image cannot provide.
Multispectral and hyperspectral imaging systems are projected to expand at a 10.12% CAGR through 2031. Their role is based on the ability to identify material characteristics rather than surface appearance alone. Specim described its SpecimONE system as an inline hyperspectral platform for industrial sorting and quality control. Its line-scan approach captures many spectral bands at speeds suited to conveyor operations. This allows real-time chemical identification in food, pharmaceutical, and recycling operations. A 2025 scientific study found that hyperspectral imaging combined with chemometrics can serve as a process analytical technology tool for online pharmaceutical monitoring. Such monitoring aligns with the FDA's process analytical technology guidance described in the supplied material. The compact machine vision systems market can therefore support inspection tasks that require material-level information.
Complete Report Scope:
- By Product Type
- Vision Sensors
- Smart Cameras
- Embedded Vision Systems
- Vision Controllers
- Other Product Types
- By Imaging Type
- 2D Vision Systems
- 3D Vision Systems
- Multispectral and Hyperspectral Imaging Systems
- By Application
- Inspection and Defect Detection
- Measurement and Metrology
- Identification and Code Reading
- Guidance and Positioning
- Other Applications
- By End-User Industry
- Automotive
- Electronics and Semiconductors
- Food and Beverage
- Healthcare and Pharmaceuticals
- Logistics and Retail
- Packaging
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of the Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 39.87% of the compact machine vision systems market share in 2025 and is projected to expand at an 8.65% CAGR through 2031. China's concentration of consumer electronics, new-energy vehicles, and semiconductor production supports regional demand. The January 2026 AI plus Manufacturing policy direction called for machine vision and unmanned intelligent inspection in production lines. Japan and South Korea remain important for high-specification electronics and automotive applications. The July 2026 announcement of Advanced Vision Solutions highlighted Japanese interest in on-sensor AI vision for manufacturing automation.
North America and Europe support demand for embedded AI systems and inspection platforms used in regulated production. In North America, reshoring can increase inspection requirements while the supply of skilled labor remains constrained. Germany is a leading European adopter because of its automotive, machinery, and medical-device manufacturing base. The EU Machinery Regulation influences choices for vision systems used in safety-critical machinery roles. Basler's ultra-compact 25 X 30 mm vision sensor reflects the need among European machine builders for components that are ready to integrate. The compact machine vision systems market benefits when equipment suppliers place these components inside original machine designs.
South America, the Middle East, and Africa remain earlier-stage adoption areas. Brazil and Argentina support demand through food, beverage, and packaging production where inspection automation is gaining attention. Saudi Arabia and the UAE are building industrial and pharmaceutical capacity under Vision 2030 programs that include automation-ready inspection infrastructure. South Africa leads regional use in automotive assembly, where international OEM plants use vision-guided quality systems. High system cost remains a key barrier across these regions. The compact machine vision systems market can broaden its presence as hardware costs decline and local system-integration capabilities develop.
- Cognex Corporation
- KEYENCE CORPORATION
- Basler AG
- Teledyne DALSA, Inc.
- Omron Corporation
- Allied Vision Technologies GmbH
- LMI Technologies Inc.
- IDS Imaging Development Systems GmbH
- HIKROBOT
- Vision Components GmbH
- VITRONIC Dr.-Ing. Stein Bildverarbeitungssysteme GmbH
- Euresys S.A.
- JAI A/S
- SVS-Vistek GmbH
- Chromasens GmbH
- SICK AG
- Baumer Holding AG
- Datalogic S.p.A.
- LUCID Vision Labs Inc.
- Emergent Vision Technologies Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding Factory Automation and Industry 4.0 Adoption
- 4.2.2 Rising Zero-Defect and Traceability Requirements
- 4.2.3 Labor Shortages in Inspection and Quality Roles
- 4.2.4 Embedded AI Inference Enabling Low-Latency Inspection
- 4.2.5 Shrinking Equipment Footprints in High-Mix Production Lines
- 4.2.6 Edge Processing Reducing Vision-Data Bandwidth
- 4.3 Market Restraints
- 4.3.1 Integration and Calibration Complexity
- 4.3.2 Upfront Cost for High-Performance Compact Systems
- 4.3.3 Shortage of Machine Vision Integrators and AI Specialists
- 4.3.4 Thermal and Optical Constraints in Miniaturized Housings
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Vision Sensors
- 5.1.2 Smart Cameras
- 5.1.3 Embedded Vision Systems
- 5.1.4 Vision Controllers
- 5.1.5 Other Product Types
- 5.2 By Imaging Type
- 5.2.1 2D Vision Systems
- 5.2.2 3D Vision Systems
- 5.2.3 Multispectral and Hyperspectral Imaging Systems
- 5.3 By Application
- 5.3.1 Inspection and Defect Detection
- 5.3.2 Measurement and Metrology
- 5.3.3 Identification and Code Reading
- 5.3.4 Guidance and Positioning
- 5.3.5 Other Applications
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Electronics and Semiconductors
- 5.4.3 Food and Beverage
- 5.4.4 Healthcare and Pharmaceuticals
- 5.4.5 Logistics and Retail
- 5.4.6 Packaging
- 5.4.7 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of the Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cognex Corporation
- 6.4.2 KEYENCE CORPORATION
- 6.4.3 Basler AG
- 6.4.4 Teledyne DALSA, Inc.
- 6.4.5 Omron Corporation
- 6.4.6 Allied Vision Technologies GmbH
- 6.4.7 LMI Technologies Inc.
- 6.4.8 IDS Imaging Development Systems GmbH
- 6.4.9 HIKROBOT
- 6.4.10 Vision Components GmbH
- 6.4.11 VITRONIC Dr.-Ing. Stein Bildverarbeitungssysteme GmbH
- 6.4.12 Euresys S.A.
- 6.4.13 JAI A/S
- 6.4.14 SVS-Vistek GmbH
- 6.4.15 Chromasens GmbH
- 6.4.16 SICK AG
- 6.4.17 Baumer Holding AG
- 6.4.18 Datalogic S.p.A.
- 6.4.19 LUCID Vision Labs Inc.
- 6.4.20 Emergent Vision Technologies Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2034年機器視覺半導體市場預測-全球半導體元件、感測器類型、半導體技術、應用、最終用戶和區域分析機器視覺和機器人市場預測至2034年——全球視覺技術、視覺能力、機器人類型、引導方法、最終用戶和地區分析
 橡膠分析設備市場規模、佔有率和成長分析:按儀器類型、測試類型、應用、最終用戶、操作方法和地區分類 - 產業預測,2026-2033 年
 固定式工業掃描
 機器視覺系統租賃:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)機器視覺軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 全球機器視覺市場:機會與策略展望(至2035年)歐洲機器視覺系統:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 機器視覺市場-2026-2032年全球市場預測
 機器視覺市場報告:按產品、組件、應用、產業和地區分類(2026-2034 年)