


 |
市場調查報告書
商品編碼
2154903
南美洲個人護理包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)South America Personal Care Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
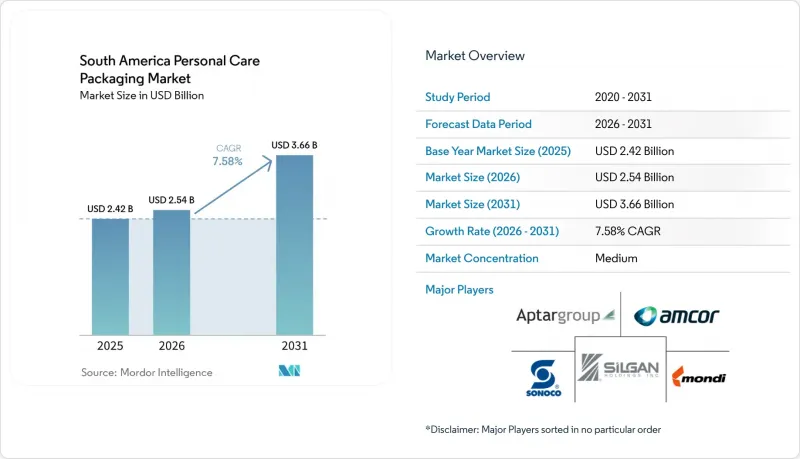
據 Mordor Intelligence 稱,2025 年南美個人護理包裝市場價值為 25.4 億美元,預計到 2031 年將從 2026 年的 25.4 億美元成長至 36.6 億美元,預測期(2026-2031 年)的複合年成長率為 7.58%。
南美個人護理包裝市場趨勢與洞察。
個人保健產品和高階美容產品的消費量增加
即使在零售環境低迷的情況下,巴西的直銷網路仍能推動重複購買,並維持對瓶裝、罐裝、管裝和袋裝產品的需求。隨著產品數量的增加,對各種尺寸的容器、瓶蓋、標籤和分配器的需求也隨之增加。高級產品通常採用真空瓶、玻璃瓶和裝飾性瓶蓋,這些都需要更專業的加工能力。由於個人化諮詢和重複訂單能夠提供比僅依賴貨架陳列的分銷管道更穩定的需求基礎,南美個人護理包裝市場正在發展出一個不局限於傳統商店的廣泛需求群體。
護膚、護髮和香水產業成長
精華液、視網醇產品和頻譜防曬油均採用無氣泵、防紫外線玻璃瓶或密封管來保護其成分。 AptarGroup 在卡哈馬爾、容迪亞伊、馬林加和卡馬卡利設有製造地,為區域美容行業的客戶提供無氣分裝系統。包括 Wheaton Brasil 供應的產品在內的香水需求,推動了高檔玻璃瓶和可重複填充設計的銷售。人們對防曬油的日益關注也促進了計量管和無氣泵的需求,這些產品在精確分裝和保護產品方面發揮著至關重要的作用。南美個人護理包裝市場日益成長的技術要求源於本地化生產這些系統的需求,這可以減少對進口的依賴,並使品牌能夠滿足更短的上市週期。
聚烯和再生樹脂的成本波動
由於聚乙烯和聚丙烯廣泛應用於瓶子、軟管、瓶蓋和軟包裝薄膜,原料成本對當地加工商至關重要。如果包裝供應商無法立即將價格上漲轉嫁給品牌所有者,樹脂成本上漲就會擠壓利潤空間。成本的不確定性也使長期供應合約和新產品開發專案的定價變得複雜。雖然再生樹脂可以在原生樹脂供應緊張時作為替代來源,但其品質和供應仍然不穩定。由於樹脂原料在大量生產的塑膠包裝成本中佔很大比例,南美洲個人護理包裝市場仍面臨風險。
細分市場分析
2025年,塑膠佔南美洲個人護理包裝市場58.23%的佔有率。這是因為聚乙烯和聚丙烯在大量生產的產品中實現了成本績效的平衡。預計到2031年,塑膠市場將以8.16%的複合年成長率成長,是所有材料子類別中成長率最高的。這一轉變反映了市場對在現有塑膠加工系統中採用可再生和回收材料的產品的需求日益成長。 Braschem公司的生物基聚乙烯「I'm Green」採用巴西甘蔗提取的乙醇製成,為加工商提供了當地可再生原料。 Natura和Grupo Boticario已在其包裝中採用可再生塑膠,促進了經認證的生物基材料的應用,並使加工商能夠在不影響產品性能的前提下改造現有生產線。
玻璃在香水和高階護膚品領域繼續扮演著至關重要的角色,它不僅提供保護,還能減輕重量,並賦予產品高階質感。 Wheaton Brazil 為國內外美妝品牌供應玻璃包裝,並正在以生物甲烷取代生產過程中部分天然氣。金屬在氣霧劑和除臭劑等對耐用性和易用性要求極高的應用中仍然發揮著重要作用。 Grupo Boticario 報告稱,到 2024 年,其回收鋁製氣霧罐容器將減少超過 240 噸的碳排放和超過 100 噸的鋁廢棄物。紙張和紙板在二次包裝和某些特殊應用中越來越受到關注,但由於每種材料的阻隔性、裝飾效果和使用後處理方式各不相同,因此材料的選擇仍然因應用而異。
預計到2025年,硬質包裝將佔南美個人護理包裝市場規模的71.48%,反映出瓶罐在護髮、口腔護理、香水和護膚領域的重要性依然不減。硬質包裝仍然至關重要,因為消費者將其與產品保護、內容物可見性和高階體驗聯繫起來。 2026年3月,安姆科推出了可客製化的「摩卡」瓶,容量分別為100毫升、250毫升和500毫升,最低訂購量為1萬個。這項規格使得即使是小規模的品牌也能縮短開發時間,並利用標準化的瓶身平台。此外,硬質包裝還能實現一些軟性包裝難以實現的裝飾和分配方式。
預計到2031年,軟包裝市場將以8.32%的複合年成長率成長,因為補充裝和小袋能夠滿足各種不同的購買場景。經濟型小袋可以降低初始購買成本,而高檔補充裝則有助於在消費者購買初始包裝後留住他們。安姆科為南美地區的個人保健產品提供補充裝,其中包括旨在提高可回收性的設計。這些包裝形式正逐漸成為互補而非直接替代品。硬質初始包裝可以提升產品展示效果,而填充用裝則可以減少重複購買時的材料消耗。這為能夠持續滿足兩種包裝形式在阻隔性、裝飾性和顏色方面的要求的供應商在南美個人護理包裝市場創造了新的商機。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 個人保健產品和高階美容產品的消費量增加
- 擴展可填充和可重複使用的包裝模式
- 對輕便、靈活包裝的需求
- 護膚、護髮產品和香水品類均達到成長。
- 品牌主導採用包含單一材料和再生材料的包裝。
- 近岸客製化服務可縮短美容產品上市時間
- 市場限制因素
- 聚烯和再生樹脂的成本波動
- 開發新型永續包裝高成本。
- 廢舊包裝材料的收集和處理不統一
- 由於產品安全和零售營運限制,補充裝系統存在摩擦。
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 材料類型
- 塑膠
- 聚乙烯
- 聚丙烯
- PET和PVC
- 聚苯乙烯
- 生物基塑膠
- 其他類型的塑膠
- 玻璃
- 金屬
- 紙張和紙板
- 塑膠
- 按包裝類型
- 死板的
- 靈活的
- 依產品類型
- 瓶子和罐子
- 管子和棍子
- 泵浦和分配器
- 小袋和小袋
- 蓋子和封口
- 其他產品類型
- 透過使用
- 護膚
- 護髮
- 口腔護理
- 化妝品
- 除臭劑和香水
- 嬰兒護理
- 其他用途
- 按地區
- 巴西
- 阿根廷
- 智利
- 哥倫比亞
- 其他南美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Mondi plc
- AptarGroup, Inc.
- Sonoco Products Company
- Silgan Holdings Inc.
- Albea Services SAS
- Gerresheimer AG
- Quadpack Industries, SA
- HCP Packaging(Shanghai)Co., Ltd.
- Cosmogen SA
- Texen SAS
- Tubaplas SA
- Wheaton Brasil Vidros SA
- Proenfar SAS
- C-Pack Packaging do Brasil Ltda.
- Globalpack Embalagens Ltda.
- Condensa SA
- Brasilata SA Embalagens Metalicas
- FCO Group Participacoes Ltda.
- Liner Brasil Ltda.
第7章 市場機會與未來展望
According to Mordor Intelligence, the South America personal care packaging market size was valued at USD 2.54 billion in 2025 and estimated to grow from USD 2.54 billion in 2026 to reach USD 3.66 billion by 2031, at a CAGR of 7.58% during the forecast period (2026-2031).
South America Personal Care Packaging Market Trends and Insights
Rising Consumption of Personal Care Products and Premium Beauty Products
Brazil's direct-selling networks support repeat purchases and maintain demand for bottles, jars, tubes, and sachets even when retail conditions weaken. More product stock-keeping units require a wider range of container sizes, closures, labels, and dispensing options. Premium products also use airless dispensers, glass flacons, and decorated closures that require more specialized conversion capabilities. Personal consultation and repeat ordering can provide a more stable demand base than channels that depend solely on shelf visibility, giving the South America personal care packaging market a broad demand base not limited to traditional stores.
Growth in Skin Care, Hair Care, and Fragrance
Serums, retinol products, and broad-spectrum sunscreens use airless pumps, UV-protective glass, or sealed tubes to protect their formulas. AptarGroup operates manufacturing sites in Cajamar, Jundiai, Maringa, and Camacari, serving regional beauty customers with airless dispensing systems. Fragrance demand supports sales of premium glass flacons and refillable designs, including products supplied by Wheaton Brasil. Greater sunscreen awareness also supports demand for metered tubes and airless pumps, which provide controlled dispensing and protect the product. Local production of these systems can reduce import dependence and help brands respond to shorter launch schedules, raising the technical requirements for the South America personal care packaging market.
Polyolefin and Recycled-Resin Cost Volatility
Polyethylene and polypropylene are widely used in bottles, tubes, caps, and flexible films, making input costs important for regional converters. Higher resin costs can compress margins when packaging suppliers cannot immediately pass price increases to brand owners. Cost uncertainty also complicates pricing for long-term supply contracts and new product development programs. Recycled material may provide an alternative source when virgin material availability tightens, although its quality and supply remain uneven. The South America personal care packaging market remains exposed because resin inputs account for a significant share of the cost of high-volume plastic packs.
Other drivers and restraints analyzed in the detailed report include:
- Brand Adoption of Mono-Material and Recycled-Content Packs
- Demand for Lightweight Flexible Packaging
- High Cost of Sustainable Packaging Development
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic accounted for 58.23% of the South America personal care packaging market in 2025 because polyethylene and polypropylene offer a practical cost-performance balance for high-volume products. Plastics are projected to grow at an 8.16% CAGR through 2031, the fastest rate among material subcategories. This change reflects higher demand for renewable and recycled-content options within established plastic conversion systems. Braskem's I'm Green bio-based polyethylene is produced from Brazilian sugarcane ethanol, giving converters access to a regional renewable feedstock. Natura and Grupo Boticario have used renewable plastic in packaging, supporting the wider adoption of certified bio-based materials and allowing converters to adapt existing production lines without sacrificing product performance.
Glass remains important for fragrance and prestige skin care because it supports product protection, weight, and premium presentation. Wheaton Brasil supplies glass packaging to domestic and multinational beauty brands and has adopted biometane as a partial replacement for natural gas in production. Metal continues to serve aerosol and deodorant applications, where durability and dispensing requirements are important. Grupo Boticario reported that its recycled aluminum aerosol packaging avoided more than 240 tonnes of carbon dioxide emissions and more than 100 tonnes of aluminum waste by 2024. Paper and paperboard are gaining attention for secondary cartons and selected specialty applications, although material selection remains application-specific because each option provides different barriers, decoration options, and end-of-life pathways.
Rigid packaging accounted for 71.48% of the South America personal care packaging market size in 2025, reflecting the continuing role of bottles and jars in hair care, oral care, fragrance, and skin care. Rigid packs remain important because consumers associate them with product protection, visibility, and a premium experience. Amcor introduced its customizable Mocha bottle in March 2026 in 100 ml, 250 ml, and 500 ml formats, with a minimum order quantity of 10,000 units. The format allows smaller brands to access a standardized bottle platform with a shorter development path. Rigid packs also support decoration and dispensing options that are difficult to reproduce in some flexible structures.
Flexible packaging is projected to grow at an 8.32% CAGR through 2031 as refill pouches and sachets serve different purchasing occasions. Value sachets lower the initial purchase cost, while premium refill pouches retain consumers after a primary pack is purchased. Amcor offers refill pouch structures for personal care products in South America, including designs intended to support recyclability. The formats are increasingly complementary rather than direct substitutes. A rigid primary container can support product presentation, while a refill pouch can reduce material for repeat purchases and create an opportunity in the South America personal care packaging market for suppliers that can meet consistent barrier, sealing, decoration, and color requirements across both formats.
Complete Report Scope:
- By Material Type
- Plastic
- Polyethylene
- Polypropylene
- PET and PVC
- Polystyrene
- Bio-Based Plastics
- Other Plastic Types
- Glass
- Metal
- Paper and Paperboard
- Plastic
- By Packaging Format
- Rigid
- Flexible
- By Product Type
- Bottles and Jars
- Tubes and Sticks
- Pumps and Dispensers
- Pouches and Sachets
- Caps and Closures
- Other Product Types
- By Application
- Skin Care
- Hair Care
- Oral Care
- Makeup Products
- Deodorants and Fragrances
- Baby Care
- Other Applications
- By Geography
- Brazil
- Argentina
- Chile
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- Amcor plc
- Mondi plc
- AptarGroup, Inc.
- Sonoco Products Company
- Silgan Holdings Inc.
- Albea Services S.A.S.
- Gerresheimer AG
- Quadpack Industries, S.A.
- HCP Packaging (Shanghai) Co., Ltd.
- Cosmogen S.A.
- Texen S.A.S.
- Tubaplas S.A.
- Wheaton Brasil Vidros S.A.
- Proenfar S.A.S.
- C-Pack Packaging do Brasil Ltda.
- Globalpack Embalagens Ltda.
- Condensa S.A.
- Brasilata S.A. Embalagens Metalicas
- FCO Group Participacoes Ltda.
- Liner Brasil Ltda.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Consumption of Personal Care Products and Premium Beauty SKUs
- 4.2.2 Expansion of Refillable and Reusable Packaging Models
- 4.2.3 Demand for Lightweight Flexible Packaging
- 4.2.4 Growth of Skin Care, Hair Care, and Fragrance Categories
- 4.2.5 Brand-Led Adoption of Mono-Material and Recycled-Content Packs
- 4.2.6 Nearshore Customization for Shorter Beauty Launch Cycles
- 4.3 Market Restraints
- 4.3.1 Volatility in Polyolefin and Recycled-Resin Costs
- 4.3.2 High Cost of New Sustainable Packaging Development
- 4.3.3 Inconsistent Collection and Recovery of Post-Consumer Packaging
- 4.3.4 Refill-System Friction from Product-Safety and Retail-Execution Constraints
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.1.1 Polyethylene
- 5.1.1.2 Polypropylene
- 5.1.1.3 PET and PVC
- 5.1.1.4 Polystyrene
- 5.1.1.5 Bio-Based Plastics
- 5.1.1.6 Other Plastic Types
- 5.1.2 Glass
- 5.1.3 Metal
- 5.1.4 Paper and Paperboard
- 5.1.1 Plastic
- 5.2 By Packaging Format
- 5.2.1 Rigid
- 5.2.2 Flexible
- 5.3 By Product Type
- 5.3.1 Bottles and Jars
- 5.3.2 Tubes and Sticks
- 5.3.3 Pumps and Dispensers
- 5.3.4 Pouches and Sachets
- 5.3.5 Caps and Closures
- 5.3.6 Other Product Types
- 5.4 By Application
- 5.4.1 Skin Care
- 5.4.2 Hair Care
- 5.4.3 Oral Care
- 5.4.4 Makeup Products
- 5.4.5 Deodorants and Fragrances
- 5.4.6 Baby Care
- 5.4.7 Other Applications
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Chile
- 5.5.4 Colombia
- 5.5.5 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi plc
- 6.4.3 AptarGroup, Inc.
- 6.4.4 Sonoco Products Company
- 6.4.5 Silgan Holdings Inc.
- 6.4.6 Albea Services S.A.S.
- 6.4.7 Gerresheimer AG
- 6.4.8 Quadpack Industries, S.A.
- 6.4.9 HCP Packaging (Shanghai) Co., Ltd.
- 6.4.10 Cosmogen S.A.
- 6.4.11 Texen S.A.S.
- 6.4.12 Tubaplas S.A.
- 6.4.13 Wheaton Brasil Vidros S.A.
- 6.4.14 Proenfar S.A.S.
- 6.4.15 C-Pack Packaging do Brasil Ltda.
- 6.4.16 Globalpack Embalagens Ltda.
- 6.4.17 Condensa S.A.
- 6.4.18 Brasilata S.A. Embalagens Metalicas
- 6.4.19 FCO Group Participacoes Ltda.
- 6.4.20 Liner Brasil Ltda.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 個人護理包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)美國個人保健產品包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)中國個人護理包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 全球個人護理包裝市場,2025-2032年
 個人護理包裝市場預測至2034年-按產品類型、包裝形式、材料和地區分類的全球分析個人護理包裝市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區分類,預測2026-2034年
 個人護理包裝市場分析及預測(至2035年):按類型、產品類型、材料類型、應用、技術、最終用戶、製程、組件和功能分類
 個人護理包裝市場規模、佔有率和成長分析(按材料、產品類型、應用、包裝類型和地區分類)-2026-2033年產業預測個人護理包裝市場-2026-2031年預測中東和非洲的個人護理包裝:市場佔有率分析、行業趨勢和成長預測(2025-2030)