


 |
市場調查報告書
商品編碼
2121312
中國個人護理包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)China Personal Care Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
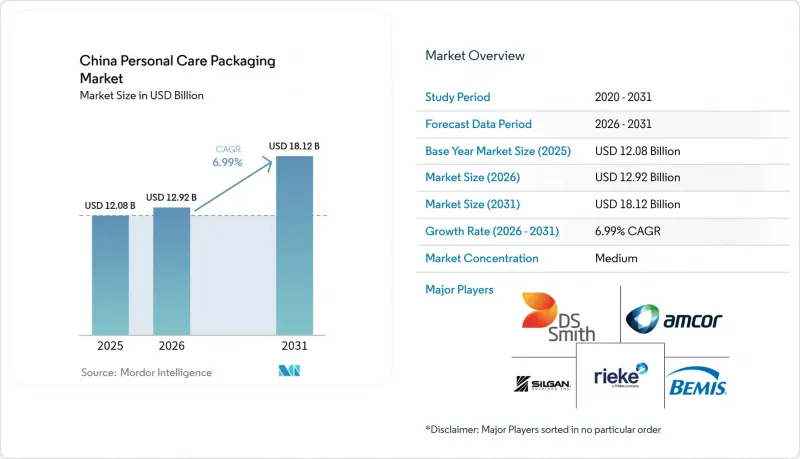
據 Mordor Intelligence 稱,2025 年中國個人護理包裝市場價值 120.8 億美元,預計到 2031 年將達到 181.2 億美元,而 2026 年為 129.2 億美元,預測期(2026-2031 年)複合年成長率為 6.99%。
本報告材料類型(塑膠、玻璃、金屬、紙/紙板、生物基/可堆肥塑膠)、包裝類型(塑膠瓶/罐、管/棒、幫浦、噴霧器、滴管、其他)、產品類型(護膚、護髮品、口腔護理品、其他)和永續性屬性(可回收、再生材料 (PCR) 含量、可生物分解性、其他永續性)進行分類。
中國個人護理包裝市場趨勢與洞察
美容和個人護理領域的電子商務快速成長
社群電商的爆炸性成長迫使品牌開發出既能承受長途運輸又能營造視覺吸引力強的開箱體驗的包裝。抖音美妝類商品交易總額在2021年至2023年間加倍以上,其演算法趨勢幾乎立即反映在包裝製造商的需求上。目前,品牌對包裝的抗衝擊性、體積重量和美觀(上鏡效果)的重視程度不相上下。隨著沿海省份以外地區履約中心的增加,具有緩衝作用且能降低運輸成本的軟包裝袋和輕質瓦楞紙板越來越受歡迎,進一步推動了中國個人護理包裝市場的發展勢頭。
可重複灌裝零售業態的興起
高階化妝品品牌紛紛設定循環經濟目標,加速了可重複使用補充裝、濃縮液袋和店內散裝分配器的測試。資生堂的目標是到2025年實現100%永續性包裝,並計劃在其主要產品系列中推廣補充裝,為此,本地ODM廠商正在重新配置射出成型線,以適應插入式墨盒的生產。上海某購物中心的初步試點測試表明,如果補充裝站位於銷售區附近,消費者更容易接受可重複使用的內芯容器。這不僅促進了重複購買,還減少了材料消耗。
樹脂和鋁價格波動
原油價格波動以及地緣政治不穩定導致的原物料價格波動,正給加工商的利潤率帶來壓力。萬凱等PET切片生產商計劃在2024年底將運轉率降至76%,由此造成的供應短缺迫使加工商透過簽訂個多月合約進行避險,或轉向生產HDPE和PP共混物。難以承受額外成本的中小型企業可能成為收購目標,這預示著中國個人護理包裝市場將逐步重組。
細分市場分析
由於成本效益和生產過程的柔軟性,預計到2025年,塑膠仍將佔據中國個人護理包裝市場58.12%的佔有率。然而,GB 23350-2021標準對內層間距比設定的上限促使品牌商考慮採用更薄的壁厚或使用紙板套作為二次包裝。在消費者將紡織包裝與環保理念聯繫起來的背景下,紙和紙板包裝實現了顯著成長,複合年成長率達到8.11%。在以重量為象徵的奢華護膚領域,玻璃的使用量保持穩定;而在高階除臭劑市場,符合無限循環利用理念的金屬氣霧罐正日益受到青睞。樹脂價格的波動也進一步推動了中國個人護理包裝市場整體採用複合材料策略。
儘管生物基聚合物的穩定來源正在湧現,但許多混合物仍需工業堆肥條件,而這些條件目前仍然短缺。因此,製造商正在投資研發單一材料的聚丙烯(PP)管和高消費再生塑膠(PCR)含量的聚對苯二甲酸乙二醇寶特瓶,這些產品既符合可回收性標準,又不影響其阻隔性能。國有銀行的綠色金融產品預計將降低維修生產線以適應再生材料的相關資本成本,而材料的選擇也可能與永續性評估標準和原料成本對沖密切相關。
2025年,塑膠瓶罐將佔總銷售額的41.12%,這主要得益於成熟的吹塑成型設備和消費者對其的熟悉度。同時,軟質塑膠的複合年成長率(CAGR)為7.95%,因為品牌利用輕量化來降低宅配成本。防篡改拉鍊和風琴式底部設計如今已成為標配,既能確保產品在經過多個配送中心的運輸過程中完好無損,又能提供平整的正面,方便在網紅影片中拍攝特寫鏡頭。隨著男士護理熱潮的興起,管狀和棒狀包裝產品正逐漸受到歡迎,而可重複填充的包裝則有助於減少高階護膚品對環境的影響。泵頭、滴管和按壓式包裝由於金屬彈簧部件而面臨成本壓力,但它們也受益於中國個人護理包裝市場對精準用量的需求,從而推動了優質化趨勢的發展。
紙板運輸箱正從普通的牛皮紙立方體演變為可客製印刷、聯名品牌的社交媒體故事講述平台。遵守GB 43352-2023快捷郵件包裝法規(該法規限制重金屬含量)仍然是一項必要要求,迫使加工商轉向水性油墨和澱粉基黏合劑。氣霧罐和特殊玻璃容器雖然在數量上屬於小眾市場,但由於香水和水療級護理產品的平均售價較高,以金額為準佔比卻高於平均水平。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 美容和個人護理領域的電子商務快速成長
- 可重複灌裝零售模式的興起
- 護膚和化妝品價格上漲
- 區域城市中男性儀容修飾的普及
- 人工智慧驅動的設計和快速原型製作
- 關於「過度包裝」的強制規定(GB 23350-2021)
- 市場限制因素
- 樹脂和鋁價格波動
- 多層複合材料回收能力的瓶頸
- 更嚴格的塑膠碳強度分配標準
- 二級包裝中的仿冒風險
- 重要法規結構的評估
- 價值鏈分析
- 技術展望
- 波特五力模型
- 對關鍵相關人員的影響評估
- 主要用例和案例研究
- 宏觀經濟因素對市場的影響
- 投資分析
第5章 市場區隔
- 依材料類型
- 塑膠
- 玻璃
- 金屬
- 紙張和紙板
- 生物基可堆肥塑膠
- 按包裝類型
- 塑膠瓶和罐子
- 管狀棒
- 泵浦、噴霧器、滴管
- 氣霧罐和金屬容器
- 折疊紙箱
- 瓦楞紙箱
- 軟質塑膠(小袋、小袋、保鮮膜)
- 蓋子與封口裝置
- 可填充和可重複使用的系統
- 依產品類型
- 護膚
- 護髮
- 口腔護理
- 彩妝品
- 男士理容
- 除臭香氛
- 嬰兒護理
- 永續性屬性
- 可回收(單一材料)
- 回收利用材料(PCR)的含量
- 可生物分解/可堆肥
- 可重複填充,可退回。
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Albea SA
- Amcor plc
- Silgan Holdings Inc.
- HCP Packaging(Shanghai)Co., Ltd.
- Berry Global Group, Inc.
- Gerresheimer AG
- AptarGroup, Inc.
- RPC Group Ltd(Berry Consumer Packaging Intl.)
- DS Smith Plc
- Huhtamaki Oyj
- Quadpack Industries, SA
- Rieke Packaging Systems Ltd.
- Shanghai Luxe-Pack Co., Ltd.
- Zhejiang Jinsheng New-Material Holding Group Co., Ltd.
- Shandong Yuhua Packing Products Co., Ltd.
- Guangzhou Beauty Packaging Co., Ltd.
- Xiamen Hexing Packaging Co., Ltd.
- Taizhou Forest Color Printing Packing Co., Ltd.
- Yunnan Yuxi Paper Co., Ltd.
- Ningbo NBG Plastic Packaging Co., Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the China personal care packaging market size was valued at USD 12.08 billion in 2025 and estimated to grow from USD 12.92 billion in 2026 to reach USD 18.12 billion by 2031, at a CAGR of 6.99% during the forecast period (2026-2031).
This report is Segmented by Material Type (Plastic, Glass, Metal, Paper and Paperboard, and Bio-Based and Compostable Plastics), Packaging Type (Plastic Bottles and Jars, Tubes and Sticks, Pumps, Sprayers and Droppers, and More), Product Type (Skincare, Haircare, Oral Care, and More), and Sustainability Attribute (Recyclable, Post-Consumer Recycled (PCR) Content, Biodegradable, and More).
China Personal Care Packaging Market Trends and Insights
E-commerce boom for beauty and personal care
Explosive social-commerce growth is forcing brands to engineer packs capable of surviving wide-radius fulfilment while staging a photogenic unboxing moment. Douyin's beauty GMV more than doubled between 2021 and 2023, turning platform algorithm trends into near-instant packaging briefs for converters. Brands now weigh impact resistance, dimensional weight, and camera-ready aesthetics in equal measure. As fulfillment centers proliferate outside coastal provinces, flexible pouches and lightweight corrugates gain favor for their cushioning and freight-saving attributes, reinforcing the momentum of the China personal care packaging market.
Rise of refill-ready retail formats
Circularity targets from premium beauty houses accelerated trials of refill pods, concentrate sachets, and in-store bulk dispensers. Shiseido aims for 100% sustainable packaging by 2025 and has extended refill options to hero SKUs, prompting local ODMs to retool injection-molding lines for plug-in cartridges. Early pilots in Shanghai malls show consumers accepting reusable cores when refill stations are adjacent to point-of-sale, unlocking repeat-purchase stickiness and trimming material footprints.
Volatile resin and aluminum prices
Feedstock swings, driven by oil price gyrations and geopolitical uncertainty, are compressing converter margins. PET chip producers such as Wankai trimmed operating rates to 76% in late 2024, tightening supply and pushing converters to hedge through multi-month contracts or diversify into HDPE and PP blends. Smaller firms struggling to absorb surcharges may become acquisition targets, spurring gradual consolidation within the China personal care packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Premiumization of skincare and cosmetic SKUs
- Male grooming uptake in lower-tier cities
- Recycling capacity bottlenecks for multi-layer laminates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic retained 58.12% of the China personal care packaging market share in 2025 owing to cost efficiency and process agility. Yet the GB 23350-2021 interspace ratio cap is prompting brands to trim wall thickness and explore paperboard sleeves for secondary packs. Paper and paperboard's 8.11% CAGR positions it as the standout growth engine, propelled by consumers equating fiber-based packs with environmental stewardship. Glass volumes are stabilizing in prestige skincare where weight signals luxury, while metal aerosols gain favor in premium deodorants as they align with infinitely recyclable narratives. Volatile resin prices further amplify the case for blended substrate strategies across the China personal care packaging market.
A steady pipeline of bio-based polymers has emerged, but many blends require industrial composting conditions that remain scarce. Consequently, producers are investing in mono-material PP tubes and PCR-rich PET bottles that meet recyclability thresholds without compromising barrier performance. State-owned banks' green finance instruments are expected to lower capital costs for retrofitting lines capable of handling recycled content, keeping material decisions tightly linked to both sustainability scorecards and input-cost hedging.
Plastic bottles and jars controlled 41.12% of 2025 revenues, backed by entrenched blow-molding assets and consumer familiarity. Flexible plastic pouches, however, are clocking an 7.95% CAGR as brands exploit weight savings that translate into lower courier tariffs. Tamper-evident zippers and gusseted bases are now standard to survive multi-node delivery routes while presenting flat fronts for influencer video close-ups. Tubes and sticks gain incremental traction alongside the male grooming boom, while refill cartridges enable footprint reduction in top-shelf skincare. Pumps, droppers, and actuators face cost pressure from metal spring components but benefit from premiumization that values dosage accuracy within the China personal care packaging market.
Corrugated shippers are evolving from plain kraft cubes into co-branded, print-on-demand canvases for social-media storytelling. Yet they must still comply with the GB 43352-2023 express-pack regulation limiting heavy-metal content, nudging converters toward water-based inks and starch adhesives. Aerosol cans and specialty glass remain niche by volume but over-index in value due to fragrance and spa-grade treatments that command higher averaged selling prices.
Complete Report Scope:
- By Material Type
- Plastic
- Glass
- Metal
- Paper and Paperboard
- Bio-based and Compostable Plastics
- By Packaging Type
- Plastic Bottles and Jars
- Tubes and Sticks
- Pumps, Sprayers and Droppers
- Aerosol Cans and Metal Containers
- Folding Cartons
- Corrugated Boxes
- Flexible Plastic (Pouches, Sachets, Wraps)
- Caps and Closures
- Refillable / Reuse Systems
- By Product Type
- Skincare
- Haircare
- Oral Care
- Color Cosmetics
- Men's Grooming
- Deodorants and Fragrances
- Baby Care
- By Sustainability Attribute
- Recyclable (Mono-material)
- Post-Consumer Recycled (PCR) Content
- Biodegradable / Compostable
- Refillable / Returnable
List of Companies Covered in this Report:
- Albea S.A.
- Amcor plc
- Silgan Holdings Inc.
- HCP Packaging (Shanghai) Co., Ltd.
- Berry Global Group, Inc.
- Gerresheimer AG
- AptarGroup, Inc.
- RPC Group Ltd (Berry Consumer Packaging Intl.)
- DS Smith Plc
- Huhtamaki Oyj
- Quadpack Industries, S.A.
- Rieke Packaging Systems Ltd.
- Shanghai Luxe-Pack Co., Ltd.
- Zhejiang Jinsheng New-Material Holding Group Co., Ltd.
- Shandong Yuhua Packing Products Co., Ltd.
- Guangzhou Beauty Packaging Co., Ltd.
- Xiamen Hexing Packaging Co., Ltd.
- Taizhou Forest Color Printing Packing Co., Ltd.
- Yunnan Yuxi Paper Co., Ltd.
- Ningbo NBG Plastic Packaging Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce boom for beauty and personal care
- 4.2.2 Rise of refill-ready retail formats
- 4.2.3 Premiumisation of skincare and cosmetic SKUs
- 4.2.4 Male grooming uptake in lower-tier cities
- 4.2.5 AI-enabled design and rapid prototyping
- 4.2.6 Mandatory "excessive-packaging" compliance (GB 23350-2021)
- 4.3 Market Restraints
- 4.3.1 Volatile resin and aluminum prices
- 4.3.2 Recycling capacity bottlenecks for multi-layer laminates
- 4.3.3 Stricter carbon-intensity quotas for plastics
- 4.3.4 Counterfeiting risk in secondary packaging
- 4.4 Evaluation of Critical Regulatory Framework
- 4.5 Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact Assessment of Key Stakeholders
- 4.9 Key Use Cases and Case Studies
- 4.10 Impact on Macroeconomic Factors of the Market
- 4.11 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.2 Glass
- 5.1.3 Metal
- 5.1.4 Paper and Paperboard
- 5.1.5 Bio-based and Compostable Plastics
- 5.2 By Packaging Type
- 5.2.1 Plastic Bottles and Jars
- 5.2.2 Tubes and Sticks
- 5.2.3 Pumps, Sprayers and Droppers
- 5.2.4 Aerosol Cans and Metal Containers
- 5.2.5 Folding Cartons
- 5.2.6 Corrugated Boxes
- 5.2.7 Flexible Plastic (Pouches, Sachets, Wraps)
- 5.2.8 Caps and Closures
- 5.2.9 Refillable / Reuse Systems
- 5.3 By Product Type
- 5.3.1 Skincare
- 5.3.2 Haircare
- 5.3.3 Oral Care
- 5.3.4 Color Cosmetics
- 5.3.5 Men's Grooming
- 5.3.6 Deodorants and Fragrances
- 5.3.7 Baby Care
- 5.4 By Sustainability Attribute
- 5.4.1 Recyclable (Mono-material)
- 5.4.2 Post-Consumer Recycled (PCR) Content
- 5.4.3 Biodegradable / Compostable
- 5.4.4 Refillable / Returnable
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Albea S.A.
- 6.4.2 Amcor plc
- 6.4.3 Silgan Holdings Inc.
- 6.4.4 HCP Packaging (Shanghai) Co., Ltd.
- 6.4.5 Berry Global Group, Inc.
- 6.4.6 Gerresheimer AG
- 6.4.7 AptarGroup, Inc.
- 6.4.8 RPC Group Ltd (Berry Consumer Packaging Intl.)
- 6.4.9 DS Smith Plc
- 6.4.10 Huhtamaki Oyj
- 6.4.11 Quadpack Industries, S.A.
- 6.4.12 Rieke Packaging Systems Ltd.
- 6.4.13 Shanghai Luxe-Pack Co., Ltd.
- 6.4.14 Zhejiang Jinsheng New-Material Holding Group Co., Ltd.
- 6.4.15 Shandong Yuhua Packing Products Co., Ltd.
- 6.4.16 Guangzhou Beauty Packaging Co., Ltd.
- 6.4.17 Xiamen Hexing Packaging Co., Ltd.
- 6.4.18 Taizhou Forest Color Printing Packing Co., Ltd.
- 6.4.19 Yunnan Yuxi Paper Co., Ltd.
- 6.4.20 Ningbo NBG Plastic Packaging Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 南美洲個人護理包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)個人護理包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)美國個人保健產品包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 全球個人護理包裝市場,2025-2032年
 個人護理包裝市場預測至2034年-按產品類型、包裝形式、材料和地區分類的全球分析個人護理包裝市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區分類,預測2026-2034年
 個人護理包裝市場分析及預測(至2035年):按類型、產品類型、材料類型、應用、技術、最終用戶、製程、組件和功能分類
 個人護理包裝市場規模、佔有率和成長分析(按材料、產品類型、應用、包裝類型和地區分類)-2026-2033年產業預測個人護理包裝市場-2026-2031年預測中東和非洲的個人護理包裝:市場佔有率分析、行業趨勢和成長預測(2025-2030)