


 |
市場調查報告書
商品編碼
2121682
美國個人保健產品包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)US Personal Care Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
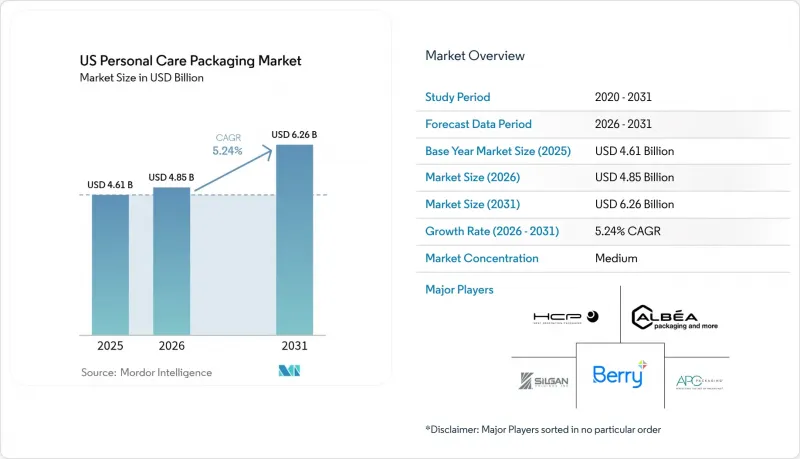
據 Mordor Intelligence 稱,2025 年美國個人保健產品包裝市場價值為 46.1 億美元,預計到 2031 年將從 2026 年的 48.5 億美元成長至 62.6 億美元,預測期(2026-2031 年)複合年成長率為 5.24%。
本報告按材料類型(塑膠、玻璃、金屬、紙張和紙板)、產品類型(瓶裝、管裝和棒狀、泵裝和分配器、袋裝等)、應用領域(護膚、護髮、口腔護理等)以及永續性屬性(可回收、含再生材料、可重複灌裝/可重複使用、可堆肥/生物基)進行細分。市場預測以美元計價。
美國個人保健產品包裝市場的趨勢與洞察
可支配收入的增加正在提振對包裝商品的需求。
2024年,個人照護支出將達到每戶908美元,西方國家更高,平均年支出達1,038美元。薪資的穩定成長推動了全國個人保健產品包裝市場的需求,促使產品種類多樣化、包裝工藝升級以及小眾配方產品不斷湧現。玻璃和金屬容器受益最大,因為消費者將其與品質和永續性聯繫起來。
適合在 Instagram 上分享的美學理念正在加速優質化。
如今,設計也成為了一種行銷管道,品牌正積極投資於視覺效果出色的造型、壓花工藝和客製化色彩,力求在照片中呈現最佳效果。玻璃瓶和拉絲鋁製氣霧罐罐正逐漸取代傳統的HDPE瓶,因為它們更能契合環保訊息和社交平臺上的視覺敘事。歐萊雅與IBM合作,利用人工智慧訓練永續配方,清楚展現了科技融合如何兼顧外觀與功能。
高昂的研發成本和模具成本限制了創新。
開發新型吹塑成型模具和精密幫浦的成本可能超過每條生產線100萬美元。小規模的加工企業難以負擔多個原型產品的研發費用,尤其是在生物基樹脂需要專用設備和漫長的認證流程時。折疊式施用器的專利申請清楚地表明了差異化點膠技術背後的複雜性和資本密集度。
細分市場分析
由於成本低廉、設計柔軟性且供應鏈成熟,塑膠在2025年仍佔據美國個人保健產品包裝市場50.12%的佔有率。然而,受更嚴格的PFAS法規和消費者對可再生基材日益成長的支持推動,預計到2031年,紙和紙板包裝市場將以9.12%的複合年成長率成長。各大品牌正在試用阻隔塗佈紙盒和模塑纖維罐,這些包裝既能通過防潮測試,又不影響產品的展示效果。再生PET的採用以及先導工廠化學回收工廠的運作,有助於塑膠保持主導,並緩解人們對循環經濟的擔憂。
循環經濟政策正迫使加工商增加再生塑膠(PCR)的使用並建立回收機制。同時,玻璃和金屬也因其作為奢侈品的定位而受益。高階護膚品牌透過使用厚壁瓶和拉絲鋁棒來為其溢價辯護,並強調其可無限循環利用的特性。垂直整合也推動了材料創新,安姆科投資樹脂採購以確保為不斷成長的美國個人保健產品包裝市場提供再生塑膠就是一個典型的例子。
由於瓶裝產品因其熟悉度高、展示效果好以及用途廣泛(涵蓋乳液、洗髮精和沐浴露等多種產品),預計到2025年,瓶裝產品將占美國個人保健產品包裝市場規模的37.65%。然而,受電商領域容積效率提升和材料用量減少的推動,柔軟性袋預計將以10.78%的複合年成長率成長。可重複密封的吸嘴和自立式設計提升了消費者的便利性,而超薄膜則有助於減輕運輸重量。
軟管、棒狀包裝和精密泵適用於那些對劑量精度要求高於單位成本的應用場景,例如防曬油的SPF棒狀包裝和視網醇精華液的真空泵包裝。隨著品牌轉向使用單一材料紙質包裝以簡化家庭回收,可折疊紙盒的市場佔有率正在不斷成長。 NFC晶片和QR碼以各種形式將包裝提升為互動中心,並成為競爭激烈的美國個人保健產品包裝市場中的關鍵差異化因素。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 隨著可支配所得的增加,個人保健產品種類也不斷增加。
- 對「適合在Instagram上分享」的高階包裝設計的需求
- 電子商務的蓬勃發展需要適合運輸的保護性包裝。
- 訂閱和補充裝模式正在推動耐用型和可重複使用包裝的發展。
- 經美國運輸安全管理局 (TSA) 批准的旅行包裝,供消費者旅行時使用。
- 智慧/物聯網賦能的包裝,用於客戶參與和可追溯性
- 市場限制因素
- 與新形式和新材料相關的高昂研發成本和模具成本。
- 美國加強塑膠和 PFAS 法規
- 再生樹脂的價格和供應品質波動
- 補貨和退貨計劃中的逆向物流障礙
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依材料類型
- 塑膠
- 玻璃
- 金屬
- 紙張和紙板
- 依產品類型
- 瓶子
- 管子和棍子
- 泵浦和分配器
- 小袋
- 折疊紙箱
- 其他
- 透過使用
- 護膚
- 護髮
- 口腔護理
- 化妝品和彩妝品
- 除臭劑和香水
- 除毛膏
- 其他
- 永續性屬性
- 可回收(單一材料)
- 來自廢舊產品的再生(PCR)成分
- 可填充/可重複使用
- 可堆肥/生物基
第6章 競爭情勢
- 市場集中度
- 策略舉措和趨勢
- 市佔率分析
- 公司簡介
- Albea Services SA
- HCP Packaging Co. Ltd
- Berry Global Group Inc.
- Silgan Holdings Inc.
- DS Smith PLC
- Graham Packaging Company
- Kaufman Container
- AptarGroup Inc.
- Amcor PLC
- Cosmopak USA LLC
- APC Packaging
- Rieke Corp(Trimas)
- Berlin Packaging LLC
- Glenroy Inc.
- TricorBraun
- Quadpack
- ProAmpac
- WestRock Company
- Gerresheimer AG
- Sonoco Products Co.
- International Paper Co.
第7章 市場機會與未來展望
According to Mordor Intelligence, the US personal care packaging market size was valued at USD 4.61 billion in 2025 and estimated to grow from USD 4.85 billion in 2026 to reach USD 6.26 billion by 2031, at a CAGR of 5.24% during the forecast period (2026-2031).
This report is Segmented by Material Type (Plastic, Glass, Metal, Paper and Paperboard), Product Type (Bottles, Tubes and Sticks, Pumps and Dispensers, Pouches and More), Application (Skin Care, Hair Care, Oral Care, and More), Sustainability Attribute (Recyclable, Post-Consumer-Recycled Content, Refillable/Reusable, Compostable/Bio-based). The Market Forecasts are Provided in Terms of Value (USD).
US Personal Care Packaging Market Trends and Insights
Rising Disposable Income Fuels Pack Demand
Personal-care outlays reached USD 908 per household in 2024 and climb even higher in the West, where annual spending averaged USD 1,038. Steady wage gains translate into greater SKU variety, premium pack finishes and niche formulations, which in turn boost unit-volume requirements across the US personal care packaging market. Glass and metal formats benefit the most because consumers associate them with quality and sustainability.
Instagram-Ready Aesthetics Accelerate Premiumization
Design now doubles as a marketing channel, prompting brands to invest in striking shapes, embossing and custom colorways that photograph well. Glass jars and brushed-aluminum aerosols outperform conventional HDPE bottles because they align with eco-messaging and visual storytelling on social platforms. L'Oreal's partnership with IBM to train AI on sustainable formulations underscores how tech convergence supports both look and function.
High R&D and Tooling Costs Limit Innovation
Developing a new blow-mold or precision pump can exceed USD 1 million per line. Small converters struggle to fund multiple trials, particularly when bio-based resins demand specialized machinery and extended qualification. Patent filings for collapsible applicators illustrate the complexity as well as the capital intensity behind differentiated dispensing technology.
Other drivers and restraints analyzed in the detailed report include:
- E-commerce Drives Ship-Ready Protective Formats
- Subscription and Refill Models Favor Durable Solutions
- State-Level PFAS Rules Add Compliance Burden
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic retained 50.12% US personal care packaging market share in 2025 thanks to low cost, design flexibility and well-established supply chains. Yet the paper and paperboard segment is projected to log a 9.12% CAGR through 2031, buoyed by PFAS crackdowns and consumer favor for renewable substrates. Brands experiment with barrier-coated cartons and molded-fiber jars that pass moisture tests without compromising shelf appeal. Recycled PET integration and pilot chemical recycling plants help plastics defend their lead by easing circularity concerns.
Circular-economy policies push converters to raise post-consumer-resin (PCR) content and build take-back schemes. Simultaneously, glass and metal profit from luxury positioning: prestige skin-care labels deploy heavy-walled flacons and brushed-aluminum sticks to justify price premiums while touting infinite recyclability. Material innovation is also spurred by vertical integration, exemplified by Amcor's resin-sourcing investments that safeguard PCR supply for the expanding US personal care packaging market.
Bottles commanded 37.65% of the US personal care packaging market size in 2025 due to familiarity, shelf impact and versatility across lotions, shampoos and body washes. However, flexible pouches are projected to log an 10.78% CAGR, propelled by e-commerce cube-efficiency and lower material usage. Reclosable spouts and stand-up formats bolster consumer convenience, while ultra-thin films curb shipping weight.
Tubes, sticks and precision pumps cater to targeted applications think SPF sticks for sun-care or airless pumps for retinol serums where dosing accuracy matters more than unit cost. Folding cartons gain ground as brands migrate to mono-material paper solutions that simplify curbside recycling. Across all formats, NFC chips and QR codes elevate packs into engagement hubs, a key differentiator in the crowded US personal care packaging market.
Complete Report Scope:
- By Material Type
- Plastic
- Glass
- Metal
- Paper and Paperboard
- By Product Type
- Bottles
- Tubes and Sticks
- Pumps and Dispensers
- Pouches
- Folding Cartons
- Others
- By Application
- Skin Care
- Hair Care
- Oral Care
- Makeup and Color Cosmetics
- Deodorants and Fragrances
- Depilatories
- Others
- By Sustainability Attribute
- Recyclable (mono-material)
- Post-consumer-recycled (PCR) Content
- Refillable / Reusable
- Compostable / Bio-based
List of Companies Covered in this Report:
- Albea Services SA
- HCP Packaging Co. Ltd
- Berry Global Group Inc.
- Silgan Holdings Inc.
- DS Smith PLC
- Graham Packaging Company
- Kaufman Container
- AptarGroup Inc.
- Amcor PLC
- Cosmopak USA LLC
- APC Packaging
- Rieke Corp (Trimas)
- Berlin Packaging LLC
- Glenroy Inc.
- TricorBraun
- Quadpack
- ProAmpac
- WestRock Company
- Gerresheimer AG
- Sonoco Products Co.
- International Paper Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising consumption of personal-care SKUs on higher disposable income
- 4.2.2 Demand for premium, "Instagram-ready" pack aesthetics
- 4.2.3 E-commerce boom needing ship-ready protective formats
- 4.2.4 Subscription and refill models driving durable / reusable packs
- 4.2.5 TSA-size travel packs for on-the-go consumers
- 4.2.6 Smart / IoT-enabled packs for engagement and traceability
- 4.3 Market Restraints
- 4.3.1 High RandD and tooling costs for novel formats and materials
- 4.3.2 Tightening U.S. plastics and PFAS regulations
- 4.3.3 Volatile recycled-resin price and supply quality
- 4.3.4 Reverse-logistics friction for refill / return programs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Buyers
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.2 Glass
- 5.1.3 Metal
- 5.1.4 Paper and Paperboard
- 5.2 By Product Type
- 5.2.1 Bottles
- 5.2.2 Tubes and Sticks
- 5.2.3 Pumps and Dispensers
- 5.2.4 Pouches
- 5.2.5 Folding Cartons
- 5.2.6 Others
- 5.3 By Application
- 5.3.1 Skin Care
- 5.3.2 Hair Care
- 5.3.3 Oral Care
- 5.3.4 Makeup and Color Cosmetics
- 5.3.5 Deodorants and Fragrances
- 5.3.6 Depilatories
- 5.3.7 Others
- 5.4 By Sustainability Attribute
- 5.4.1 Recyclable (mono-material)
- 5.4.2 Post-consumer-recycled (PCR) Content
- 5.4.3 Refillable / Reusable
- 5.4.4 Compostable / Bio-based
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Developments
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Albea Services SA
- 6.4.2 HCP Packaging Co. Ltd
- 6.4.3 Berry Global Group Inc.
- 6.4.4 Silgan Holdings Inc.
- 6.4.5 DS Smith PLC
- 6.4.6 Graham Packaging Company
- 6.4.7 Kaufman Container
- 6.4.8 AptarGroup Inc.
- 6.4.9 Amcor PLC
- 6.4.10 Cosmopak USA LLC
- 6.4.11 APC Packaging
- 6.4.12 Rieke Corp (Trimas)
- 6.4.13 Berlin Packaging LLC
- 6.4.14 Glenroy Inc.
- 6.4.15 TricorBraun
- 6.4.16 Quadpack
- 6.4.17 ProAmpac
- 6.4.18 WestRock Company
- 6.4.19 Gerresheimer AG
- 6.4.20 Sonoco Products Co.
- 6.4.21 International Paper Co.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 南美洲個人護理包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)個人護理包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)中國個人護理包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 全球個人護理包裝市場,2025-2032年
 個人護理包裝市場預測至2034年-按產品類型、包裝形式、材料和地區分類的全球分析個人護理包裝市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區分類,預測2026-2034年
 個人護理包裝市場分析及預測(至2035年):按類型、產品類型、材料類型、應用、技術、最終用戶、製程、組件和功能分類
 個人護理包裝市場規模、佔有率和成長分析(按材料、產品類型、應用、包裝類型和地區分類)-2026-2033年產業預測個人護理包裝市場-2026-2031年預測中東和非洲的個人護理包裝:市場佔有率分析、行業趨勢和成長預測(2025-2030)