


 |
市場調查報告書
商品編碼
2154823
德國自動農業曳引機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Germany Autonomous Agricultural Tractors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
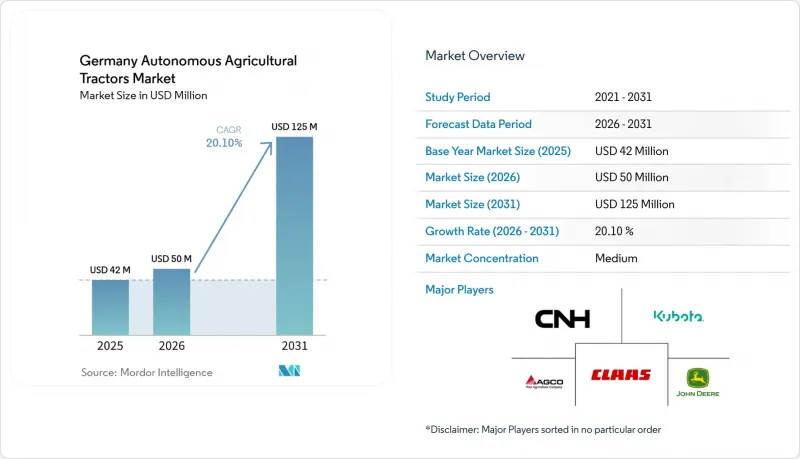
據 Mordor Intelligence 稱,2025 年德國自動農業曳引機市場價值 4,200 萬美元,預計到 2031 年將達到 1.25 億美元,而 2026 年為 5,000 萬美元,預測期(2026-2031 年)的複合年成長率為 20.10%。
德國自動駕駛農用曳引機市場的趨勢與洞察
農業勞動力短缺和熟練操作人員短缺
預計到2025年,德國農業工人數將減少3,000人(0.5%),降至56.2萬人。這反映出農業勞動力持續減少,隨著可用操作人員數量的減少,完成農場工作的壓力也隨之增加。根據德國聯邦統計局(Destatis)的數據,農民的平均年齡為56歲。季節性工人在播種和收穫高峰期仍然發揮著至關重要的作用。當熟練的操作人員無法到崗時,自動曳引機可以幫助農場完成日常作業。當一名主管人員統籌特定區域內的多台機器時,自動曳引機尤其有效。弗勞恩霍夫IVI研究所指出,協調多台機器的作業是降低每公頃勞動投入的手段。承包商可以利用這種模式,在較短的季節內為多個農場提供服務。這些因素正在推動德國對自動農業曳引機的需求,尤其是在大規模農場。
精密農業和互聯導航系統的引入
許多德國農場已經在使用導航系統、數位化記錄和連網農機設備。由於田地邊界和作業記錄已經數位化,這些工具為自動駕駛提供了切實可行的基礎。相容於 ISOBUS 的農機設備也減少了自動化田間作業所需的整合工作。擁有現有數位化田間管理系統的農場可以利用目前的作業數據來評估自動駕駛系統。開放的遠端資訊處理技術和互通平台對於多樣化的車輛配置至關重要。歐盟資料法與關於機器資料存取和使用的更廣泛討論息息相關。這項成熟的技術基礎將縮短從輔助導航到監督式自動駕駛的過渡期,從而促進德國自動駕駛農用曳引機市場的普及,而無需農場一次改變所有作業流程。
高昂的實施成本所帶來的限制並非大型企業所獨有。
全自動系統需要感測器、計算硬體、整合和安全檢驗。這些成本使得面積小於200公頃的農場難以證明採用新系統的合理性。這些設備會使曳引機的基礎價格增加3萬至8萬歐元(約3.42萬至9.12萬美元)。根據引用的資料集,德國有25.5萬家農業企業,其中許多企業的經營面積不到100公頃。考慮到這些企業的使用率,直接購買可能並不實際。服務合約和租賃可以幫助降低初始成本。低成本的改裝方案也是可行的選擇,但這並不能完全消除培訓、網路連接和支援方面的成本。這仍然是德國自動農用曳引機市場的一個主要阻礙因素。
細分市場分析
到2025年,31-100馬力等級的曳引機將佔德國自動駕駛農用曳引機市場的38.9%。此功率等級適合升級為自動駕駛系統,因為它能夠勝任各種犁地、播種和作物保護任務,配備導航功能的曳引機也擁有成熟的應用案例。由於這些曳引機可用於各種規模的田地和種植系統,因此該等級將成為許多自動駕駛應用的理想起點。
預計到2031年,功率超過100馬力的曳引機市場將以23.4%的複合年成長率成長。德國北部和東部的大面積耕地需要高功率曳引機進行連續犁地和播種。迪爾公司(Deere & Company)的自動駕駛曳引機「9RX」正是針對這一高功率應用場景,並配備了16個攝影機用於機器感知。由於這些曳引機經常需要在不同的地塊之間移動,因此需要考慮型號認證問題。功率低於30馬力的曳引機市場目前仍局限於特定應用領域,主要用於對軸荷低、尺寸緊湊的狹窄葡萄園和果園。
2025年,半自動系統將佔據德國自動農用曳引機市場64.0%的佔有率。這些系統能夠自動完成導航、轉向和作業等功能,同時保留操作員的角色。這種操作模式與目前的農業實踐相容,既降低了實施風險,又能讓操作員逐漸適應自動化作業。 2026年的一項針對德國農民的調查顯示,他們對採用機器人系統和智慧機械的意願相對較低,技術成熟度和對現有作業的干擾是他們最重要的評估標準。半自動設備透過維持人工監督,使農民能夠繼續積極參與田間作業,有助於減輕自動化對作業的影響。
預計到2031年,全自動系統將以25.0%的複合年成長率成長。歐盟農業機械框架要求從2027年起,對受監管的自主操作制定更明確的合規框架。 2026年4月,CLAAS KGaA mbH宣布,其「XERION 12」曳引機將配備由AgXeed開發的車輛控制單元。該單元將於2026年中期上市,屆時將支援駕駛人監督下的自動化田間作業。這一發展將使高階曳引機超越輔助駕駛模式。然而,該領域的成長仍將取決於認證、互聯性和操作員的信心。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 農業勞動力短缺和熟練工人短缺
- 精密農業和互聯導航系統的引入
- 政府支持智慧、低排放農業機械
- 透過 24 小時現場操作和監控多台機器,提高了生產效率。
- 改裝自動駕駛套件和具備自動駕駛功能的曳引機平台
- 果園和葡萄園特種作物的機械化
- 市場限制因素
- 高昂的實施成本所帶來的限制並非大型企業所獨有。
- 法規的模糊性延緩了全自動系統的引進。
- 連接性和定位精度差會影響運轉可靠性。
- 在與混合飛機中隊的兼容性和作戰準備方面仍有改進空間。
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按馬力
- 30馬力或以下
- 31~100 HP
- 100馬力或以上
- 按自動化級別
- 完全自主
- 半自動
- 透過驅動系統
- 柴油引擎
- 混合
- 電池式電動車
- 透過使用
- 犁地
- 播種
- 收成
- 果園和葡萄園的經營
- 按組件
- GPS和GNSS
- 感測器和視覺系統
- LiDAR和雷達模組
- 控制和導航軟體
- 按農場規模
- 小規模(不足100公頃)
- 中等規模(100-500公頃)
- 大型(超過500公頃)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- AGCO Corporation
- Deere & Company
- CNH Industrial NV
- CLAAS KGaA mbH
- Kubota Corporation
- SDF Group
- YANMAR HOLDINGS CO., LTD.
- Mahindra and Mahindra Limited
- TYM Corporation
- ZETOR TRACTORS as
- ISEKI and Co., Ltd.
- JCBamford Excavators Limited
- Monarch Tractor
- AgXeed BV
- NEXAT GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the Germany autonomous agricultural tractors market size was valued at USD 42 million in 2025 and is estimated to grow from USD 50 million in 2026 to reach USD 125 million by 2031, at a CAGR of 20.10% during the forecast period (2026-2031).
Germany Autonomous Agricultural Tractors Market Trends and Insights
Farm Labor Shortages and Skilled Operator Scarcity
Agricultural employment in Germany declined by 3,000 workers, or 0.5%, to 562,000 in 2025, continuing the downward trend in the agricultural workforce and increasing pressure to complete fieldwork with fewer available operators. The average farmer age is 56, as reported by the Federal Statistical Office (Destatis). Seasonal labor remains important during peak planting and harvest periods. Autonomous tractors can help farms complete routine tasks when skilled operators are unavailable, with the greatest benefit achieved when one supervisor oversees multiple machines across defined field areas. Fraunhofer IVI identifies multi-machine coordination as a means of reducing labor input per hectare. Contractors can apply this model to deliver services across multiple farms within short seasonal windows. These factors support demand in the Germany autonomous agricultural tractors market, particularly on larger arable farms.
Precision Agriculture and Connected Guidance Stack Adoption
Many German farms already use guidance systems, digital records, and connected implements. These tools provide a practical foundation for autonomous operation, as field boundaries and work records are already digitized. ISOBUS-enabled implements also reduce the integration work required for automated field tasks. Farms with existing digital field management can evaluate autonomous systems using their current operating data. Open telematics and interoperable platforms are important for mixed fleets. The EU Data Act is relevant to the broader discussion of access to and use of machine data. This established technology base shortens the transition from assisted guidance to supervised autonomy, supporting adoption in the Germany autonomous agricultural tractors market without requiring farms to change all operating processes at once.
High Acquisition Cost Limits Reach Beyond Large Enterprises
A fully autonomous system requires sensors, computing hardware, integration work, and safety validation. These costs make it difficult to justify a new system for farms below 200 hectares. The equipment adds EUR 30,000 to EUR 80,000 (USD 34,200 to USD 91,200) to the base tractor cost. Germany had 255,000 agricultural holdings in the cited dataset, many of which operated below 100 hectares. Utilization levels at these holdings may not support a direct purchase. Service contracts and leasing can reduce the upfront cost. Lower-cost retrofit options may also help, but they do not eliminate the costs of training, connectivity, and support. This remains a central constraint on the Germany autonomous agricultural tractors market.
Other drivers and restraints analyzed in the detailed report include:
- Government Support for Smart and Low-Emission Farm Equipment
- Productivity Gains From Continuous Field Operations and Multi-Machine Supervision
- Regulatory Ambiguity Delays Fully Unattended Deployment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 31 to 100 HP segment held 38.9% of the Germany autonomous agricultural tractors market in 2025. This power class supports a wide range of tillage, sowing, and crop-protection tasks and has a substantial installed base of guidance-enabled tractors, making it suitable for autonomy upgrades. These machines can be used across a wide range of field sizes and crop systems, making this segment a practical starting point for many autonomous deployments.
The above 100 HP category is forecast to grow at a 23.4% CAGR through 2031. Large arable operations in North and East Germany require high power for continuous tillage and drilling work. Deere & Company's autonomous 9RX targets this high-power use case and uses 16 cameras for machine perception. These tractors are more likely to travel between parcels, which raises type-approval considerations. The up to 30 HP category remains specialized, used primarily for narrow vineyard and orchard applications where low axle loads and compact dimensions are necessary.
Semi-autonomous systems held 64.0% of the Germany autonomous agricultural tractors market share in 2025. These systems automate guidance, turns, and implement functions while retaining an operator role. This operating model aligns with current farm practices and reduces the risk of adoption, while allowing operators to build familiarity with automated tasks. A 2026 study of German arable farmers found that robotic systems and smart machines had relatively low adoption readiness, with technological maturity and the degree of disruption among the most important evaluation criteria. Semi-autonomous equipment can help reduce perceived disruption by maintaining human oversight and allowing farmers to retain an active role in field operations.
Fully autonomous systems are forecast to grow at a 25.0% CAGR through 2031. The EU machinery framework provides a clearer compliance structure for supervised autonomy from 2027. In April 2026, CLAAS KGaA mbH announced that its XERION 12 would receive an AgXeed-developed Vehicle Control Unit, available from mid-2026 for driver-monitored automated field operations. This development moves premium tractors beyond assisted guidance. However, growth in this category will remain dependent on certification, connectivity, and operator confidence.
Complete Report Scope:
- By Horsepower
- Up to 30 HP
- 31 to 100 HP
- Above 100 HP
- By Automation Level
- Fully Autonomous
- Semi-Autonomous
- By Drive Type
- Diesel
- Hybrid
- Battery-Electric
- By Application
- Tillage
- Sowing
- Harvesting
- Orchard and Vineyard Operations
- By Component
- GPS and GNSS
- Sensors and Vision Systems
- LiDAR and Radar Modules
- Control and Navigation Software
- By Farm Size
- Small (Less than 100 ha)
- Medium (100-500 ha)
- Large (More than 500 ha)
List of Companies Covered in this Report:
- AGCO Corporation
- Deere & Company
- CNH Industrial N.V.
- CLAAS KGaA mbH
- Kubota Corporation
- SDF Group
- YANMAR HOLDINGS CO., LTD.
- Mahindra and Mahindra Limited
- TYM Corporation
- ZETOR TRACTORS a.s.
- ISEKI and Co., Ltd.
- J.C.Bamford Excavators Limited
- Monarch Tractor
- AgXeed B.V.
- NEXAT GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Farm labor shortages and skilled operator scarcity
- 4.2.2 Precision agriculture and connected guidance stack adoption
- 4.2.3 Government support for smart and low-emission farm equipment
- 4.2.4 Productivity gains from 24-hour field operations and multi-machine supervision
- 4.2.5 Retrofit autonomy kits and autonomy-ready tractor platforms
- 4.2.6 Specialty-crop mechanization in orchards and vineyards
- 4.3 Market Restraints
- 4.3.1 High acquisition cost limits reach beyond large enterprises
- 4.3.2 Regulatory ambiguity delays fully unattended deployment
- 4.3.3 Connectivity and positioning weaknesses reduce operating confidence
- 4.3.4 Mixed-fleet compatibility and service readiness still need work
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size And Growth Forecasts (Value)
- 5.1 By Horsepower
- 5.1.1 Up to 30 HP
- 5.1.2 31 to 100 HP
- 5.1.3 Above 100 HP
- 5.2 By Automation Level
- 5.2.1 Fully Autonomous
- 5.2.2 Semi-Autonomous
- 5.3 By Drive Type
- 5.3.1 Diesel
- 5.3.2 Hybrid
- 5.3.3 Battery-Electric
- 5.4 By Application
- 5.4.1 Tillage
- 5.4.2 Sowing
- 5.4.3 Harvesting
- 5.4.4 Orchard and Vineyard Operations
- 5.5 By Component
- 5.5.1 GPS and GNSS
- 5.5.2 Sensors and Vision Systems
- 5.5.3 LiDAR and Radar Modules
- 5.5.4 Control and Navigation Software
- 5.6 By Farm Size
- 5.6.1 Small (Less than 100 ha)
- 5.6.2 Medium (100-500 ha)
- 5.6.3 Large (More than 500 ha)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AGCO Corporation
- 6.4.2 Deere & Company
- 6.4.3 CNH Industrial N.V.
- 6.4.4 CLAAS KGaA mbH
- 6.4.5 Kubota Corporation
- 6.4.6 SDF Group
- 6.4.7 YANMAR HOLDINGS CO., LTD.
- 6.4.8 Mahindra and Mahindra Limited
- 6.4.9 TYM Corporation
- 6.4.10 ZETOR TRACTORS a.s.
- 6.4.11 ISEKI and Co., Ltd.
- 6.4.12 J.C.Bamford Excavators Limited
- 6.4.13 Monarch Tractor
- 6.4.14 AgXeed B.V.
- 6.4.15 NEXAT GmbH
7 Market Opportunities And Future Outlook

 自動駕駛曳引機市場報告:趨勢、預測和競爭分析(至2035年)
 美國自主農業曳引機:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)英國自動農業曳引機:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)中國自主農業曳引機市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)
 自動曳引機市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。
 自主和半自動自主曳引機市場:按產品、曳引機類型、組件、自主程度、功率輸出、推進類型、應用和最終用戶分類-全球預測,2026-2032年自動駕駛曳引機:市佔率分析、產業趨勢與統計、成長預測(2026-2031)
 自動曳引機市場規模、佔有率、趨勢和預測:按組件、產量、作物類型、應用和地區分類,2026-2034年2026-2034年全球自動駕駛曳引機市場規模、佔有率、趨勢和成長分析報告
 2026年全球自動播種機市場報告