


 |
市場調查報告書
商品編碼
2154799
南美洲一次性塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)South America Single-use Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
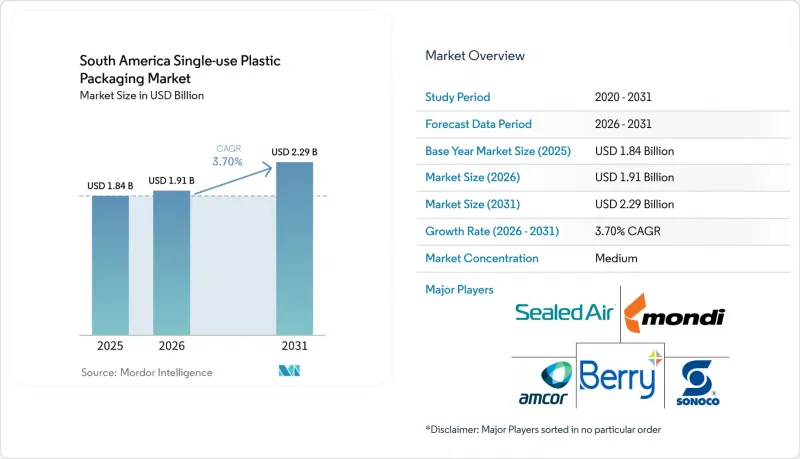
據 Mordor Intelligence 稱,2025 年南美洲一次性塑膠包裝市場價值為 18.4 億美元,預計到 2031 年將達到 22.9 億美元,而 2026 年為 19.1 億美元,2026 年至 2031 年預測期內的複合年成長率為 3.70%。
南美洲一次性塑膠包裝市場趨勢及洞察。
食品配送和快餐店的擴張
外帶和快餐店需要能夠保護食品並確保安全處理的包裝。隨著外送平台使用密封袋、托盤和包裝袋來包裝每份訂單,南美洲一次性塑膠包裝市場正從中受益。雲廚房則使用薄膜袋、防篡改托盤和熱封袋,因為它們適合快速烹飪。對於得來速和應用程式訂餐,多個獨立包裝的食品可能會被放在同一個保護性外袋中。即使餐廳菜單簡化,這也會增加每份訂單的包裝材料用量。因此,隨著餐飲服務管道的擴張,對安全配送包裝的需求將成為推動包裝轉換器需求持續成長的主要動力。
預包裝食品和飲料消費量增加
2025年,巴西加工食品產量年增4.2%。這一成長主要得益於雞肉、即溶咖啡和濃縮液果汁等產品,這些產品在出口運輸過程中需要阻隔包裝。隨著零售商和餐飲服務企業對易於補充包裝的需求不斷成長,調味品包裝袋的使用量也不斷擴大。這種轉變使得每單位配料的重量得以降低,同時增加了該品類包裝單元的使用數量。機能飲料、能量飲料和冷藏乳製品也需要具有阻隔性的透明PET和PP容器。隨著便利商店的擴張,對能夠透過分散分銷網路保護產品且價格合理的包裝的需求進一步增加。這些需求確保了食品和飲料消費在南美洲一次性塑膠包裝市場中繼續佔據核心地位。
與監管一次性塑膠和生產者延伸責任制(EPR)相關的成本
巴西聯邦法令第12688/2025號建立了全國性的塑膠包裝逆向物流框架。該框架設定了2026年塑膠包裝回收率達到32%的目標,並要求再生材料含量達到22%,但對大中小型企業的實施時間有所不同。智利於2026年2月推出了進一步限制餐廳使用一次性產品的規定。餐飲服務商只有在符合堆肥要求或消費者提出要求的情況下,才能將某些產品外送。這些法規提高了經認證的可回收和可堆肥設計的重要性。此外,依賴多材料結構的加工商將面臨更高的合規、測試和文件編製成本。
細分市場分析
到2025年,瓶罐將佔銷售額的36.14%,這主要得益於飲料、醫藥和個人護理等行業對包裝剛性和產品可見度的需求。 PET和PP瓶在有組織的零售業中仍佔據重要地位,尤其適用於需要防篡改包裝和透明標籤的品牌產品。這些包裝形式在南美洲一次性塑膠包裝市場所佔佔有率反映了它們適用於大規模生產的消費品。因此,硬質瓶是南美洲一次性塑膠包裝市場穩定需求的重要來源。預計到2031年,包裝袋和包裝袋的複合年成長率將達到4.83%。這一成長反映了對用於調味品、乳製品和乾貨配料的輕質包裝的需求。
托盤、杯子和蓋子廣泛應用於食品服務和外賣行業,其使用量與已調理食品量密切相關。改良的熱成型技術使得托盤可以做得更薄,同時保持必要的強度以便於搬運。翻蓋式包裝盒因其便於查看內容物,仍然是生鮮食品和烘焙食品的理想選擇。薄膜和包裝材料則應用於工業拉伸膜、農業地膜以及食品熱封等領域。紙質替代品可能會限制某些二次包裝應用領域的成長。康斯坦蒂亞軟性包裝公司(Constantia Flexibles)在智利推出了一款專為低密度聚乙烯(LDPE)回收系統設計的單材料聚乙烯(PE)拉鍊袋。
聚乙烯(用於薄膜、包裝袋和瓶子)預計到2025年將佔材料銷售額的35.05%。其廣泛的應用和成本優勢支撐了南美洲一次性塑膠包裝市場的需求。它也為南美洲一次性塑膠包裝市場的加工商提供了一種易於取得的樹脂基料,可以滿足各種終端用途的需求。聚丙烯(PP)廣泛用於瓶蓋、微波爐適用托盤和耐熱食品服務容器。聚對苯二甲酸乙二醇酯(PET)在透明瓶和食品托盤領域繼續發揮重要作用。 2025年,PET現貨價格預計將達到每公斤1.06美元,再生PET的價格預計將達到每公斤1.12美元。
由於智利和巴西地方政府實施的法規限制了聚苯乙烯和發泡聚苯乙烯的市場准入。這推動了食品服務領域對聚丙烯(PP)和聚對苯二甲酸乙二醇酯(PET)替代材料的需求。預計到2031年,聚乳酸(PLA)的複合年成長率將達到4.62%,是所列材料中成長率最高的。巴西的甘蔗乙醇供應鏈正在推動生物基材料的發展。巴西生物技術公司Braschem宣布將於2026年推出用於食品接觸、醫療和衛生領域的生物基和循環聚烯產品。此外,巴西政府降低了用於食品接觸領域的PLA的進口關稅,這鼓勵了經認證的加工商採用該材料。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 食品配送和快餐店的擴張
- 包裝食品和飲料消費量的成長
- 電子商務與快速貿易中的履約需求
- 從硬質一次性包裝過渡到軟質一次性包裝
- 擴大可回收單一材料包裝
- 食品、農業和出口供應鏈的區域成長
- 市場限制因素
- 與監管一次性塑膠製品和生產者延伸責任相關的成本
- 石化樹脂價格波動
- 用於食品的再生塑膠供應有限。
- 多層包裝碎片回收系統
- 宏觀經濟因素對市場的影響
- 產業供應鏈分析
- 科技趨勢
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 瓶子和容器
- 袋子和小袋
- 托盤、杯子、蓋子
- 蛤殼
- 薄膜和包裝
- 其他產品類型
- 材料類型
- 聚乙烯
- 聚丙烯
- 聚對苯二甲酸乙二酯
- 聚苯乙烯和膨脹聚苯乙烯
- 聚乳酸
- 其他材料類型
- 按包裝類型
- 硬包裝
- 軟包裝
- 半剛性包裝
- 透過使用
- 食品包裝
- 飲料包裝
- 個人護理套裝
- 藥品包裝
- 家用和商用包裝
- 工業和農業包裝
- 最終用戶
- 餐飲服務業及速食店
- 零售商店和超級市場
- 電子商務與配送平台
- 消費品製造商
- 醫療和製藥製造商
- 個人護理和化妝品製造商
- 按地區
- 巴西
- 阿根廷
- 哥倫比亞
- 智利
- 其他南美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
- Mondi plc
- Sonoco Products Company
- Huhtamaki Oyj
- ProAmpac Holdings Inc.
- Constantia Flexibles Group GmbH
- Coveris Management GmbH
- Transcontinental Inc.
- Winpak Ltd.
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Plastipak Holdings, Inc.
- Valgroup Participacoes SA
- Logoplaste Group
- AptarGroup, Inc.
- CCL Industries Inc.
- Gerresheimer AG
- Graham Packaging Company, LP
- Comar, LLC
- ZARAPLAST SA
- Petropack SA
- EMUSA
- Megapack
第7章 市場機會與未來展望
According to Mordor Intelligence, the South America single-use plastic packaging market size was valued at USD 1.84 billion in 2025 and is estimated to grow from USD 1.91 billion in 2026 to reach USD 2.29 billion by 2031, at a CAGR of 3.70% during the forecast period 2026-2031.
South America Single-use Plastic Packaging Market Trends and Insights
Expansion of Food Delivery and Quick-Service Restaurants
Food delivery and quick-service restaurants require packaging that protects food and supports safe handling. The South America Single-use Plastic Packaging Market benefits when delivery operators use sealed bags, trays, and pouches for each order. Cloud kitchens use film pouches, tamper-evident trays, and heat-sealed bags because these formats are well-suited to rapid preparation cycles. Drive-through and app-based orders can include several individually packed items in one protected outer bag. This can increase the packaging used per order, even as restaurant menus become simpler. The requirement for secure delivery packaging, therefore, supports stable demand for converters as foodservice channels expand.
Growth of Packaged Food and Beverage Consumption
Brazil's processed-food output grew 4.2% year over year in 2025, led by poultry, instant coffee, and fruit concentrates that need barrier packaging during export transport. Pouches have gained use for condiments as retailers and foodservice companies seek refill-friendly formats. This shift can reduce the material weight of each unit while increasing the number of packaged units used in a category. Functional beverages, energy drinks, and chilled dairy products also require clear PET and PP containers with barrier properties. Growth in convenience retail creates further demand for affordable packs that can protect products through fragmented distribution networks. These needs keep food and beverage consumption central to the South America Single-use Plastic Packaging Market.
Single-Use Plastic Restrictions and Extended Producer Responsibility Costs
Brazil's Federal Decree No. 12,688/2025 established a national reverse-logistics framework for plastic packaging. The framework set a 32% recovery target and 22% recycled-content requirement for 2026, with different implementation dates for large and smaller companies. Chile introduced further requirements in February 2026 that restricted the use of single-use products in food establishments. Foodservice operators can provide certain products off-premises only when they meet compostability requirements or are requested by consumers. These rules increase the importance of certified recyclable and compostable designs. They also raise compliance, testing, and documentation costs for converters that rely on multi-material structures.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce and Quick-Commerce Fulfillment Demand
- Conversion From Rigid to Flexible Single-Use Formats
- Volatility in Petrochemical Resin Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bottles and Containers held 36.14% of 2025 revenue, supported by beverage, pharmaceutical, and personal care applications that require rigidity and product visibility. PET and PP bottles remain important in organized retail, particularly for branded products that require tamper-evident packaging and clear presentation. The share of the South America Single-use Plastic Packaging Market held by these formats reflects their fit with high-volume consumer products. This makes rigid bottles an important source of stable demand in the South America Single-use Plastic Packaging Market. Bags and Pouches are projected to grow at a 4.83% CAGR through 2031. Their growth reflects demand for lightweight packs used for condiments, dairy products, and dry food ingredients.
Trays, Cups, and Lids serve the foodservice and restaurant delivery sectors, where volume follows prepared-meal orders. Thermoforming improvements can reduce tray gauge while retaining the required strength for handling. Clamshells remain useful for fresh produce and bakery items because they allow product visibility. Films and Wraps support industrial stretch-film, agricultural mulch, and food heat-seal applications. Paper alternatives may limit growth in selected secondary-packaging uses. Constantia Flexibles launched a mono-material PE zipper pouch in Chile that was designed for LDPE collection systems.
Polyethylene accounted for 35.05% of material revenue in 2025 because it is used in films, bags, and bottles. Its broad use and cost profile sustain demand in the South America Single-use Plastic Packaging Market. It also provides converters with a widely available resin base for various end uses in the South America Single-use Plastic Packaging Market. PP is widely used for closures, microwave-safe trays, and heat-resistant foodservice containers. PET remains important for clear bottles and food trays. PET spot prices reached USD 1.06 per kilogram in 2025, while recycled PET was priced at USD 1.12 per kilogram.
Polystyrene and expanded polystyrene face lower market access as restrictions take effect in Chile and Brazilian municipalities. This supports demand for PP and PET alternatives in several foodservice uses. Polylactic Acid is projected to record a 4.62% CAGR through 2031, the fastest rate among the listed materials. Brazil's sugarcane-based ethanol supply chain supports the development of bio-based materials. Braskem presented bio-based and circular polyolefin grades for food-contact, healthcare, and hygiene uses in 2026. Brazil also reduces the import duty on PLA used in food-contact applications, thereby supporting adoption by certified converters.
Complete Report Scope:
- By Product Type
- Bottles and Containers
- Bags and Pouches
- Trays, Cups, and Lids
- Clamshells
- Films and Wraps
- Other Product Types
- By Material Type
- Polyethylene
- Polypropylene
- Polyethylene Terephthalate
- Polystyrene and Expanded Polystyrene
- Polylactic Acid
- Other Material Types
- By Packaging Format
- Rigid Packaging
- Flexible Packaging
- Semi-Rigid Packaging
- By Application
- Food Packaging
- Beverage Packaging
- Personal Care Packaging
- Pharmaceutical Packaging
- Household and Institutional Packaging
- Industrial and Agricultural Packaging
- By End User
- Foodservice and Quick-Service Restaurants
- Retail and Supermarkets
- E-Commerce and Delivery Platforms
- Consumer Goods Manufacturers
- Healthcare and Pharmaceutical Manufacturers
- Personal Care and Cosmetics Manufacturers
- By Geography
- Brazil
- Argentina
- Colombia
- Chile
- Rest of South America
List of Companies Covered in this Report:
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
- Mondi plc
- Sonoco Products Company
- Huhtamaki Oyj
- ProAmpac Holdings Inc.
- Constantia Flexibles Group GmbH
- Coveris Management GmbH
- Transcontinental Inc.
- Winpak Ltd.
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Plastipak Holdings, Inc.
- Valgroup Participacoes S.A.
- Logoplaste Group
- AptarGroup, Inc.
- CCL Industries Inc.
- Gerresheimer AG
- Graham Packaging Company, L.P.
- Comar, LLC
- ZARAPLAST S.A.
- Petropack S.A.
- EMUSA
- Megapack
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Food Delivery and Quick-Service Restaurants
- 4.2.2 Growth of Packaged Food and Beverage Consumption
- 4.2.3 E-Commerce and Quick-Commerce Fulfillment Demand
- 4.2.4 Conversion from Rigid to Flexible Single-Use Formats
- 4.2.5 Expansion of Recyclable Mono-Material Packaging
- 4.2.6 Regional Growth of Food, Agricultural, and Export Supply Chains
- 4.3 Market Restraints
- 4.3.1 Single-Use Plastic Restrictions and Extended Producer Responsibility Costs
- 4.3.2 Volatility in Petrochemical Resin Prices
- 4.3.3 Limited Food-Grade Recycled Resin Availability
- 4.3.4 Fragmented Collection Systems for Multilayer Packaging
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Bottles and Containers
- 5.1.2 Bags and Pouches
- 5.1.3 Trays, Cups, and Lids
- 5.1.4 Clamshells
- 5.1.5 Films and Wraps
- 5.1.6 Other Product Types
- 5.2 By Material Type
- 5.2.1 Polyethylene
- 5.2.2 Polypropylene
- 5.2.3 Polyethylene Terephthalate
- 5.2.4 Polystyrene and Expanded Polystyrene
- 5.2.5 Polylactic Acid
- 5.2.6 Other Material Types
- 5.3 By Packaging Format
- 5.3.1 Rigid Packaging
- 5.3.2 Flexible Packaging
- 5.3.3 Semi-Rigid Packaging
- 5.4 By Application
- 5.4.1 Food Packaging
- 5.4.2 Beverage Packaging
- 5.4.3 Personal Care Packaging
- 5.4.4 Pharmaceutical Packaging
- 5.4.5 Household and Institutional Packaging
- 5.4.6 Industrial and Agricultural Packaging
- 5.5 By End User
- 5.5.1 Foodservice and Quick-Service Restaurants
- 5.5.2 Retail and Supermarkets
- 5.5.3 E-Commerce and Delivery Platforms
- 5.5.4 Consumer Goods Manufacturers
- 5.5.5 Healthcare and Pharmaceutical Manufacturers
- 5.5.6 Personal Care and Cosmetics Manufacturers
- 5.6 By Geography
- 5.6.1 Brazil
- 5.6.2 Argentina
- 5.6.3 Colombia
- 5.6.4 Chile
- 5.6.5 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Berry Global Group, Inc.
- 6.4.3 Sealed Air Corporation
- 6.4.4 Mondi plc
- 6.4.5 Sonoco Products Company
- 6.4.6 Huhtamaki Oyj
- 6.4.7 ProAmpac Holdings Inc.
- 6.4.8 Constantia Flexibles Group GmbH
- 6.4.9 Coveris Management GmbH
- 6.4.10 Transcontinental Inc.
- 6.4.11 Winpak Ltd.
- 6.4.12 ALPLA Werke Alwin Lehner GmbH & Co KG
- 6.4.13 Plastipak Holdings, Inc.
- 6.4.14 Valgroup Participacoes S.A.
- 6.4.15 Logoplaste Group
- 6.4.16 AptarGroup, Inc.
- 6.4.17 CCL Industries Inc.
- 6.4.18 Gerresheimer AG
- 6.4.19 Graham Packaging Company, L.P.
- 6.4.20 Comar, LLC
- 6.4.21 ZARAPLAST S.A.
- 6.4.22 Petropack S.A.
- 6.4.23 EMUSA
- 6.4.24 Megapack
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 全球聚苯乙烯包裝市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 全球塑膠包裝市場
 聚苯乙烯包裝市場規模、佔有率和趨勢分析報告:按材料、包裝產品、應用、最終用途、地區和細分市場預測(2026-2033 年)
 2026年全球鬆散填充聚苯乙烯包裝材料市場報告2026年全球聚苯乙烯包裝市場報告
 全球一次性塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 2035 年前食品飲料塑膠包裝市場分析與預測:類型、產品類型、技術、應用、材料類型、製造流程、最終用戶、功能中東和非洲塑膠包裝市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)亞太地區塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)全球塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)