


 |
市場調查報告書
商品編碼
2124782
英國瓦楞紙板包裝:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)United Kingdom Corrugated Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
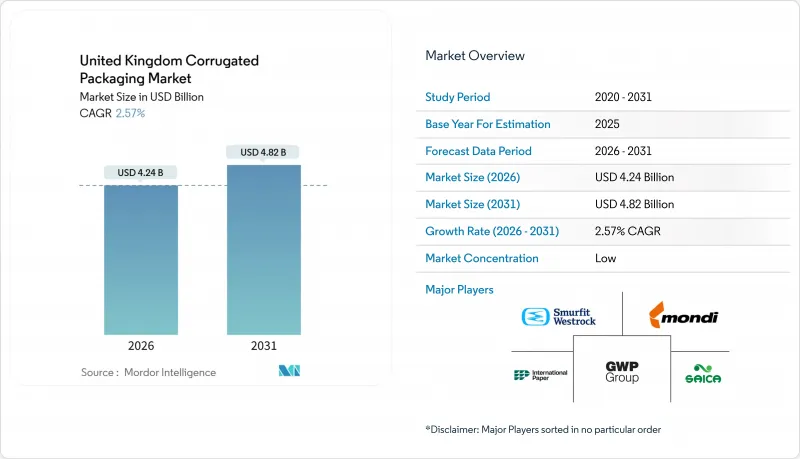
根據 Mordor Intelligence 預測,英國瓦楞紙板包裝市場規模預計將在 2026 年達到 42.4 億美元,到 2031 年達到 48.2 億美元,預測期內複合年成長率為 2.57%。
本報告按產品類型(開槽紙盒、伸縮式多片紙盒、托盤及其他)、紙板類型(單層、雙層、三層)、瓦楞型材(A、B、C、E、F及其他)、終端用戶行業(食品、飲料、醫藥及其他)和印刷技術(柔版印刷、數位印刷、膠版印刷及其他)進行細分。市場預測以美元計價。
英國瓦楞紙板包裝市場趨勢與洞察
電子商務小包裹量激增
到2024年,英國線上零售市場滲透率將達到總銷售額的27.8%,這將刺激對輕便的B型和F型瓦楞紙包裝的需求,這些包裝既能最大限度地減少體積重量費用,又能承受自動化分揀的負荷。品牌參與「自有貨櫃運輸」(Ships in Own Container)計劃,正在擴大免維護開槽紙箱的潛在客戶群,而可變數據和QR碼的數位印刷應用也在逐步增加。
偏好可回收紡織包裝
《2024年廢棄物分類條例》規定,大多數企業必須在2025年3月前將紙張和紙板分開回收,這將提高廢料包的純度,並使再生纖維的價格上漲約8-12%。生產者延伸責任制(EPR)費用造成了成本差距,有利於單一材料設計,促使品牌商用紙板替代品取代塑膠托盤。
再生紙價格和供應的波動
2023年,家庭用紙回收量較去年同期下降3.3%,至189.4萬噸。儘管回收率達74.3%,但原料供應仍緊張。到2025年初,包裝和回收憑證(PRN)的價格跌破每噸5英鎊,削弱了地方政府對回收紙(OCC)進行分類和處理的獎勵,迫使加工商對沖紙漿採購風險。
細分市場分析
預計到2025年,開槽紙箱將佔據42.43%的市場。這反映了其與高速組裝的兼容性,以及其在食品、飲料和工業運輸領域的廣泛應用。英國瓦楞紙包裝市場(包括托盤、折疊紙盒和紙板)預計將以3.66%的複合年成長率成長,這主要得益於人事費用對「即裝即用」展示品的需求,此類展示品可以降低店內人工成本並提高貨架可見度。 Tesco和Sainsbury's制定的關於易撕線和加固角柱的規範正在推動材料升級,而亞馬遜的「自有貨櫃出貨」標準則促使初級包裝也兼作運輸箱。此外,採用平版印刷和覆膜處理法的禮品和促銷包裝也帶來了需求,這些包裝有助於在競爭激烈的電商平台中脫穎而出。
品牌擁有者為了滿足單人家庭小批量包裝的需求,開發了數千種SKU,其中托盤和折疊紙盒特別適合快速數位印刷。雖然伸縮式和多片式紙箱在英國瓦楞紙包裝市場仍佔有一定佔有率,但重型設備出口商依賴這些深度可調的紙箱來運輸價值超過5萬英鎊(6.35萬美元)的精密設備。在預測期內,出版商預計微型瓦楞紙郵寄盒將廣泛應用,但開槽紙箱仍佔據相當大的市場佔有率,尤其是在自動化裝箱組裝每分鐘可處理超過60個紙箱的情況下。
到2025年,單層瓦楞紙板將佔據英國瓦楞紙板包裝市場38.32%的佔有率,這主要得益於其重量、成本和承載能力的均衡優勢。相較之下,三層瓦楞紙板的市佔率正以4.32%的複合年成長率成長,主要得益於汽車、航太和機械業的托運人逐漸放棄木箱包裝。 CorrBoard和VPK Packaging公司新增的產能擴大了BB和BC雙層瓦楞紙板的供應,這些紙板符合每公尺超過10kN的抗壓強度標準。雖然雙層瓦楞紙板在消費性電子產品領域仍佔據重要地位,但對輕質材料日益成長的需求正推動著許多應用領域轉向採用高性能內襯的最佳化型單層瓦楞紙板。
工業領域的托運人更傾向於使用三層瓦楞紙板包裝出口貨物,因為這些貨物在海運過程中可能面臨震動、潮濕和穿刺的風險。雖然在英國瓦楞紙板市場,三層瓦楞紙板的佔有率仍然低於單層瓦楞紙板,但其更高的單位收益和穩定的利潤率正吸引著加工商的注意。 CorrBoard公司對自動化堆疊技術的投資,也提振了高耐久性瓦楞紙板的中期市場前景。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務小包裹量激增
- 受英國法規影響,人們更傾向於使用可回收的紡織包裝。
- 透過減輕重量來減少物流排放
- 對加工食品和飲料品牌的需求不斷成長
- 零售業「現貨」紙板產品的擴張
- 受塑膠包裝稅影響,資本轉向瓦楞紙板生產線。
- 市場限制因素
- 再生紙(OCC)的價格和供應波動
- 易碎產品中柔軟性塑膠替代品的威脅
- 都市區對挨家挨戶收集混合紙製品的限制
- 能源價格波動給瓦楞紙板生產商的利潤率帶來了壓力。
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 帶插槽的盒子
- 望遠鏡多件套裝
- 托盤、文件夾、紙張
- 其他
- 依電路板類型
- 單層壁
- 雙層壁
- 三層壁
- 笛形輪廓
- 長笛
- 低音長笛
- C調長笛
- E 長笛
- F調長笛
- 其他笛型
- 按最終用戶行業分類
- 食物
- 飲料
- 製藥
- 個人護理和家居用品
- 產業
- 電子商務
- 電氣和電子設備
- 其他
- 透過印刷技術
- 柔版印刷
- 數位的
- 光刻
- 其他印刷技術
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Mondi Group
- Smurfit WestRock
- International Paper Company
- Saica Group SL
- GWP Group Limited
- The Box Factory Limited
- Cepac Limited
- Board24 Limited
- Rigid Containers Limited
- Boxes and Packaging(Oxford)Limited
- Kentpak Limited
- Keenpac UK Limited
- Atlas Packaging Limited
- Reedbut Group Limited
- Preston Board & Packaging Ltd
- Schumacher Packaging Ltd
- Kite Packaging Ltd
- CorrBoard UK Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom corrugated packaging market size stands at USD 4.24 billion in 2026 and is expected to reach USD 4.82 billion by 2031, reflecting a 2.57% CAGR over the forecast period.
This report is Segmented by Product Type (Slotted Box, Telescope/Multi-Piece Boxes, Trays, and More), Board Type (Single Wall, Double Wall, and Triple Wall), Flute Profile (A, B, C, E, F, and More), End-User Industry (Food, Beverages, Pharmaceuticals, and More) and Print Technology (Flexography, Digital, Lithography, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Corrugated Packaging Market Trends and Insights
Surge in E-Commerce Parcel Volumes
Online retail penetration touched 27.8% of total U.K. sales in 2024, stimulating demand for lightweight B- and F-flute mailers that withstand automated sortation forces while minimizing dimensional-weight charges. Brand participation in "Ships in Own Container" programs expands the addressable pool for frustration-free slotted boxes, supporting incremental adoption of digital printing for variable data and QR codes.
Preference for Recyclable Fiber-Based Packaging
The Separation of Waste Regulations 2024 mandates dedicated paper and card collection for most businesses by March 2025, lifting bale purity and boosting recovered-fiber prices by roughly 8-12%. Extended Producer Responsibility fees establish a cost gradient that favors mono-material designs, encouraging brands to substitute plastic trays with corrugated equivalents.
Volatility in Recovered Paper Prices and Supply
Household paper collection fell 3.3% year on year to 1.894 million t in 2023, compressing raw-material availability even as recycling rates reached 74.3%. Packaging Recovery Note prices dropped below GBP 5 per tonne in early 2025, undermining the incentive for local authorities to segregate OCC and forcing converters to hedge pulp inputs.
Other drivers and restraints analyzed in the detailed report include:
- Lightweighting Initiatives
- Rising Demand from Processed Food Brands
- Substitution Threat from Flexible Plastics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Slotted boxes represented 42.43% of market share in 2025, reflecting their compatibility with high-speed erecting lines and broad use across food, beverage, and industrial shipping. The United Kingdom corrugated packaging market size attached to trays, folders and sheets is projected to expand at a 3.66% CAGR, fueled by retailer mandates for shelf-ready presentation that trims in-store labor and boosts on-shelf visibility. Tesco and Sainsbury's specifications for perforated tear strips and reinforced corner posts reinforce material upgrades, and Amazon's ship-in-own-container standard pushes primary packs to double as shipping cases. Additional demand stems from gift and promotional formats that employ litho-laminated graphics to differentiate products in crowded e-commerce storefronts.
Brand owners chasing smaller pack counts for single-person households generate thousands of SKUs, making trays and folders ideal for short-run digital printing. The United Kingdom corrugated packaging market share enjoyed by telescope and multi-piece boxes remains modest, yet heavy-machinery exporters rely on these adjustable depth designs for delicate equipment valued at more than GBP 50,000 (USD 63,500) per shipment. Over the forecast horizon, publishers forecast micro-flute mailers to proliferate, yet slotted boxes retain scale where automated case erectors handle more than 60 cases per minute.
Single-wall board captured 38.32% of the United Kingdom corrugated packaging market share in 2025, balancing weight, cost, and stacking performance. In contrast, triple-wall constructions are gaining at a 4.32% CAGR as automotive, aerospace, and machinery shippers shift away from timber crates. CorrBoard and VPK Packaging's new capacity expands access to BB and BC double-wall flutes that meet edge-crush thresholds above 10 kN per meter. Double-wall variants remain relevant for household appliances, but lightweighting is pushing many applications toward optimized single-wall grades with high-performance liners.
Industrial shippers prefer triple-wall for export cargo that can face vibration, humidity, and puncture hazards during ocean transit. The United Kingdom corrugated packaging market's triple-wall volume remains smaller than single-wall volumes, yet its higher unit revenue and stable margins drive converter interest. Investments in automated palletization at CorrBoard reinforce the medium-term outlook for heavy-duty board.
Complete Report Scope:
- By Product Type
- Slotted Box
- Telescope/Multi-Piece Boxes
- Trays, Folder and Sheets
- Other Product Types
- By Board Type
- Single Wall
- Double Wall
- Triple Wall
- By Flute Profile
- A Flute
- B Flute
- C Flute
- E Flute
- F Flute
- Other Flute Profile
- By End-user Industry
- Food
- Beverages
- Pharmaceuticals
- Personal Care and Household
- Industrial
- E-commerce
- Electrical and Electronics
- Other End-user Industries
- By Print Technology
- Flexography
- Digital
- Lithography
- Other Print Technology
List of Companies Covered in this Report:
- Mondi Group
- Smurfit WestRock
- International Paper Company
- Saica Group S.L.
- GWP Group Limited
- The Box Factory Limited
- Cepac Limited
- Board24 Limited
- Rigid Containers Limited
- Boxes and Packaging (Oxford) Limited
- Kentpak Limited
- Keenpac UK Limited
- Atlas Packaging Limited
- Reedbut Group Limited
- Preston Board & Packaging Ltd
- Schumacher Packaging Ltd
- Kite Packaging Ltd
- CorrBoard UK Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge In E-Commerce Parcel Volumes
- 4.2.2 Preference For Recyclable Fibre-Based Packaging Amid UK Regulations
- 4.2.3 Lightweighting Initiatives Lowering Logistics Emissions
- 4.2.4 Rising Demand From Processed Food And Beverage Brands
- 4.2.5 Expansion Of Shelf-Ready Corrugated Formats In Retail
- 4.2.6 Plastic Packaging Tax Redirecting Capital Toward Corrugated Lines
- 4.3 Market Restraints
- 4.3.1 Volatility In Recovered Paper (OCC) Prices And Supply
- 4.3.2 Substitution Threat From Flexible Plastics In Fragile Goods
- 4.3.3 Urban Curbside Collection Limits For Mixed Paper Streams
- 4.3.4 Energy-Price Fluctuations Squeezing Corrugator Margins
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Slotted Box
- 5.1.2 Telescope/Multi-Piece Boxes
- 5.1.3 Trays, Folder and Sheets
- 5.1.4 Other Product Types
- 5.2 By Board Type
- 5.2.1 Single Wall
- 5.2.2 Double Wall
- 5.2.3 Triple Wall
- 5.3 By Flute Profile
- 5.3.1 A Flute
- 5.3.2 B Flute
- 5.3.3 C Flute
- 5.3.4 E Flute
- 5.3.5 F Flute
- 5.3.6 Other Flute Profile
- 5.4 By End-user Industry
- 5.4.1 Food
- 5.4.2 Beverages
- 5.4.3 Pharmaceuticals
- 5.4.4 Personal Care and Household
- 5.4.5 Industrial
- 5.4.6 E-commerce
- 5.4.7 Electrical and Electronics
- 5.4.8 Other End-user Industries
- 5.5 By Print Technology
- 5.5.1 Flexography
- 5.5.2 Digital
- 5.5.3 Lithography
- 5.5.4 Other Print Technology
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Mondi Group
- 6.4.2 Smurfit WestRock
- 6.4.3 International Paper Company
- 6.4.4 Saica Group S.L.
- 6.4.5 GWP Group Limited
- 6.4.6 The Box Factory Limited
- 6.4.7 Cepac Limited
- 6.4.8 Board24 Limited
- 6.4.9 Rigid Containers Limited
- 6.4.10 Boxes and Packaging (Oxford) Limited
- 6.4.11 Kentpak Limited
- 6.4.12 Keenpac UK Limited
- 6.4.13 Atlas Packaging Limited
- 6.4.14 Reedbut Group Limited
- 6.4.15 Preston Board & Packaging Ltd
- 6.4.16 Schumacher Packaging Ltd
- 6.4.17 Kite Packaging Ltd
- 6.4.18 CorrBoard UK Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 北美瓦楞紙和折疊式紙盒包裝:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)中東瓦楞紙包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)中東和非洲瓦楞紙包裝市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)北美瓦楞紙包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 瓦楞紙市場規模、佔有率和成長分析:按產品類型、紙張重量、應用、最終用途產業、包裝類型和地區分類 - 產業預測,2026-2033年
 瓦楞紙板配件市場規模、佔有率和成長分析:按產品類型、材料、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 瓦楞紙板包裝軟體市場-2026-2032年全球市場預測
 2026-2030年全球瓦楞紙包裝軟體市場
 紙盒包裝市場預測至2034年-全球分析(按紙板類型、材料、印刷和表面處理、封裝類型、應用、最終用途、分銷管道和地區分類)南美瓦楞紙包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)