


 |
市場調查報告書
商品編碼
2124326
歐洲電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Electric Bus - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
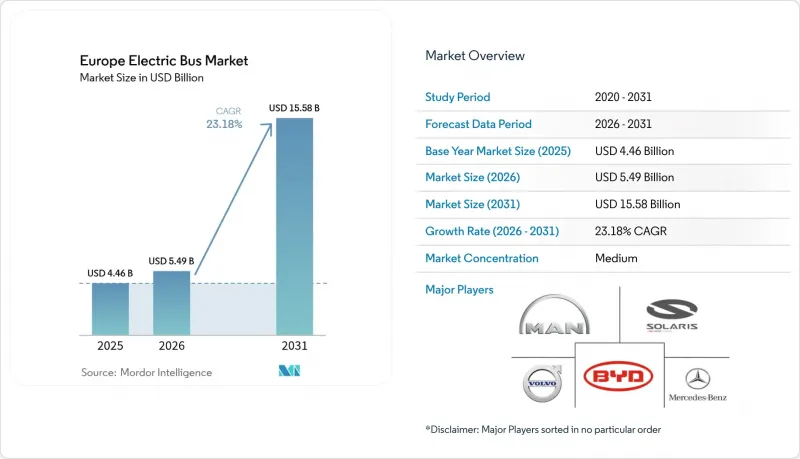
據 Mordor Intelligence 稱,2025 年歐洲電動巴士市場價值 44.6 億美元,預計到 2031 年將達到 155.8 億美元,而 2026 年為 54.9 億美元,預測期(2026-2031 年)複合年成長率為 23.18%。
本報告按動力類型(純電動公車 (BEB)、插電式混合動力公車 (PHEB) 及其他)、電池化學成分(磷酸鋰鐵(LFP)、鎳氫電池 (NiMH) 及其他)、公車長度(9 公尺以下、9-14 公尺(標準)、其他)、用戶類型、應用領域和國家/地區進行細分。市場預測以美元 (USD) 為單位。
歐洲電動巴士市場趨勢與洞察
從 2026 年起,總擁有成本 (TCO) 將低於柴油車。
2024年,由於磷酸鋰鐵電池(LFP)的廣泛應用,電池價格大幅下降,電池組成本較鎳基複合材料(NMC)降低了約20%。考慮到維護成本的降低以及歐洲排放標準ETS-2的碳排放,預計2025年購買的電動公車在投入使用四年後,其總擁有成本(TCO)將與柴油車相當。梅賽德斯-奔馳eCitaro在柏林和烏得勒支的初步部署表明,由於動力傳動系統易損件減少,年度維護成本降低了30%以上。目前,車輛業者正在推廣三班倒的營運模式,將電力利用率提升至96%以上,並加快了投資回報。這些經濟優勢增強了私部門的信心,也解釋了2025年專業電動公車業者的創業融資成長18%的原因。
歐盟清潔車輛指令的最後期限
清潔車輛指令規定的具有約束力的採購目標正在降低城市交通的不確定性,並促進將車輛供應與充電解決方案捆綁在一起的多年期合約競標。德國的《清潔車輛採購法》(Saubere-Fahrzeuge-Beschaffungs-Gesetz)將2026年至2030年間清潔車輛的強制比例提高到65%,其中一半必須是零排放車輛。法國和西班牙正在實施類似的立法,允許製造商透過將需求整合到可預測的大批量訂單中來最佳化生產線並降低單位成本。此外,各國可以柔軟性整合不同訂購機構的採購目標,這提高了購買力,並使即使是小規模的城市也能獲得數量折扣。因此,到2024年,歐盟超過49%的新城市公車已經是零排放車輛,預計到2027年這一比例將超過70%。
老式火車站電網連接瓶頸
由於電力公司在核准流程上遭遇長期延誤,柴油車專用設施的變電站和線路升級改造工程仍落後。米蘭和慕尼黑的營運商報告稱,他們等待2兆瓦併網的等待時間已超過18個月,迫使他們依賴行動充電樁,而行動充電樁必須限制夜間充電。歐盟委員會的「電網行動計畫」預測,到2030年,電力需求將增加60%,但許多城市中心幾乎沒有剩餘的電纜容量來應對集中充電的需求。這些延誤導致合約生效日期推遲,車庫維修預算膨脹,儘管訂單積壓充足,但短期累積訂單仍被推遲。
細分市場分析
2025年,在監管政策和成熟的供應鏈縮小價格差距的推動下,純電動公車技術佔據了歐洲電動公車市場81.95%的佔有率。強力的政策支持、簡化的驅動系統以及電池成本的下降預計將推動該細分市場在2031年實現24.10%的複合年成長率。燃料電池公車仍然是日行駛里程超過400公里線路的戰略選擇,但加氫站的缺乏阻礙了其廣泛應用。插電式混合動力公車目前主要在過渡合約下運營,因為其車庫維修尚未完成。
製造商正在其所有電動和氫燃料電池公車產品線中實現電力電子和溫度控管系統的標準化,從而降低了研發成本。索拉里斯公司在履行博洛尼亞市130輛氫燃料電池公車的訂單的同時,也保持著純電動公車的量產,確保能夠靈活應對不斷變化的政策方向。由於市政當局的大量補貼旨在實現“零排放”,而非特定技術,因此車輛管理者出於短期合規和成本穩定的考慮,繼續選擇純電動公車,預計這將鞏固主導地位。
預計到2025年,磷酸鋰鐵(LFP)電池組將佔據歐洲電動巴士市場48.75%的佔有率,並引領該品類以24.60%的複合年成長率(CAGR)成長,到2031年成長速度將達到最快。這主要得益於其成本優勢和卓越的熱穩定性,而這些優勢恰好符合營運商的安全和經濟效益考量。該電池的循環壽命超過4000次充放電循環,使營運商能夠規劃長達12年的資產使用壽命,無需中途更換電池,從而降低全生命週期資本支出(CAPEX)。雷諾選擇從寧德時代(CATL)的匈牙利工廠採購LFP模組,體現了OEM廠商對歐洲供應鏈穩定性的信心。鎳錳鈷酸鋰(NMC)仍然是需要高能量密度鉸接式巴士的最佳電池成分,但正面臨鈷價飆升和ESG(環境、社會和治理)審查帶來的挑戰。
受低纖維鉀(LFP)電池技術推動,歐洲電動巴士市場規模不斷擴大,歐盟電池法規中的回收成分配額標準也促進了這一成長。使用鐵基正極材料更容易達到這些標準。赫爾辛基和維也納的營運商報告稱,與使用早期新型金屬電容器(NMC)技術的車輛相比,採用LFP技術的車輛電池保固索賠有所減少,這表明技術風險降低。雖然在預測期內,鈉離子電池的研究可能會帶來成本較低的化學成分,但在2030年之前實現商業規模部署仍被認為難度較大,預計LFP電池仍將是主流技術。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟清潔車輛指令合規期限
- 從 2026 年起,總擁有成本將低於柴油車。
- 國家零排放公共採購配額
- 透過現場電池儲能來平衡高峰需求電價。
- 透過電池即服務 (BaaS) 合約降低資本投資風險
- 根據歐盟碳排放交易體系2 (ETS-2),歐盟碳定價的提高將增加柴油公車的營運成本,從而加速向電動公車的轉型。
- 市場限制因素
- 老式火車站電網連接瓶頸
- 第一代電動巴士的殘值存在很大的不確定性
- 歐盟可能對中國製造的電動公車徵收關稅,這可能會推高系統成本。
- 持證高壓維修技術人員短缺
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 依推進類型
- 電池驅動電動巴士(BEB)
- 插電式混合動力電動巴士(PHEB)
- 燃料電池電動巴士(FCEB)
- 電池化學成分
- 磷酸鋰鐵(LFP)
- 鋰鎳錳鈷氧化物(NMC)
- 鎳氫電池(NiMH)
- 其他(鈉離子,所有固體)
- 按巴士長度
- 小於9米
- 9-14公尺(標準)
- 超過14公尺(鉸接式巴士、雙層巴士)
- 依消費者類型
- 政府和地方政府交通
- 私家車營運商
- 透過使用
- 城市大眾運輸
- 城際/區域內
- 機場和接駁車服務
- 國家
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 挪威
- 波蘭
- 瑞典
- 芬蘭
- 比利時
- 瑞士
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Solaris Bus & Coach sp. z oo
- MAN Truck & Bus
- Mercedes-Benz Group AG
- Volvo Buses
- BYD Auto Co., Ltd
- VDL Bus & Coach
- Ebusco
- IVECO Group
- Scania
- Otokar
- Van Hool
- Yutong Europe
- Irizar e-mobility
- Wrightbus
- Karsan
- CaetanoBus
- Temsa
- Bozankaya
- Switch Mobility
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe electric bus market size was valued at USD 4.46 billion in 2025 and estimated to grow from USD 5.49 billion in 2026 to reach USD 15.58 billion by 2031, at a CAGR of 23.18% during the forecast period (2026-2031).
This report is Segmented by Propulsion Type (Battery Electric Bus (BEB), Plug-In Hybrid Electric Bus (PHEB), and More), Battery Chemistry (Lithium-Iron-Phosphate (LFP), Nickel-Metal Hydride (NiMH), and More), Bus Length (Less Than 9 M, 9-14 M (Standard), and More), Consumer Type, Application and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Electric Bus Market Trends and Insights
Falling Total Cost of Ownership Versus Diesel After 2026
Battery prices fell sharply in 2024 on wider LFP adoption, cutting pack costs by about 20% compared with NMC. When maintenance savings and ETS-2 carbon charges are added, an electric bus purchased in 2025 is projected to reach TCO parity with a diesel unit within four years of service. Early deployments of the Mercedes-Benz eCitaro in Berlin and Utrecht reveal annual maintenance savings exceeding 30% thanks to fewer drivetrain wear parts. Fleet operators are now standardizing three-shift duty cycles that push electric utilization above 96%, which accelerates payback. Such economics underpin private-sector confidence and explain why venture funding for specialized e-bus operators climbed 18% in 2025 .
EU Clean-Vehicles Directive Deadlines
Binding procurement targets under the Clean-Vehicles Directive remove uncertainty for city transport agencies, prompting multi-year tenders that bundle vehicle supply and charging solutions. Germany's Saubere-Fahrzeuge-Beschaffungs-Gesetz lifts required clean-vehicle purchases to 65% for 2026-2030, half of which must be zero-emission. Similar transpositions in France and Spain are clustering demand into large, predictable tranches that let manufacturers optimize production lines and reduce per-unit costs. National flexibility to pool targets across contracting authorities also raises purchasing power, helping smaller cities gain volume discounts. As a result, more than 49% of new EU city buses were already zero-emission in 2024, a share expected to exceed 70% by 2027 .
Grid-Connection Bottlenecks at Legacy Depots
Upgrading substations and cabling at sites built for diesel fleets remains slow because utilities face long permitting backlogs. Operators in Milan and Munich report waits of 18 months or more for 2-MW connections, forcing interim reliance on mobile chargers that limit overnight energy intake. The European Commission's Action Plan for Grids identifies a 60% increase in electricity demand by 2030, yet many city centers have little spare cabling capacity to handle clustered charging. Delays can push back contract start dates and inflate depot conversion budgets, cooling near-term delivery schedules despite healthy order books.
Other drivers and restraints analyzed in the detailed report include:
- National Zero-Emission Public-Procurement Quotas
- On-Site Depot Battery-Storage Shaving Peak-Demand Charges
- Residual-Value Uncertainty for First-Generation E-Buses
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Battery-electric technology controlled 81.95% of the Europe electric bus market in 2025, driven by regulatory mandates and the maturing supply chain that reduce purchase price gaps. Strong policy backing, simpler drivetrains, and falling battery costs support a 24.10% CAGR for the segment through 2031. Fuel-cell buses remain a strategic hedge for routes exceeding 400 km daily, but scarce hydrogen refueling sites restrict widespread adoption. Plug-in hybrids now serve mostly in transitional contracts where depot upgrades are incomplete.
Manufacturers are standardizing power electronics and thermal-management systems across their electric and hydrogen lines, which lowers development expense. Solaris is executing a 130-unit hydrogen order for Bologna while maintaining battery-electric production at volume, ensuring flexibility if policy signals shift. Because heavy municipal subsidies target zero tailpipe emissions rather than a specific technology, fleet managers continue to pick battery-electric options for near-term compliance and cost reliability, cementing segment leadership for the next five years.
Lithium-iron-phosphate packs captured 48.75% Europe electric bus market share in 2025 and lead the category with the fastest projected expansion of 24.60% CAGR through 2031, driven by cost advantages and superior thermal stability that resonate with operator safety and economic priorities. The chemistry's cycle life of 4,000+ charge events helps operators plan for 12-year asset lives without mid-life battery swaps, cutting lifetime capex. Renault's decision to source LFP modules from CATL's Hungarian plant illustrates OEM confidence in European supply security. Lithium nickel manganese cobalt oxide remains the chemistry of choice for articulated buses that need high energy density, but rising cobalt prices and ESG scrutiny create headwinds.
Europe electric bus market size gains tied to LFP are reinforced by EU Battery Regulation recycled-content quotas that are easier to meet with iron-based cathodes. Operators in Helsinki and Vienna report battery warranty claims trending lower than early NMC fleets, signaling reduced technical risk. Over the forecast horizon, sodium-ion research may add yet another low-cost chemistry, but commercial scale is unlikely before 2030, leaving LFP dominant.
Complete Report Scope:
- By Propulsion Type
- Battery Electric Bus (BEB)
- Plug-in Hybrid Electric Bus (PHEB)
- Fuel-Cell Electric Bus (FCEB)
- By Battery Chemistry
- Lithium-Iron-Phosphate (LFP)
- Lithium Nickel Manganese Cobalt Oxide (NMC)
- Nickel-Metal Hydride (NiMH)
- Others (Sodium-ion, Solid-state)
- By Bus Length
- Less than 9 m
- 9-14 m (Standard)
- Above 14 m (Articulated/Double-decker)
- By Consumer Type
- Government / Municipal Transit Agencies
- Private Fleet Operators
- By Application
- Intra-city Urban Transit
- Inter-city & Regional
- Airport & Shuttle Services
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Norway
- Poland
- Sweden
- Finland
- Belgium
- Switzerland
- Rest of Europe
List of Companies Covered in this Report:
- Solaris Bus & Coach sp. z o.o.
- MAN Truck & Bus
- Mercedes-Benz Group AG
- Volvo Buses
- BYD Auto Co., Ltd
- VDL Bus & Coach
- Ebusco
- IVECO Group
- Scania
- Otokar
- Van Hool
- Yutong Europe
- Irizar e-mobility
- Wrightbus
- Karsan
- CaetanoBus
- Temsa
- Bozankaya
- Switch Mobility
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Clean-Vehicles Directive compliance deadlines
- 4.2.2 Falling total-cost-of-ownership versus diesel after 2026
- 4.2.3 National zero-emission public-procurement quotas
- 4.2.4 On-site depot battery-storage shaving peak-demand charges
- 4.2.5 Battery-as-a-Service contracts lowering capex risk
- 4.2.6 Escalating EU carbon-pricing under ETS-2 boosts diesel operating costs, accelerating e-bus switch
- 4.3 Market Restraints
- 4.3.1 Grid-connection bottlenecks at legacy depots
- 4.3.2 High residual-value uncertainty for first-generation e-buses
- 4.3.3 Potential EU tariffs on Chinese e-buses could raise system costs
- 4.3.4 Shortage of certified high-voltage maintenance technicians
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Propulsion Type
- 5.1.1 Battery Electric Bus (BEB)
- 5.1.2 Plug-in Hybrid Electric Bus (PHEB)
- 5.1.3 Fuel-Cell Electric Bus (FCEB)
- 5.2 By Battery Chemistry
- 5.2.1 Lithium-Iron-Phosphate (LFP)
- 5.2.2 Lithium Nickel Manganese Cobalt Oxide (NMC)
- 5.2.3 Nickel-Metal Hydride (NiMH)
- 5.2.4 Others (Sodium-ion, Solid-state)
- 5.3 By Bus Length
- 5.3.1 Less than 9 m
- 5.3.2 9-14 m (Standard)
- 5.3.3 Above 14 m (Articulated/Double-decker)
- 5.4 By Consumer Type
- 5.4.1 Government / Municipal Transit Agencies
- 5.4.2 Private Fleet Operators
- 5.5 By Application
- 5.5.1 Intra-city Urban Transit
- 5.5.2 Inter-city & Regional
- 5.5.3 Airport & Shuttle Services
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Netherlands
- 5.6.7 Norway
- 5.6.8 Poland
- 5.6.9 Sweden
- 5.6.10 Finland
- 5.6.11 Belgium
- 5.6.12 Switzerland
- 5.6.13 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Solaris Bus & Coach sp. z o.o.
- 6.4.2 MAN Truck & Bus
- 6.4.3 Mercedes-Benz Group AG
- 6.4.4 Volvo Buses
- 6.4.5 BYD Auto Co., Ltd
- 6.4.6 VDL Bus & Coach
- 6.4.7 Ebusco
- 6.4.8 IVECO Group
- 6.4.9 Scania
- 6.4.10 Otokar
- 6.4.11 Van Hool
- 6.4.12 Yutong Europe
- 6.4.13 Irizar e-mobility
- 6.4.14 Wrightbus
- 6.4.15 Karsan
- 6.4.16 CaetanoBus
- 6.4.17 Temsa
- 6.4.18 Bozankaya
- 6.4.19 Switch Mobility
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 2034年電動巴士和公共交通電氣化市場預測-全球分析(按推進方式、巴士類型、電池類型、馬達類型、充電方式、充電地點、充電基礎設施、應用、最終用戶和地區分類)
 全球電動巴士市場:按應用、電池容量、電池類型、組件、消費者、動力系統架構、車輛總重、巴士長度、自動駕駛水平、功率輸出、推進系統、續航里程、座位數和地區分類-預測至2035年
 燃料電池電動巴士全球市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 燃料電池電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)亞太地區電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)非洲電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 公共運輸電氣化市場:按組件、應用、電池類型、全球價值鏈 (GVC)、推進系統、國家和地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 電動微型巴士市場:2026-2032年全球市場預測(按驅動系統、座位數、續航里程、電池容量、應用和最終用戶分類)電動校車市場:按驅動系統、車身長度、電池容量、校車類型、充電方式和最終用戶分類-2026-2032年全球市場預測電動巴士市場:2026-2032年全球市場預測(按推進系統、電池類型、底盤類型、座位數、續航里程、應用和最終用戶分類)