

 |
市場調查報告書
商品編碼
2138094
全球電動巴士市場:按應用、電池容量、電池類型、組件、消費者、動力系統架構、車輛總重、巴士長度、自動駕駛水平、功率輸出、推進系統、續航里程、座位數和地區分類-預測至2035年Electric Buses Market by Propulsion (BEV, FCEV), Battery (LFP, NMC, NCA), Length (<9, 9-14, >14m), Battery Capacity (<=400, >400kWh), Application, Seating Capacity, Range, Power Output, Component, Consumer, and Region - Global Forecast to 2035 |
||||||

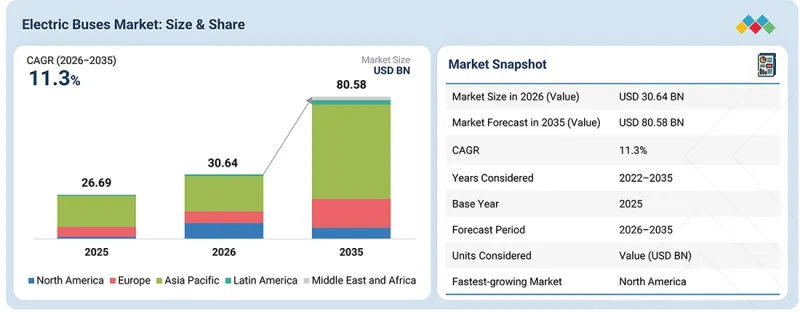
全球電動巴士市場預計將從 2026 年的 306.4 億美元成長到 2035 年的 805.8 億美元,複合年成長率為 11.3%。
除了傳統的城市公共交通外,市場正在擴大,涵蓋企業員工通勤、企業出行、機場接送、旅遊、城際交通、校車和本地線路,從而對續航里程更長、日運轉率更高的電動公車產生了新的需求。
| 調查範圍 | |
|---|---|
| 調查期 | 2022-2035 |
| 基準年 | 2025 |
| 預測期 | 2026-2033 |
| 目標單元 | 10億美元 |
| 部分 | 依應用、電池容量、電池類型、組件、消費者、動力傳動系統架構、車輛總重、巴士長度、自主等級、功率輸出、推進系統、續航里程、座位容量和地區分類。 |
| 目標區域 | 亞太地區、北美地區、歐洲 |
電池容量的提升、快速充電、溫度控管以及車輛效率的提高,使得營運商能夠將電動公車部署到日益繁忙的線路上。同時,車主們不僅更關注車輛的初始購買價格,也更重視總擁有成本、車輛運轉率和能源成本。這為長續航里程的純電動車(BEV)和燃料電池電動車(FCEV)創造了需求,尤其是在充電時間和線路柔軟性至關重要的城際和長途線路上。
據估計,到 2026 年,政府部門對電動公車的需求量最大。
預計到2026年,政府部門將成為電動公車需求的主要驅動力,因為公共交通在都市區公車採購中佔據相當大的佔有率。在許多國家,國有或地方政府運輸公司通常是公車的最大單一買家。政府機構擁有集中採購、基於站點的充電基礎設施和可預測的路線等優勢,與分散的私人車輛運營相比,這些優勢使得大規模電氣化更具可行性。結構化的採購模式、強制性車輛更換以及官民合作關係進一步強化了這一優勢,從而降低了傳統上與電動公車部署相關的前期成本和財務風險。此外,政府支持的資金籌措機制、補貼計畫和專案採購項目進一步降低了公共交通的前期成本門檻。此外,一些國家製定了長期電氣化藍圖,規定公共交通在特定日期之後購買的新電動公車必須實現零排放,從而形成政策支持且永續的需求前景。因此,集中的購買力、支持性的政策框架和結構性的財政支持預計將在整個預測期內繼續推動電動巴士市場的需求,其中政府和公共交通部門是主要的需求促進因素。
預計在預測期內,電池容量超過 400 kWh 的細分市場將以更快的速度成長。
容量超過 400 kWh 的電池組市場正以更快的速度成長,這得益於電池技術的持續發展、電池成本的下降以及充電基礎設施的改善。各大製造商正擴大採用大容量電池系統來延長公車的續航里程,同時又不會顯著影響載客量或車輛性能。國際能源總署 (IEA) 的數據顯示,電池經濟性也不斷提升,預計到 2025 年,全球電池平均價格將比 2024 年下降 8%。這凸顯了大容量電池組的商業性可行性。同時,高功率充電技術和車庫基礎設施的進步正在緩解大容量電池帶來的營運劣勢。此外,容量超過 400 kWh 的電池不僅適用於長途城市線路,也適用於郊區、鄉村、城際、機場、員工通勤以及其他高利用率的應用情境。根據國際能源總署(IEA)的數據,到2025年,市售電動公車的平均續航里程將達到360公里,比2020年成長約15%。同時,業界正積極研發續航里程更長的車款。隨著電動公車在傳統城市交通之外的領域日益普及,這將推動市場轉向更高容量規格。私人車隊營運商和長途線路對電動公車的需求不斷成長,預計將進一步加速對電池容量超過400千瓦時的公車的需求。
北美是電動巴士市場成長最快的地區。
在北美,儘管預計2025年電動巴士市場將出現暫時性放緩,但其長期成長潛力依然強勁。美國零排放巴士新註冊量從2024年的3911輛下降至2025年的2626輛,降幅達25.9%,零排放巴士在新註冊巴士的佔比也從7.0%下降至4.4%。然而,這一降幅反映的是採購速度放緩和政策不確定性,而非電氣化進程的結構性轉變。預計北美電動巴士市場在2029年之前將保持相對停滯狀態,主要原因是聯邦政府對零排放巴士的資助、採購優先事項以及電動巴士經濟效益的不確定性。此外,對進口巴士、電池、鋼鐵、鋁和其他零件徵收的新關稅推高了車輛成本,導致運輸公司推遲或重新考慮採購計劃。因此,該預測調整了純電動車(BEV)成長放緩的預期,而非假設其能迅速恢復到先前的成長軌跡。預計2029年後,隨著老舊公共交通和校車更換需求增加、各州層級的法規持續推動電氣化、國內產能擴大以及電池成本改善,純電動車市場將出現復甦。然而,由於氫基礎設施不足、車輛和燃料成本飆升、未來訂單減少以及該地區原始設備製造商(OEM)供給能力有限,燃料電池電動車(FCEV)預計將出現更為劇烈的下滑。在大規模的更換需求和各州層級的電氣化計畫(尤其是在加州和其他專注於零排放車輛(ZEV)的州)的支撐下,校車預計仍將是最大的應用領域。普通公車線路的投放量可能會呈現更為緩慢的復甦。包括NFI/New Flyer、Gillig、Blue Bird、Nova Bus/Volvo、比亞迪和REV集團在內的領先企業正透過擴大國內產能、維持豐富的動力系統產品組合、加強與各州客戶的關係以及優先發展資金籌措前景更明朗的市場來應對這一挑戰。總體而言,北美市場預計將經歷由政策而非結構性變革驅動的暫時停滯。從2029年起,純電動車預計將逐步復甦,而燃料電池電動車的普及率預計將繼續下降。
電動客車市場的主要製造商包括比亞迪股份有限公司(中國)、宇通客車(中國)、廈門金龍客車(中國)、中車股份有限公司(中國)、浙江格利控股集團(中國)、NFI集團(加拿大)、沃爾沃集團(瑞典)、索拉里斯客車有限公司(波蘭)和戴姆勒卡車股份公司(德國)。這些公司已採取新產品開發和供應合約策略來擴大其在電動客車市場的佔有率。
調查範圍:
本研究按推進系統(純電動車 (BEV)、燃料電池電動車 (FCEV))、續航里程(低於 300 英里、高於 300 英里)、車身長度(低於 9 公尺、9-14 公尺、高於 14 公尺)、消費者(私人、政府)、應用程式(線路公車、長途巴士、校車、其他 400 千瓦時低於 400 千瓦時)千瓦時)、組件(馬達、電池、燃料電池堆、電池管理系統、電池冷卻系統、直流-直流轉換器、逆變器、交流/直流充電器、電動車連接器)、自動駕駛等級(半自動駕駛、完全自動駕駛)、功率輸出(低於 250 千瓦、高於 250 千瓦)、座位數(低於 400 個座位數(低於 70 個座位) 10 噸、10-20 噸、高於 20 噸)和地區(亞太地區、北美、中東和非洲 [MEA]、歐洲、拉丁美洲)對電動公車市場進行細分。本報告對電動巴士市場生態系統中的新興創業公司和中小企業進行了競爭分析。
本報告詳細介紹了影響電動巴士市場成長的關鍵因素。透過對主要產業參與者的深入分析,我們得以了解每家公司的業務概況、產品、關鍵策略、協議、合作關係、產品發布、併購、微觀經濟指標以及電動巴士市場的最新發展動態。
購買本報告的主要好處:
本報告為市場領導者及新參與企業提供電動巴士市場整體及各細分市場最精準的收入預測。報告內容涵蓋全面的市場佔有率分析、供應鏈分析、零件製造商的詳細名單及相關信息,以及競爭格局分析。此外,報告還有助於相關人員了解市場趨勢,並提供有關關鍵市場促進因素、限制因素、挑戰和機會的資訊。
本報告深入分析了以下幾點:
- 本報告深入分析了關鍵促進因素(從車輛採購轉向路線經濟性最佳化,以及平台模組化以實現多路線電動公車的規模化)、阻礙因素(CNG 和生質燃料電動巴士普及緩慢)、機遇(針對特定商用車的電池更換解決方案,以及電動巴士、車庫和能源解決方案的整合)和挑戰(高功率駕駛在持續時間下運作里程數以及在持續性停電下行駛時保持極端的耐久性空氣速度。
- 產品開發/創新:深入了解電動巴士市場的未來技術、研發活動以及產品/服務發布。
- 市場發展:盈利市場的全面資訊(本報告分析了各個地區的電動巴士市場。)
- 市場多元化:全面介紹電動巴士市場的新產品和服務、未開發的地區、近期趨勢和投資情況。
- 競爭分析:對電動巴士市場主要參與者的市場佔有率、成長策略和服務產品進行詳細評估,包括比亞迪股份有限公司(中國)、宇通汽車(中國)、廈門金龍客車(中國)、中車股份有限公司(中國)和浙江吉利控股集團(中國)。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 大型公司的策略舉措
第5章 產業趨勢
- 宏觀經濟展望
- 供應鏈分析
- 生態系分析
- 電動巴士生態系統
- 價格分析
- 2026年至2028年主要會議及活動
- 貿易分析
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 總擁有成本
- 2025-2024年歐洲註冊電動巴士數量
- 材料清單分析
- OEM分析
- 電動巴士驅動電機供應商(依OEM廠商、地區、2026年預測)
- 電動巴士電池供應商(依OEM廠商、地區、2026年預測)
第6章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
- 市場盈利
第7章 監理情勢
- 監管機構、政府機構和其他組織
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 區域監管機構、政府機構和其他組織
第8章 產業趨勢:技術進步、專利、創新與未來策略應用
- 專利分析
第9章:按應用分類的電動巴士市場
- 城市公車/路線公車
- 教練
- 校車
- 其他用途
- 主要行業趨勢
第10章:電動公車市場(以電池容量分類)
- 小於400度
- 400度或以上
- 主要行業趨勢
第11章:電動巴士市場(以電池類型分類)
- NMC電池
- 磷酸鋰電池
- NCA電池
- 其他
- 主要行業趨勢
第12章:電動巴士市場(按零件分類)
- 引擎
- 電池
- 燃料電池堆
- 電池管理系統
- 電池冷卻系統
- 直流-直流轉換器
- 逆變器
- 交流/直流充電器
- 電動汽車連接器
- 主要行業趨勢
第13章:電動巴士市場(依消費者分類)
- 私人的
- 民眾
- 主要行業趨勢
第14章:電動巴士市場(依動力系統架構分類)
- 中央馬達系統
- 整合式電力驅動橋
- 輪轂/輪內馬達
- 主要行業趨勢
第15章:電動巴士市場(以車輛總重計)
- 不到10噸
- 10-20噸
- 超過20噸
- 主要行業趨勢
第16章:電動巴士市場(以巴士長度分類)
- 小於9米
- 9-14米
- 超過14米
- 主要行業趨勢
第17章:電動巴士市場(依自動駕駛等級分類)
- 半自動
- 自動的
- 主要行業趨勢
第18章:電動公車市場(依功率輸出)
- 小於250千瓦
- 250度或以上
- 關鍵見解
第19章:電動公車市場(依推進系統分類)
- 電池驅動電動巴士(BEV)
- 燃料電池電動巴士(FCEV)
- 主要行業趨勢
第20章:電動巴士市場(依續航里程分類)
- 不到300英里
- 超過300英里
- 關鍵見解
第21章:電動巴士市場(依座位容量分類)
- 最多40個座位
- 40-70個座位
- 超過70個座位
- 主要行業趨勢
第22章:電動巴士市場(依地區分類)
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 新加坡
- 印尼
- 澳洲
- 歐洲
- 法國
- 德國
- 西班牙
- 義大利
- 挪威
- 瑞典
- 丹麥
- 荷蘭
- 比利時
- 英國
- 芬蘭
- 波蘭
- 北美洲
- 美國
- 加拿大
- 拉丁美洲
- 阿根廷
- 巴西
- 智利
- 墨西哥
- 哥倫比亞
- 中東和非洲
- 南非
- 阿拉伯聯合大公國
- 卡達
第23章 競爭情勢
- 概述
- 主要參與企業的策略/優勢
- 收入分析
- 2025年電動巴士市場佔有率分析
- 公司評估
- 財務指標
- 品牌/產品對比
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 競爭格局
第24章 公司簡介
- 主要參與企業
- BYD COMPANY LTD.
- YUTONG BUS CO., LTD.
- ZHEJIANG GEELY HOLDING GROUP
- DAIMLER TRUCK AG
- NFI GROUP
- AB VOLVO
- CAF(SOLARIS BUS & COACH SP. Z OO)
- ZHONGTONG BUS HOLDING CO., LTD.
- CRRC CORPORATION LIMITED
- VDL GROEP
- EBUSCO
- XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.
- 其他公司
- BLUE BIRD CORPORATION
- GILLIG LLC.
- THE LION ELECTRIC COMPANY
- TATA MOTORS LIMITED.
- ASHOK LEYLAND
- CHANGSHA SUNDA NEW ENERGY TECHNOLOGY CO., LTD.
- GREE ALTAIRNANO NEW ENERGY INC.
- XIAMEN GOLDEN DRAGON BUS CO. LTD.
- JBM GROUP
- SCANIA AB
- IRIZAR GROUP
- IVECO SPA
- BLUEBUS
- BOZANKAYA
- CAETANOBUS
- CHARIOT MOTORS
- HEULIEZ BUS
- OTOKAR OTOMOTIV VE SAVUNMA SANAYI AS
- TEMSA
- URSUS SA
- KARSAN OTOMOTIV SANAYII VE TICARET AS
- MELLOR
- HINO MOTORS, LTD.
- ANHUI ANKAI AUTOMOBILE CO., LTD.
- OLECTRA GREENTECH LIMITED
第25章調查方法
第26章附錄
The global electric buses market is projected to grow from USD 30.64 billion in 2026 and reach USD 80.58 billion in 2035, at a CAGR of 11.3%. Beyond traditional municipal transit, the market is expanding into private employee transportation, corporate mobility, airport transfers, tourism, intercity services, school transportation, and regional routes, creating new demand for electric buses with longer range and higher daily utilization.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | USD billion |
| Segments | By propulsion, length of bus, component, range, power output, battery capacity, application, battery type, seating capacity, consumers, GVW, level of autonomy |
| Regions covered | Asia Pacific, North America, Europe |
Improvements in battery capacity, fast charging, thermal management, and vehicle efficiency are enabling operators to deploy electric buses on increasingly demanding routes, while fleet operators are placing greater emphasis on total cost of ownership, vehicle utilization, and energy costs rather than only upfront vehicle price. This is also creating opportunities for high-range BEVs and FCEVs, particularly for intercity and high-mileage operations where charging time and route flexibility are critical.
The government sector is estimated to generate the largest demand for electric buses in 2026.
The government sector dominates the electric bus demand in 2026 because public transport authorities control a large share of urban bus procurement. State-owned or municipal transit corporations are typically the largest single buyers of buses in most countries. The government sector bodies benefit from centralized purchasing, depot-based charging infrastructure, and predictable route operations that make large-scale electrification more feasible than fragmented private-fleet applications. This dominance is reinforced through structured procurement models, fleet-replacement mandates, and public-private partnerships that reduce the upfront cost and financial risk historically associated with e-bus adoption. Furthermore, government-backed funding mechanisms, subsidy schemes, and dedicated procurement programs further lower the upfront cost barrier for transit authorities. In addition, several countries have established long-term electrification roadmaps that require new electric bus purchases by public transit agencies to be zero-emission beyond certain dates, creating sustained, policy-backed demand visibility. Thus, the combination of concentrated buying power, supportive policy frameworks, and structural funding support is expected to keep the government and public-transit segment as the anchor demand driver for the electric buses market through the forecast period.
The above 400 kWh battery capacity is expected to grow at a faster rate during the forecast period.
The above 400 kWh segment is growing at a faster rate as it is supported by continuous battery development, declining battery costs, and improvements in charging infrastructure. Key manufacturers are increasingly introducing higher-capacity battery systems to extend bus range without significantly compromising passenger capacity or vehicle performance. According to the International Energy Agency (IEA), battery economics are also improving, with global average battery prices declining to 8% in 2025 compared to 2024. This supports the commercial viability of larger battery packs. At the same time, advances in high-power charging and depot infrastructure are reducing the operational penalty associated with larger batteries. Moreover, battery capacities above 400 kWh are becoming suitable not only for longer urban routes but also for suburban, regional, intercity, airport, employee-transport, and other high-utilization applications. The IEA data shows that the average range of available battery-electric bus models reached 360 km in 2025, around 15% higher than in 2020, while the industry is increasingly developing models capable of much longer ranges. This supports the shift toward higher-capacity configurations as electric buses expand beyond traditional city transit. Growing adoption by private fleet operators and long-distance applications is expected to further accelerate demand for >400 kWh battery capacity buses.
North America is the fastest-growing region for the electric buses market.
North America is expected to offer strong long-term growth potential for electric buses despite a temporary slowdown in 2025. US zero-emission bus registrations declined 25.9%, from 3,911 units in 2024 to 2,626 units in 2025, reducing the zero-emission share of new bus registrations from 7.0% to 4.4%. However, the decline reflects slower procurement and policy uncertainty rather than a structural move away from electrification. North America's electric bus market is expected to remain relatively stagnant through 2029, primarily because of uncertainty around federal zero-emission bus funding, procurement priorities, and the economics of electric buses. Moreover, new tariffs on imported buses, batteries, steel, aluminum and other components increased vehicle costs and encouraged transit agencies to delay or reassess purchases. As a result, BEV growth has been moderated in the forecast rather than assuming a rapid return to the previous growth trajectory, with recovery expected after 2029 as aging transit and school-bus fleets require replacement, state-level mandates continue to support electrification, domestic manufacturing expands, and battery costs improve. FCEVs are expected to decline much more sharply because of limited hydrogen infrastructure, higher vehicle and fuel costs, fewer upcoming orders and limited OEM availability in the region. School buses are expected to remain the largest application, supported by the large replacement requirement and state-level electrification programs, particularly in California and other ZEV-focused states. Transit-bus adoption is likely to recover more gradually. Major players such as NFI/New Flyer, Gillig, Blue Bird, Nova Bus/Volvo, BYD, and REV Group are responding by increasing domestic production, maintaining broader propulsion portfolios, strengthening state-level customer relationships, and prioritizing markets with clearer funding visibility. Overall, the North American market is likely to experience a policy-driven pause rather than a structural reversal, with moderate BEV recovery after 2029 but a sustained decline in FCEV deployment.
Break-up of the profile of primary participants in the electric buses market:
By Companies: Bus Battery Manufacturers - 30%, OEMs - 70%
By Designation: Manager level - 50%, C-Level Executives - 30%, Others - 20%
By Region: North America - 10%, Europe - 30%, and Asia Pacific - 60%
Major manufacturers in the electric buses market include BYD Company Ltd. (China), Yutong Co., Ltd. (China), Xiamen King Long (China), CRRC Corporation Limited (China), Zhejiang Gelly Holding Group (China), NFI Group (Canada), AB Volvo (Sweden), Solaris Bus & Coach SP. Z.O.O (Poland), and Daimler Truck AG (Germany). These companies adopted new product development and supply contract strategies to gain traction in the electric buses market.
Research Coverage:
The study segments the electric buses market and forecasts the market size based on propulsion (BEVs, FCEVs), range (up to 300 miles, above 300 miles), length of bus (less than 9 m, 9-14 m, more than 14m), consumer (private, government), application (transit buses, coaches, school buses, and others), battery capacity (up to 400 kWh, Above 400 kWh), component (motors, batteries, fuel cell stacks, battery management systems, battery cooling systems, DC-DC converters, inverters, AC/DC chargers, EV connectors), level of autonomy (semi-autonomous, autonomous), power output (up to 250 kW, above 250 kW), seating capacity (up to 40 seats, 40-70 seats, above 70 seats), by GVW (Up to 10 tonnes, 10 to 20 tonnes, and above 20 tonnes), and region (Asia Pacific, North America, Middle East & Africa [MEA], Europe, and Latin America). This report covers the competitive analysis of upcoming startups/SMEs in the electric buses market ecosystem.
The report's scope covers detailed information regarding the major factors influencing the growth of the electric buses market. A thorough analysis of the key industry players has provided insights into their business overview, products, key strategies, contracts, partnerships, agreements, product launches, mergers & acquisitions, microeconomic indicators, and recent developments in the electric buses market.
Key Benefits of Buying the Report:
The report will help market leaders/new entrants with information on the closest approximations of the revenue numbers for the overall electric buses market and the subsegments. The report includes a comprehensive market share analysis, supply chain analysis, extensive lists and insights into component manufacturers, and a competitive landscape. The report also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
- Analysis of critical drivers (Shift from vehicle procurement to route-economics optimization, and Platform modularization enabling multi-route eBuses scaling), restraints (CNG and biofuel buses slowing adoption of electric buses), opportunities (Battery-swapping solutions for selected commercial fleets, Integrated eBuses-Depot-Energy Solutions), and challenges (High power e-axle durability under continues stop-go duty cycles, Maintaining range under extreme temperatures and heavy HVAC loads).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the electric buses market
- Market Development: Comprehensive information about lucrative markets (the report analyzes the electric buses market across varied regions)
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the electric buses market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players in the electric buses market, such as BYD Company Ltd. (China), Yutong Co., Ltd. (China), Xiamen King Long (China), CRRC Corporation Limited (China), and Zhejiang Geely Holding Group (China).
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SNAPSHOT
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET INSIGHTS AND KEY HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN ELECTRIC BUSES MARKET
- 3.2 ELECTRIC BUSES MARKET, BY PROPULSION
- 3.3 ELECTRIC BUSES MARKET, BY RANGE
- 3.4 ELECTRIC BUSES MARKET, BY COMPONENT
- 3.5 ELECTRIC BUSES MARKET, BY CONSUMER
- 3.6 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY
- 3.7 ELECTRIC BUSES MARKET, BY BATTERY TYPE
- 3.8 ELECTRIC BUSES MARKET, BY APPLICATION
- 3.9 ELECTRIC BUSES MARKET, BY POWER OUTPUT
- 3.10 ELECTRIC BUSES MARKET, BY LENGTH
- 3.11 ELECTRIC BUSES MARKET, BY SEATING CAPACITY
- 3.12 ELECTRIC BUSES MARKET, BY GVW
- 3.13 ELECTRIC BUSES MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Shift from vehicle procurement to route-economics optimization
- 4.2.1.2 Platform modularization enables multi-route electric bus scaling
- 4.2.1.3 Growing availability of financing and leasing/business models
- 4.2.2 RESTRAINTS
- 4.2.2.1 CNG and biofuel buses slowing adoption of electric buses
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Battery swapping solutions for selected commercial fleets
- 4.2.3.2 Second-life and battery recycling ecosystem
- 4.2.3.3 Integrated electric buses depot energy solutions
- 4.2.4 CHALLENGES
- 4.2.4.1 High-power e-axle durability under continuous stop-and-go duty cycles
- 4.2.4.2 Maintaining range under extreme temperature and heavy HVAC loads
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS
- 4.3.2 WHITE SPACES
- 4.4 INTERCONNECTED MARKET AND CROSS-SECTOR OPPORTUNITY
- 4.5 STRATEGIC MOVES BY KEY PLAYERS
5 INDUSTRIAL TRENDS
- 5.1 MACROECONOMIC OUTLOOK
- 5.1.1 INTRODUCTION
- 5.1.2 GDP TRENDS AND FORECAST
- 5.1.3 TRENDS IN ELECTRIC BUSES MARKET
- 5.1.3.1 Investment environment
- 5.2 SUPPLY CHAIN ANALYSIS
- 5.3 ECOSYSTEM ANALYSIS
- 5.4 ELECTRIC BUSES ECOSYSTEM
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICE OF ELECTRIC BUSES, BY REGION, 2026
- 5.5.1.1 Indicative price of electric buses, by region, 2026
- 5.5.1.2 Indicative price of electric buses, by application, 2026
- 5.5.1.3 Indicative price of electric buses, by propulsion, 2026
- 5.5.1 INDICATIVE PRICE OF ELECTRIC BUSES, BY REGION, 2026
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2028
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 870240)
- 5.7.2 EXPORT SCENARIO (HS CODE 870240)
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 COMPLETE TRANSITION TO ELECTRIC BUSES IN SHENZHEN, CHINA
- 5.10.2 ZENOBE HELPED STAGECOACH INCORPORATE CHARGING INFRASTRUCTURE AND INSTALL CUSTOM MANAGEMENT SOFTWARE SYSTEM
- 5.10.3 HSL WAS AWARDED OPERATIONS BASED ON OPEN TENDERS UNDER CHARGING-AS-A-SERVICE (CAAS) BUSINESS MODEL
- 5.10.4 AI-POWERED SOFTWARE IMPLEMENTED TO HELP FLEET OPERATORS CHARGE ELECTRIC BUSES
- 5.10.5 HIGHLAND ELECTRIC FLEETS, IN PARTNERSHIP WITH NATIONAL GRID, PROVIDED ELECTRIC SCHOOL BUSES AND COORDINATED ITS PARTICIPATION IN V2G PROGRAM SCHOOL BUSES
- 5.10.6 VERMONT ELECTRIC SCHOOL AND TRANSIT BUS PILOT PROGRAM IMPLEMENTED TO FACILITATE COST-EFFECTIVE ELECTRIFICATION
- 5.10.7 FLEET TEST & EVALUATION TEAM AT NREL SUPPORTED AVTA BY CONDUCTING ASSESSMENTS OF MEDIUM- AND HEAVY-DUTY VEHICLES, ELECTRIC BUSES, AND TROLLEYS
- 5.10.8 EVENERGI DEVELOPED FRAMEWORK TO DETERMINE OPTIMAL COMBINATION OF DEPOT LAYOUTS, CHARGER SPEEDS, AND CHARGER TYPES
- 5.11 TOTAL COST OF OWNERSHIP
- 5.12 ELECTRIC BUSES REGISTRATION IN EUROPE, 2025-2024
- 5.13 BILL OF MATERIALS ANALYSIS
- 5.14 OEM ANALYSIS
- 5.14.1 INTRODUCTION
- 5.14.2 ELECTRIC AND ICE BUS MODELS: LENGTH VS. NUMBER OF SEATS
- 5.14.3 ELECTRIC BUS MODELS: LENGTH VS. NUMBER OF SEATS
- 5.14.4 BATTERY CAPACITY VS. DRIVE RANGE VS. PAX
- 5.15 ELECTRIC BUS DRIVE MOTOR SUPPLIERS, BY OEM AND REGION, 2026
- 5.16 ELECTRIC BUS BATTERY CELL SUPPLIERS, BY OEM AND REGION, 2026
6 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 6.1 DECISION-MAKING PROCESS
- 6.2 KEY STAKEHOLDERS & BUYING CRITERIA
- 6.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 6.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 6.5 MARKET PROFITABILITY
- 6.5.1 MARKET PROFITABILITY FOR ELECTRIC BUSES
7 REGULATORY LANDSCAPE
- 7.1 INTRODUCTION
- 7.2 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.2.1 NORTH AMERICA
- 7.2.2 EUROPE
- 7.2.3 ASIA PACIFIC
- 7.2.4 LATIN AMERICA
- 7.2.5 MIDDLE EAST & AFRICA
- 7.2.6 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS, BY REGION
8 INDUSTRY TRENDS: TECHNOLOGICAL ADVANCEMENTS, PATENTS, INNOVATIONS, AND FUTURE STRATEGIC APPLICATIONS
- 8.1 PATENT ANALYSIS
- 8.1.1 INTRODUCTION
9 ELECTRIC BUSES MARKET, BY APPLICATION
- 9.1 INTRODUCTION
- 9.2 CITY/TRANSIT BUSES
- 9.2.1 NEED TO IMPROVE AIR QUALITY IN CITIES TO DRIVE DEMAND
- 9.3 COACHES
- 9.3.1 GROWING DEMAND FOR SUSTAINABLE LONG-DISTANCE TRAVEL TO DRIVE DEMAND
- 9.4 SCHOOL BUSES
- 9.4.1 GROWING DEMAND IN NORTH AMERICA TO DRIVE THE ELECTRIC SCHOOL BUSES MARKET
- 9.5 OTHER APPLICATIONS
- 9.6 KEY INDUSTRY INSIGHTS
10 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY
- 10.1 INTRODUCTION
- 10.2 UP TO 400 KWH
- 10.2.1 DEPLOYMENT IN INTRACITY TRANSPORT TO PROPEL GROWTH
- 10.3 ABOVE 400 KWH
- 10.3.1 USED FOR LONG-DISTANCE COMMUTE
- 10.4 KEY INDUSTRY INSIGHTS
11 ELECTRIC BUSES MARKET, BY BATTERY TYPE
- 11.1 INTRODUCTION
- 11.2 NMC BATTERIES
- 11.2.1 INCREASED PREFERENCE FOR HIGH ENERGY DENSITY
- 11.3 LFP BATTERIES
- 11.3.1 DEMAND FOR LOW-COST AND GOOD THERMAL STABILITY
- 11.4 NCA BATTERIES
- 11.4.1 BENEFITS ASSOCIATED WITH HIGH ENERGY DENSITY AND LONG-LIFE CYCLE
- 11.5 OTHER BATTERIES
- 11.6 KEY INDUSTRY INSIGHTS
12 ELECTRIC BUSES MARKET, BY COMPONENT
- 12.1 INTRODUCTION
- 12.2 MOTORS
- 12.2.1 HIGHER EFFICIENCY THAN TRADITIONAL COMBUSTION ENGINES TO DRIVE GROWTH
- 12.3 BATTERIES
- 12.3.1 DECREASING PRICE OF LITHIUM-ION BATTERIES TO DRIVE GROWTH
- 12.4 FUEL CELL STACKS
- 12.4.1 INCREASING DEMAND FOR HYDROGEN FUEL CELL ELECTRIC BUSES TO DRIVE GROWTH
- 12.5 BATTERY MANAGEMENT SYSTEMS
- 12.5.1 NEED FOR EFFICIENT BATTERY OPTIMIZATION IN ELECTRIC BUSES TO DRIVE GROWTH
- 12.6 BATTERY COOLING SYSTEMS
- 12.6.1 GROWING FOCUS ON INCREASING BATTERY LIFE AND IMPROVING THERMAL MANAGEMENT TO DRIVE GROWTH
- 12.7 DC-DC CONVERTERS
- 12.7.1 KEY SAFETY SYSTEMS IN ELECTRIC BUSES
- 12.8 INVERTERS
- 12.8.1 GROWING DEMAND FOR ELECTRIC BUSES WITH HIGHER RANGE TO DRIVE GROWTH
- 12.9 AC/DC CHARGERS
- 12.9.1 CRITICAL TO OVERALL OPERATION AND EFFICIENCY OF ELECTRIC BUSES
- 12.10 EV CONNECTORS
- 12.10.1 INCREASING INVESTMENTS IN SUSTAINABLE URBAN TRANSPORTATION INITIATIVES TO DRIVE GROWTH
- 12.11 KEY INDUSTRY INSIGHTS
13 ELECTRIC BUSES MARKET, BY CONSUMER
- 13.1 INTRODUCTION
- 13.2 PRIVATE
- 13.2.1 GOVERNMENT SUBSIDIES TO PROMOTE ADOPTION OF ELECTRIC BUSES
- 13.3 PUBLIC
- 13.3.1 USE OF ELECTRIC BUSES FOR PUBLIC TRANSPORTATION
- 13.4 KEY INDUSTRY INSIGHTS
14 ELECTRIC BUSES MARKET, BY DRIVETRAIN ARCHITECTURE
- 14.1 INTRODUCTION
- 14.2 CENTRAL MOTOR
- 14.3 INTEGRATED E-AXLE
- 14.4 HUB/IN-WHEEL MOTOR
- 14.5 KEY INDUSTRY INSIGHTS
15 ELECTRIC BUSES MARKET, BY GROSS VEHICLE WEIGHT (GVW)
- 15.1 INTRODUCTION
- 15.2 UP TO 10 TONNES
- 15.2.1 NEED FOR ELECTRIC BUSES FOR SHORT-DISTANCE SHUTTLES TO DRIVE GROWTH
- 15.3 10-20 TONNES
- 15.3.1 ASIA PACIFIC TO LEAD MARKET IN THIS SEGMENT
- 15.4 ABOVE 20 TONNES
- 15.4.1 ENGINEERED FOR BIGGER AND TEDIOUS OPERATIONS
- 15.5 KEY INDUSTRY INSIGHTS
16 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES
- 16.1 INTRODUCTION
- 16.2 LESS THAN 9 M
- 16.2.1 EASY MANEUVERING ON COMPACT ROADS
- 16.3 9-14 M
- 16.3.1 SUITABLE FOR FULL-DAY OPERATIONS
- 16.4 MORE THAN 14 M
- 16.4.1 GROWING NUMBER OF ARTICULATED ELECTRIC BUSES TO DRIVE MARKET
- 16.5 KEY INDUSTRY INSIGHTS
17 ELECTRIC BUSES MARKET, BY LEVEL OF AUTONOMY
- 17.1 INTRODUCTION
- 17.2 SEMI-AUTONOMOUS
- 17.3 AUTONOMOUS
- 17.4 KEY INDUSTRY INSIGHTS
18 ELECTRIC BUSES MARKET, BY POWER OUTPUT
- 18.1 INTRODUCTION
- 18.2 UP TO 250 KW
- 18.2.1 WIDELY USED IN PUBLIC TRANSPORT BUSES
- 18.3 ABOVE 250 KW
- 18.3.1 DEMAND FOR HIGH-PERFORMANCE ELECTRIC BUSES TO DRIVE MARKET
- 18.4 KEY PRIMARY INSIGHTS
19 ELECTRIC BUSES MARKET, BY PROPULSION
- 19.1 INTRODUCTION
- 19.2 BATTERY ELECTRIC BUSES (BEV)
- 19.2.1 FALLING BATTERY PRICES AND GOVERNMENT INCENTIVES TO ELECTRIFY PUBLIC BUS FLEETS
- 19.3 FUEL CELL ELECTRIC BUSES (FCEV)
- 19.3.1 SUSTAINABLE PRODUCTION OF HYDROGEN TO DRIVE GROWTH
- 19.4 KEY INDUSTRY INSIGHTS
20 ELECTRIC BUSES MARKET, BY RANGE
- 20.1 INTRODUCTION
- 20.1.1 SUITABLE FOR URBAN AND SUBURBAN ROUTES WITH FREQUENT STOPS AND SHORTER DISTANCES BETWEEN CHARGING POINTS
- 20.2 ABOVE 300 MILES
- 20.2.1 INCREASING DEMAND FOR INTERCITY ELECTRIC BUSES TO DRIVE MARKET
- 20.3 KEY PRIMARY INSIGHTS
21 ELECTRIC BUSES MARKET, BY SEATING CAPACITY
- 21.1 INTRODUCTION
- 21.2 UP TO 40 SEATS
- 21.2.1 NEED FOR ELECTRIC BUSES FOR SHORT-DISTANCE SHUTTLES TO DRIVE DEMAND
- 21.3 40-70 SEATS
- 21.3.1 SUITABLE FOR DENSELY POPULATED AREAS
- 21.4 ABOVE 70 SEATS
- 21.4.1 NEED FOR HIGHER PASSENGER-CARRYING CAPABILITIES TO DRIVE DEMAND
- 21.5 KEY INDUSTRY INSIGHTS
22 ELECTRIC BUSES MARKET, BY REGION
- 22.1 INTRODUCTION
- 22.2 ASIA PACIFIC
- 22.2.1 CHINA
- 22.2.1.1 Widespread adoption of electric buses in public transport and presence of leading OEMs to boost growth
- 22.2.2 JAPAN
- 22.2.2.1 Focus on developing advanced electric buses to drive market
- 22.2.3 INDIA
- 22.2.3.1 Government support for electrification of public transport to propel demand for electric buses
- 22.2.4 SOUTH KOREA
- 22.2.4.1 Focus on electrification of public transport fleets to boost growth
- 22.2.5 SINGAPORE
- 22.2.5.1 Growing emphasis on promoting green public transport by 2040 to boost growth
- 22.2.6 INDONESIA
- 22.2.6.1 Government's commitment to improving air quality to spur demand
- 22.2.7 AUSTRALIA
- 22.2.7.1 Increasing awareness regarding climate change to drive growth
- 22.2.1 CHINA
- 22.3 EUROPE
- 22.3.1 FRANCE
- 22.3.1.1 Aim for all-electric public transport fleet by 2025 to promote use of electric buses
- 22.3.2 GERMANY
- 22.3.2.1 Increased government incentives and investments for infrastructure development to boost market
- 22.3.3 SPAIN
- 22.3.3.1 Government's focus on replacing existing public transport fleet with electric buses to boost growth
- 22.3.4 ITALY
- 22.3.4.1 Rising concerns about emissions to encourage government to adopt electrification of public transport system
- 22.3.5 NORWAY
- 22.3.5.1 Rising government support and schemes for electric buses to increase demand
- 22.3.6 SWEDEN
- 22.3.6.1 Presence of market-leading OEMs to support growth of electric buses market
- 22.3.7 DENMARK
- 22.3.7.1 Favorable government regulations to support growth of electric buses market
- 22.3.8 NETHERLANDS
- 22.3.8.1 Increased orders and deliveries of electric buses to boost demand
- 22.3.9 BELGIUM
- 22.3.9.1 Investments in electrification of public transport to drive growth
- 22.3.10 UK
- 22.3.10.1 Stringent regulations for emission-free buses to boost adoption of electric buses
- 22.3.11 FINLAND
- 22.3.11.1 Continuous need to reduce carbon emissions to drive growth
- 22.3.12 POLAND
- 22.3.12.1 Push toward sustainable public transportation to spur demand for electric buses
- 22.3.1 FRANCE
- 22.4 NORTH AMERICA
- 22.4.1 US
- 22.4.1.1 Government programs to promote zero-emission vehicles to boost growth
- 22.4.2 CANADA
- 22.4.2.1 Government subsidies and presence of key players to boost adoption of electric school buses
- 22.4.1 US
- 22.5 LATIN AMERICA
- 22.5.1 ARGENTINA
- 22.5.1.1 Demand for electrification of bus fleets to boost demand for advanced electric buses
- 22.5.2 BRAZIL
- 22.5.2.1 Growing environmental concerns to lead to demand for electric buses
- 22.5.3 CHILE
- 22.5.3.1 Government's focus on promoting emission-free public transport to encourage use of electric buses
- 22.5.4 MEXICO
- 22.5.4.1 Rapid strategies undertaken by government to indicate growth of electric buses market
- 22.5.5 COLOMBIA
- 22.5.5.1 Increasing government initiatives for electric bus purchases to drive market
- 22.5.1 ARGENTINA
- 22.6 MIDDLE EAST & AFRICA
- 22.6.1 SOUTH AFRICA
- 22.6.1.1 Investments by leading OEMs in advanced technologies in automotive sector to drive market
- 22.6.2 UAE
- 22.6.2.1 Growing electrification trend in cities to boost demand for electric buses
- 22.6.3 QATAR
- 22.6.3.1 Net-zero aims to push incorporation of electric buses
- 22.6.1 SOUTH AFRICA
23 COMPETITIVE LANDSCAPE
- 23.1 OVERVIEW
- 23.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 23.3 REVENUE ANALYSIS
- 23.4 ELECTRIC BUS MARKET SHARE ANALYSIS, 2025
- 23.4.1 ASIA ELECTRIC BUS MARKET SHARE ANALYSIS, 2025
- 23.4.2 EUROPE ELECTRIC BUS MARKET SHARE ANALYSIS, 2025
- 23.4.3 NORTH AMERICA ELECTRIC BUS MARKET SHARE ANALYSIS, 2025
- 23.5 COMPANY VALUATION
- 23.6 FINANCIAL METRICS
- 23.7 BRAND/PRODUCT COMPARISON
- 23.8 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 23.8.1 STARS
- 23.8.2 EMERGING LEADERS
- 23.8.3 PERVASIVE PLAYERS
- 23.8.4 PARTICIPANTS
- 23.8.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 23.9 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 23.9.1 PROGRESSIVE COMPANIES
- 23.9.2 RESPONSIVE COMPANIES
- 23.9.3 DYNAMIC COMPANIES
- 23.9.4 STARTING BLOCKS
- 23.9.5 COMPETITIVE BENCHMARKING
- 23.10 COMPETITIVE SCENARIO
- 23.10.1 PRODUCT LAUNCHES, DEVELOPMENTS, AND ENHANCEMENTS, SEPTEMBER 2022-JULY 2025
- 23.10.2 DEALS, FEBRUARY 2025-FEBRUARY 2026
- 23.10.3 EXPANSIONS, JULY 2025-MAY 2026
- 23.10.4 OTHERS, OCTOBER 2022-JULY 2025
24 COMPANY PROFILES
- 24.1 KEY PLAYERS
- 24.1.1 BYD COMPANY LTD.
- 24.1.1.1 Business overview
- 24.1.1.2 Products/Solutions offered
- 24.1.1.3 Recent developments
- 24.1.1.4 MnM view
- 24.1.1.4.1 Key strengths
- 24.1.1.4.2 Strategic choices
- 24.1.1.4.3 Weaknesses & competitive threats
- 24.1.2 YUTONG BUS CO., LTD.
- 24.1.2.1 Business overview
- 24.1.2.2 Products/Solutions offered
- 24.1.2.3 Recent developments
- 24.1.2.4 MnM view
- 24.1.2.4.1 Key Strengths
- 24.1.2.4.2 Strategic choices
- 24.1.2.4.3 Weaknesses & competitive threats
- 24.1.3 ZHEJIANG GEELY HOLDING GROUP
- 24.1.3.1 Business overview
- 24.1.3.2 Products/Solutions offered
- 24.1.3.3 Recent developments
- 24.1.3.4 MnM view
- 24.1.3.4.1 Key strengths
- 24.1.3.4.2 Strategic choices
- 24.1.3.4.3 Weaknesses & competitive threats
- 24.1.4 DAIMLER TRUCK AG
- 24.1.4.1 Business overview
- 24.1.4.2 Products/Solutions offered
- 24.1.4.3 Recent developments
- 24.1.4.4 MnM view
- 24.1.4.4.1 Key Strengths
- 24.1.4.4.2 Strategic choices
- 24.1.4.4.3 Weaknesses & competitive threats
- 24.1.5 NFI GROUP
- 24.1.5.1 Business overview
- 24.1.5.2 Products/Solutions offered
- 24.1.5.3 Recent developments
- 24.1.5.4 MnM view
- 24.1.5.4.1 Right to win
- 24.1.5.4.2 Strategic choices
- 24.1.5.4.3 Weaknesses & competitive threats
- 24.1.6 AB VOLVO
- 24.1.6.1 Business overview
- 24.1.6.2 Products/Solutions offered
- 24.1.6.3 Recent developments
- 24.1.7 CAF (SOLARIS BUS & COACH SP. Z O.O.)
- 24.1.7.1 Business overview
- 24.1.7.2 Products/Solutions offered
- 24.1.7.3 Recent developments
- 24.1.8 ZHONGTONG BUS HOLDING CO., LTD.
- 24.1.8.1 Business overview
- 24.1.8.2 Products/Solutions offered
- 24.1.8.3 Recent developments
- 24.1.9 CRRC CORPORATION LIMITED
- 24.1.9.1 Business overview
- 24.1.9.2 Products/Solutions offered
- 24.1.9.3 Recent developments
- 24.1.9.3.1 CCR Corporation Limited: Expansion
- 24.1.10 VDL GROEP
- 24.1.10.1 Business overview
- 24.1.10.2 Products/Solutions offered
- 24.1.10.3 Recent developments
- 24.1.11 EBUSCO
- 24.1.11.1 Business overview
- 24.1.11.2 Products/Solutions offered
- 24.1.11.3 Recent developments
- 24.1.12 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.
- 24.1.12.1 Business overview
- 24.1.12.2 Products/Solutions offered
- 24.1.12.3 Recent developments
- 24.1.1 BYD COMPANY LTD.
- 24.2 OTHER PLAYERS
- 24.2.1 BLUE BIRD CORPORATION
- 24.2.2 GILLIG LLC.
- 24.2.3 THE LION ELECTRIC COMPANY
- 24.2.4 TATA MOTORS LIMITED.
- 24.2.5 ASHOK LEYLAND
- 24.2.6 CHANGSHA SUNDA NEW ENERGY TECHNOLOGY CO., LTD.
- 24.2.7 GREE ALTAIRNANO NEW ENERGY INC.
- 24.2.8 XIAMEN GOLDEN DRAGON BUS CO. LTD.
- 24.2.9 JBM GROUP
- 24.2.10 SCANIA AB
- 24.2.11 IRIZAR GROUP
- 24.2.12 IVECO S.P.A
- 24.2.13 BLUEBUS
- 24.2.14 BOZANKAYA
- 24.2.15 CAETANOBUS
- 24.2.16 CHARIOT MOTORS
- 24.2.17 HEULIEZ BUS
- 24.2.18 OTOKAR OTOMOTIV VE SAVUNMA SANAYI A.S.
- 24.2.19 TEMSA
- 24.2.20 URSUS S.A.
- 24.2.21 KARSAN OTOMOTIV SANAYII VE TICARET A.S.
- 24.2.22 MELLOR
- 24.2.23 HINO MOTORS, LTD.
- 24.2.24 ANHUI ANKAI AUTOMOBILE CO., LTD.
- 24.2.25 OLECTRA GREENTECH LIMITED
25 RESEARCH METHODOLOGY
- 25.1 RESEARCH DATA
- 25.1.1 SECONDARY DATA
- 25.1.1.1 Key secondary sources
- 25.1.1.2 Key data from secondary sources
- 25.1.2 PRIMARY DATA
- 25.1.2.1 Primary participants
- 25.1.1 SECONDARY DATA
- 25.2 MARKET SIZE ESTIMATION
- 25.2.1 BOTTOM-UP APPROACH
- 25.3 DATA TRIANGULATION
- 25.4 FACTOR ANALYSIS
- 25.5 RESEARCH ASSUMPTIONS AND RISK ASSESSMENT
- 25.6 RESEARCH LIMITATIONS
26 APPENDIX
- 26.1 KEY INDUSTRY INSIGHTS
- 26.2 DISCUSSION GUIDE
- 26.3 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 26.4 CUSTOMIZATION OPTIONS
- 26.5 RELATED REPORTS
- 26.6 AUTHOR DETAILS
List of Tables
- TABLE 1 EXCHANGE RATE, 2025-2022
- TABLE 2 PLATFORM MODULARIZATION BY KEY PLAYERS
- TABLE 3 FINANCING AND LEASING/BUSINESS MODELS FOR ELECTRIC BUSES BY REGION
- TABLE 4 BBATTERY-SWAPPING LAUNCHES/DEPLOYMENTS RELEVANT TO ELECTRIC BUSES
- TABLE 5 KEY QUANTITATIVE EVIDENCE FROM MERCEDES-BENZ
- TABLE 6 INTEGRATED DEPOT ENERGY SOLUTIONS - KEY DEPLOYMENTS
- TABLE 7 E-AXLE OFFERING WITH ADVANTAGES FOR ELECTRIC BUSES
- TABLE 8 TEMPERATURE AND HVAC IMPACT ON ELECTRIC BUS RANGE
- TABLE 9 STRATEGIC MOVES BY TOP KEY PLAYERS
- TABLE 10 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2022-2031
- TABLE 11 ROLE OF COMPANIES IN ELECTRIC BUSES MARKET ECOSYSTEM
- TABLE 12 REGION-WISE INDICATIVE PRICE OF ELECTRIC BUSES, 2026 (USD)
- TABLE 13 INDICATIVE PRICING OF ELECTRIC BUSES, BY APPLICATION, 2026 (USD)
- TABLE 14 INDICATIVE PRICING OF ELECTRIC BUSES, BY PROPULSION, 2026 (USD)
- TABLE 15 ELECTRIC BUSES MARKET: KEY CONFERENCES & EVENTS, 2026-2028
- TABLE 16 IMPORT DATA FOR HS CODE 870240-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 17 EXPORT DATA FOR HS CODE 870240-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 18 LIST OF FUNDING, 2022-2025
- TABLE 19 ANALYSIS TO EVALUATE FINANCIAL FEASIBILITY OF DEPLOYING ELECTRIC BUS FLEETS
- TABLE 20 DEPLOYMENT OF ELECTRIC BUSES IN DOHA PUBLIC TRANSPORT, 2022
- TABLE 21 TOTAL COST OF OWNERSHIP FOR ELECTRIC BUSES
- TABLE 22 ELECTRIC BUSES REGISTRATION FOR EUROPE, 2025 - 2024
- TABLE 23 ELECTRIC BUS DRIVE MOTOR SUPPLIERS, BY BRAND/OEM AND REGION, 2026
- TABLE 24 ELECTRIC BUS BATTERY CELL SUPPLIERS, BY BRAND/OEM AND REGION, 2026
- TABLE 25 KEY BUYING CRITERIA FOR ELECTRIC BUS, BY PROPULSION
- TABLE 26 MARKET PROFITABILITY FOR ELECTRIC BUSES BY VALUE-CHAIN SEGMENT
- TABLE 27 NORTH AMERICA: POLICIES AND INITIATIVES SUPPORTING ELECTRIC & HYDROGEN-POWERED BUSES AND INFRASTRUCTURE
- TABLE 28 EUROPE: POLICIES AND INITIATIVES SUPPORTING ELECTRIC & HYDROGEN-POWERED BUSES AND INFRASTRUCTURE
- TABLE 29 ASIA PACIFIC: POLICIES AND INITIATIVES SUPPORTING ELECTRIC & HYDROGEN-POWERED BUSES AND INFRASTRUCTURE
- TABLE 30 LATIN AMERICA: POLICIES AND INITIATIVES SUPPORTING ELECTRIC & HYDROGEN-POWERED BUSES AND INFRASTRUCTURE
- TABLE 31 MIDDLE EAST & AFRICA: POLICIES AND INITIATIVES SUPPORTING ELECTRIC & HYDROGEN-POWERED BUSES AND INFRASTRUCTURE
- TABLE 32 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 33 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 34 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 35 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 36 LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 37 KEY PATENTS, 2025-2026
- TABLE 38 ELECTRIC BUSES MARKET, BY APPLICATION, 2022-2025 (UNITS)
- TABLE 39 ELECTRIC BUSES MARKET, BY APPLICATION, 2026-2030 (UNITS)
- TABLE 40 ELECTRIC BUSES MARKET, BY APPLICATION, 2031-2035 (UNITS)
- TABLE 41 ELECTRIC BUSES MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 42 ELECTRIC BUSES MARKET, BY APPLICATION, 2026-2030 (USD MILLION)
- TABLE 43 ELECTRIC BUSES MARKET, BY APPLICATION, 2031-2035 (USD MILLION)
- TABLE 44 CITY/TRANSIT BUSES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 45 CITY/TRANSIT BUSES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 46 CITY/TRANSIT BUSES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 47 CITY/TRANSIT BUSES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 48 CITY/TRANSIT BUSES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 49 CITY/TRANSIT BUSES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 50 COACHES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 51 COACHES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 52 COACHES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 53 COACHES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 54 COACHES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 55 COACHES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 56 SCHOOL BUSES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 57 SCHOOL BUSES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 58 SCHOOL BUSES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 59 SCHOOL BUSES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 60 SCHOOL BUSES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 61 SCHOOL BUSES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 62 OTHER APPLICATIONS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 63 OTHER APPLICATIONS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 64 OTHER APPLICATIONS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 65 OTHER APPLICATIONS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 66 OTHER APPLICATIONS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 67 OTHER APPLICATIONS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 68 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2022-2025 (UNITS)
- TABLE 69 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2026-2030 (UNITS)
- TABLE 70 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2031-2035 (UNITS)
- TABLE 71 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 72 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2026-2030 (USD MILLION)
- TABLE 73 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2031-2035 (USD MILLION)
- TABLE 74 UP TO 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 75 UP TO 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 76 UP TO 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 77 UP TO 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 78 UP TO 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 79 UP TO 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 80 ABOVE 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 81 ABOVE 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 82 ABOVE 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 83 ABOVE 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 84 ABOVE 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 85 ABOVE 400 KWH: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 86 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2022-2025 (UNITS)
- TABLE 87 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2026-2030 (UNITS)
- TABLE 88 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2031-2035 (UNITS)
- TABLE 89 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2022-2025 (USD MILLION)
- TABLE 90 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2026-2030 (USD MILLION)
- TABLE 91 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2031-2035 (USD MILLION)
- TABLE 92 NMC BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 93 NMC BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 94 NMC BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 95 NMC BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 96 NMC BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 97 NMC BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 98 LFP BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 99 LFP BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 100 LFP BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 101 LFP BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 102 LFP BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 103 LFP BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 104 NCA BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 105 NCA BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 106 NCA BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 107 NCA BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 108 NCA BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 109 NCA BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 110 OTHER BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 111 OTHER BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 112 OTHER BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 113 OTHER BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 114 OTHER BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 115 OTHER BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 116 ELECTRIC BUSES MARKET, BY COMPONENT, 2022-2025 (UNITS)
- TABLE 117 ELECTRIC BUSES MARKET, BY COMPONENT, 2026-2030 (UNITS)
- TABLE 118 ELECTRIC BUSES MARKET, BY COMPONENT, 2031-2035 (UNITS)
- TABLE 119 ELECTRIC BUSES MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 120 ELECTRIC BUSES MARKET, BY COMPONENT, 2026-2030 (USD MILLION)
- TABLE 121 ELECTRIC BUSES MARKET, BY COMPONENT, 2031-2035 (USD MILLION)
- TABLE 122 MOTORS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 123 MOTORS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 124 MOTORS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 125 MOTORS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 126 MOTORS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 127 MOTORS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 128 BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 129 BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 130 BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 131 BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 132 BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 133 BATTERIES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 134 FUEL CELL STACKS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 135 FUEL CELL STACKS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 136 FUEL CELL STACKS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 137 FUEL CELL STACKS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 138 FUEL CELL STACKS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 139 FUEL CELL STACKS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 140 BATTERY MANAGEMENT SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 141 BATTERY MANAGEMENT SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 142 BATTERY MANAGEMENT SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 143 BATTERY MANAGEMENT SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 144 BATTERY MANAGEMENT SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 145 BATTERY MANAGEMENT SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 146 BATTERY COOLING SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 147 BATTERY COOLING SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 148 BATTERY COOLING SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 149 BATTERY COOLING SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 150 BATTERY COOLING SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 151 BATTERY COOLING SYSTEMS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 152 DC-DC CONVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 153 DC-DC CONVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 154 DC-DC CONVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 155 DC-DC CONVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 156 DC-DC CONVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 157 DC-DC CONVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 158 INVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 159 INVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 160 INVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 161 INVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 162 INVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 163 INVERTERS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 164 AC/DC CHARGERS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 165 AC/DC CHARGERS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 166 AC/DC CHARGERS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 167 AC/DC CHARGERS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 168 AC/DC CHARGERS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 169 AC/DC CHARGERS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 170 EV CONNECTORS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 171 EV CONNECTORS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 172 EV CONNECTORS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 173 EV CONNECTORS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 174 EV CONNECTORS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 175 EV CONNECTORS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 176 ELECTRIC BUSES MARKET, BY CONSUMER, 2022-2025 (UNITS)
- TABLE 177 ELECTRIC BUSES MARKET, BY CONSUMER, 2026-2030 (UNITS)
- TABLE 178 ELECTRIC BUSES MARKET, BY CONSUMER, 2031-2035 (UNITS)
- TABLE 179 ELECTRIC BUSES MARKET, BY CONSUMER, 2022-2025 (USD MILLION)
- TABLE 180 ELECTRIC BUSES MARKET, BY CONSUMER, 2026-2030 (USD MILLION)
- TABLE 181 ELECTRIC BUSES MARKET, BY CONSUMER, 2031-2035 (USD MILLION)
- TABLE 182 PRIVATE: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 183 PRIVATE: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 184 PRIVATE: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 185 PRIVATE: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 186 PRIVATE: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 187 PRIVATE: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 188 PUBLIC: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 189 PUBLIC: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 190 PUBLIC: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 191 PUBLIC: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 192 PUBLIC: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 193 PUBLIC: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 194 KEY SUPPLIERS OF CENTRAL MOTOR SYSTEMS FOR ELECTRIC BUSES
- TABLE 195 KEY INTEGRATED E-AXLE SUPPLIERS TO ELECTRIC-BUS OEMS
- TABLE 196 KEY INTEGRATED HUB/IN-WHEEL MOTOR SUPPLIERS TO ELECTRIC-BUSES OEMS
- TABLE 197 ELECTRIC BUSES MARKET, BY GVW, 2022-2025 (UNITS)
- TABLE 198 ELECTRIC BUSES MARKET, BY GVW, 2026-2030 (UNITS)
- TABLE 199 ELECTRIC BUSES MARKET, BY GVW, 2031-2035 (UNITS)
- TABLE 200 ELECTRIC BUSES MARKET, BY GVW, 2022-2025 (USD MILLION)
- TABLE 201 ELECTRIC BUSES MARKET, BY GVW, 2026-2030 (USD MILLION)
- TABLE 202 ELECTRIC BUSES MARKET, BY GVW, 2031-2035 (USD MILLION)
- TABLE 203 UP TO 10 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 204 UP TO 10 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 205 UP TO 10 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 206 UP TO 10 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 207 UP TO 10 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 208 UP TO 10 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 209 10 - 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 210 10 - 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 211 10 - 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 212 10 - 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 213 10 - 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 214 10 - 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 215 ABOVE 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 216 ABOVE 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 217 ABOVE 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 218 ABOVE 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 219 ABOVE 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 220 ABOVE 20 TONNES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 221 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2022-2025 (UNITS)
- TABLE 222 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2026-2030 (UNITS)
- TABLE 223 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2031-2035 (UNITS)
- TABLE 224 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2022-2025 (USD MILLION)
- TABLE 225 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2026-2030 (USD MILLION)
- TABLE 226 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2031-2035 (USD MILLION)
- TABLE 227 LESS THAN 9 M: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 228 LESS THAN 9 M: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 229 LESS THAN 9 M: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 230 LESS THAN 9 M: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 231 LESS THAN 9 M: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 232 LESS THAN 9 M: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 233 9-14 M: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 234 9-14 M: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 235 9-14 M: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 236 9-14 M: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 237 9-14 M: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 238 9-14 M: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 239 MORE THAN 14 M: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 240 MORE THAN 14 M: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 241 MORE THAN 14 M: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 242 MORE THAN 14 M: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 243 MORE THAN 14 M: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 244 MORE THAN 14 M: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 245 SEMI-AUTONOMOUS ELECTRIC BUS MODELS AND THEIR FEATURES, 2026
- TABLE 246 AUTONOMOUS ELECTRIC BUS MODELS AND THEIR FEATURES, 2026
- TABLE 247 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2022-2025 (UNITS)
- TABLE 248 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2026-2030 (UNITS)
- TABLE 249 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2031-2035 (UNITS)
- TABLE 250 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2022-2025 (USD MILLION)
- TABLE 251 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2026-2030 (USD MILLION)
- TABLE 252 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2031-2035 (USD MILLION)
- TABLE 253 UP TO 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 254 UP TO 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 255 UP TO 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 256 UP TO 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 257 UP TO 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 258 UP TO 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 259 ABOVE 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 260 ABOVE 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 261 ABOVE 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 262 ABOVE 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 263 ABOVE 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 264 ABOVE 250 KW: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 265 ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 266 ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 267 ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 268 ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 269 ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 270 ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION
- TABLE 271 BATTERY ELECTRIC BUSES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 272 BATTERY ELECTRIC BUSES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 273 BATTERY ELECTRIC BUSES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 274 BATTERY ELECTRIC BUSES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 275 BATTERY ELECTRIC BUSES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 276 BATTERY ELECTRIC BUSES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 277 FUEL CELL ELECTRIC VEHICLE: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 278 FUEL CELL ELECTRIC VEHICLE: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 279 FUEL CELL ELECTRIC VEHICLE: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 280 FUEL CELL ELECTRIC VEHICLE: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 281 FUEL CELL ELECTRIC VEHICLE: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 282 FUEL CELL ELECTRIC VEHICLE: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 283 ELECTRIC BUSES MARKET, BY RANGE, 2022-2025 (UNITS)
- TABLE 284 ELECTRIC BUSES MARKET, BY RANGE, 2026-2030 (UNITS)
- TABLE 285 ELECTRIC BUSES MARKET, BY RANGE, 2031-2035 (UNITS)
- TABLE 286 ELECTRIC BUSES MARKET, BY RANGE, 2022-2025 (USD MILLION)
- TABLE 287 ELECTRIC BUSES MARKET, BY RANGE, 2026-2030 (USD MILLION)
- TABLE 288 ELECTRIC BUSES MARKET, BY RANGE, 2031-2035 (USD MILLION)
- TABLE 289 UP TO 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 290 UP TO 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 291 UP TO 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 292 UP TO 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 293 UP TO 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 294 UP TO 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 295 ABOVE 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 296 ABOVE 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 297 ABOVE 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 298 ABOVE 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 299 ABOVE 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 300 ABOVE 300 MILES: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 301 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2022-2025 (UNITS)
- TABLE 302 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2026-2030 (UNITS)
- TABLE 303 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2031-2035 (UNITS)
- TABLE 304 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2022-2025 (USD MILLION)
- TABLE 305 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2026-2030 (USD MILLION)
- TABLE 306 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2031-2035 (USD MILLION)
- TABLE 307 UP TO 40 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 308 UP TO 40 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 309 UP TO 40 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 310 UP TO 40 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 311 UP TO 40 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 312 UP TO 40 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 313 40 -70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 314 40 -70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 315 40 -70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 316 40 -70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 317 40 -70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 318 40 -70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 319 ABOVE 70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 320 ABOVE 70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 321 ABOVE 70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 322 ABOVE 70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 323 ABOVE 70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 324 ABOVE 70 SEATS: ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 325 ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 326 ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (UNITS)
- TABLE 327 ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (UNITS)
- TABLE 328 ELECTRIC BUSES MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 329 ELECTRIC BUSES MARKET, BY REGION, 2026-2030 (USD MILLION)
- TABLE 330 ELECTRIC BUSES MARKET, BY REGION, 2031-2035 (USD MILLION)
- TABLE 331 ASIA PACIFIC: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (UNITS)
- TABLE 332 ASIA PACIFIC: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (UNITS)
- TABLE 333 ASIA PACIFIC: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (UNITS)
- TABLE 334 ASIA PACIFIC: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 335 ASIA PACIFIC: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (USD MILLION)
- TABLE 336 ASIA PACIFIC: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (USD MILLION)
- TABLE 337 CHINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 338 CHINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 339 CHINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 340 CHINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 341 CHINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 342 CHINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 343 JAPAN: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 344 JAPAN: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 345 JAPAN: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 346 JAPAN: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 347 JAPAN: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 348 JAPAN: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 349 INDIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 350 INDIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 351 INDIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 352 INDIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 353 INDIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 354 INDIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 355 SOUTH KOREA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 356 SOUTH KOREA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 357 SOUTH KOREA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 358 SOUTH KOREA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 359 SOUTH KOREA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 360 SOUTH KOREA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 361 SINGAPORE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 362 SINGAPORE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 363 SINGAPORE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 364 SINGAPORE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 365 SINGAPORE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 366 SINGAPORE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 367 INDONESIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 368 INDONESIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 369 INDONESIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 370 INDONESIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 371 INDONESIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 372 INDONESIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 373 AUSTRALIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 374 AUSTRALIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 375 AUSTRALIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 376 AUSTRALIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 377 AUSTRALIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 378 AUSTRALIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 379 EUROPE: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (UNITS)
- TABLE 380 EUROPE: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (UNITS)
- TABLE 381 EUROPE: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (UNITS)
- TABLE 382 EUROPE: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 383 EUROPE: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (USD MILLION)
- TABLE 384 EUROPE: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (USD MILLION)
- TABLE 385 FRANCE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 386 FRANCE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 387 FRANCE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 388 FRANCE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 389 FRANCE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 390 FRANCE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 391 GERMANY: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 392 GERMANY: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 393 GERMANY: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 394 GERMANY: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 395 GERMANY: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 396 GERMANY: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 397 SPAIN: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 398 SPAIN: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 399 SPAIN: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 400 SPAIN: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 401 SPAIN: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 402 SPAIN: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 403 ITALY: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 404 ITALY: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 405 ITALY: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 406 ITALY: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 407 ITALY: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 408 ITALY: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 409 NORWAY: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 410 NORWAY: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 411 NORWAY: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 412 NORWAY: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 413 NORWAY: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 414 NORWAY: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 415 SWEDEN: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 416 SWEDEN: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 417 SWEDEN: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 418 SWEDEN: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 419 SWEDEN: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 420 SWEDEN: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 421 DENMARK: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 422 DENMARK: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 423 DENMARK: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 424 DENMARK: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 425 DENMARK: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 426 DENMARK: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 427 NETHERLANDS: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 428 NETHERLANDS ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 429 NETHERLANDS: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 430 NETHERLANDS: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 431 NETHERLANDS: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 432 NETHERLANDS: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 433 BELGIUM: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 434 BELGIUM: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 435 BELGIUM: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 436 BELGIUM: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 437 BELGIUM: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 438 BELGIUM: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 439 UK: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 440 UK: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 441 UK: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 442 UK: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 443 UK: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 444 UK: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 445 FINLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 446 FINLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 447 FINLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 448 FINLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 449 FINLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 450 FINLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 451 POLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 452 POLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 453 POLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 454 POLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 455 POLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 456 POLAND: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 457 NORTH AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (UNITS)
- TABLE 458 NORTH AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (UNITS)
- TABLE 459 NORTH AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (UNITS)
- TABLE 460 NORTH AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 461 NORTH AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (USD MILLION)
- TABLE 462 NORTH AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (USD MILLION)
- TABLE 463 US: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 464 US: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 465 US: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 466 US: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 467 US: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 468 US: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 469 CANADA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 470 CANADA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 471 CANADA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 472 CANADA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 473 CANADA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 474 CANADA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 475 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (UNITS)
- TABLE 476 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (UNITS)
- TABLE 477 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (UNITS)
- TABLE 478 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 479 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (USD MILLION)
- TABLE 480 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (USD MILLION)
- TABLE 481 ARGENTINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 482 ARGENTINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 483 ARGENTINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 484 ARGENTINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 485 ARGENTINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 486 ARGENTINA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 487 BRAZIL: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 488 BRAZIL ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 489 BRAZIL: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 490 BRAZIL: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 491 BRAZIL: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 492 BRAZIL: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 493 CHILE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 494 CHILE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 495 CHILE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 496 CHILE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 497 CHILE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 498 CHILE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 499 MEXICO: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 500 MEXICO: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 501 MEXICO: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 502 MEXICO: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 503 MEXICO: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 504 MEXICO: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 505 COLOMBIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 506 COLOMBIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 507 COLOMBIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 508 COLOMBIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 509 COLOMBIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 510 COLOMBIA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 511 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (UNITS)
- TABLE 512 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (UNITS)
- TABLE 513 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (UNITS)
- TABLE 514 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 515 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026-2030 (USD MILLION)
- TABLE 516 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2031-2035 (USD MILLION)
- TABLE 517 SOUTH AFRICA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 518 SOUTH AFRICA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 519 SOUTH AFRICA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 520 SOUTH AFRICA: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 521 SOUTH AFRICA: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 522 SOUTH AFRICA: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 523 UAE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 524 UAE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 525 UAE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 526 UAE: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 527 UAE: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 528 UAE: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 529 QATAR: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (UNITS)
- TABLE 530 QATAR: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (UNITS)
- TABLE 531 QATAR: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (UNITS)
- TABLE 532 QATAR: ELECTRIC BUSES MARKET, BY PROPULSION, 2022-2025 (USD MILLION)
- TABLE 533 QATAR: ELECTRIC BUSES MARKET, BY PROPULSION, 2026-2030 (USD MILLION)
- TABLE 534 QATAR: ELECTRIC BUSES MARKET, BY PROPULSION, 2031-2035 (USD MILLION)
- TABLE 535 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2022-2025
- TABLE 536 ASIAN ELECTRIC BUS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 537 EUROPEAN ELECTRIC BUS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 538 NORTH AMERICAN ELECTRIC BUS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 539 ELECTRIC BUS MARKET: CONSUMER FOOTPRINT, 2025
- TABLE 540 ELECTRIC BUS MARKET: REGION FOOTPRINT, 2025
- TABLE 541 ELECTRIC BUS MARKET: APPLICATION FOOTPRINT, 2025
- TABLE 542 ELECTRIC BUS MARKET: PROPULSION FOOTPRINT, 2025
- TABLE 543 ELECTRIC BUS MARKET: LIST OF KEY STARTUPS/SMES
- TABLE 544 COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 545 ELECTRIC BUS MARKET: PRODUCT LAUNCHES/ENHANCEMENTS/DEVELOPMENTS, JANUARY 2025-JULY 2026
- TABLE 546 ELECTRIC BUS MARKET: DEALS, AUGUST 2022-MARCH 2025
- TABLE 547 ELECTRIC BUS MARKET: EXPANSIONS, JUNE 2021-JULY 2025
- TABLE 548 ELECTRIC BUS MARKET: OTHERS, MARCH 2025-JULY 2025
- TABLE 549 BYD COMPANY LTD.: COMPANY OVERVIEW
- TABLE 550 BYD COMPANY LTD.: PRODUCTS/SOLUTIONS OFFERED
- TABLE 551 BYD COMPANY LTD.: PRODUCT LAUNCHES
- TABLE 552 BYD COMPANY LTD.: DEALS
- TABLE 553 BYD COMPANY LTD.: EXPANSIONS
- TABLE 554 BYD COMPANY LTD.: OTHERS
- TABLE 555 YUTONG BUS CO., LTD.: COMPANY OVERVIEW
- TABLE 556 YUTONG BUS CO., LTD.: PRODUCTS/SOLUTIONS OFFERED
- TABLE 557 YUTONG BUS CO., LTD.: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 558 YUTONG BUS CO., LTD.: DEALS
- TABLE 559 YUTONG BUS CO., LTD.: EXPANSIONS
- TABLE 560 YUTONG BUS CO., LTD.: OTHERS
- TABLE 561 ZHEJIANG GEELY HOLDING GROUP: COMPANY OVERVIEW
- TABLE 562 ZHEJIANG GEELY HOLDING GROUP: PRODUCTS/SOLUTIONS OFFERED
- TABLE 563 ZHEJIANG GEELY HOLDING GROUP: PRODUCT LAUNCHES
- TABLE 564 ZHEJIANG GEELY HOLDING GROUP: DEALS
- TABLE 565 ZHEJIANG GEELY HOLDING GROUP: EXPANSIONS
- TABLE 566 ZHEJIANG GEELY HOLDING GROUP: OTHERS
- TABLE 567 DAIMLER TRUCK AG: COMPANY OVERVIEW
- TABLE 568 DAIMLER TRUCK AG: PRODUCTS/SOLUTIONS OFFERED
- TABLE 569 DAIMLER TRUCK AG: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 570 DAIMLER TRUCK AG: DEALS
- TABLE 571 DAIMLER TRUCK AG: EXPANSIONS
- TABLE 572 DAIMLER TRUCK AG: OTHERS
- TABLE 573 NFI GROUP: COMPANY OVERVIEW
- TABLE 574 NFI GROUP: PRODUCTS/SOLUTIONS OFFERED
- TABLE 575 NFI GROUP: PRODUCT LAUNCHES/DEVELOPMENTS/ENHANCEMENTS
- TABLE 576 NFI GROUP: DEALS
- TABLE 577 NFI GROUP: EXPANSIONS
- TABLE 578 NFI GROUP: OTHERS
- TABLE 579 AB VOLVO: COMPANY OVERVIEW
- TABLE 580 AB VOLVO: PRODUCTS/SOLUTIONS OFFERED
- TABLE 581 AB VOLVO: PRODUCT LAUNCHES
- TABLE 582 AB VOLVO: DEALS
- TABLE 583 AB VOLVO: EXPANSIONS
- TABLE 584 AB VOLVO: OTHERS
- TABLE 585 CAF (SOLARIS BUS & COACH SP. Z O.O.): COMPANY OVERVIEW
- TABLE 586 CAF (SOLARIS BUS & COACH SP. Z O.O.): PRODUCTS/SOLUTIONS OFFERED
- TABLE 587 CAF (SOLARIS BUS & COACH SP. Z O.O.): PRODUCT LAUNCHES
- TABLE 588 CAF (SOLARIS BUS & COACH SP. Z O.O.): OTHERS
- TABLE 589 ZHONGTONG BUS HOLDING CO., LTD.: COMPANY OVERVIEW
- TABLE 590 ZHONGTONG BUS HOLDING CO., LTD.: PRODUCTS/SOLUTIONS OFFERED
- TABLE 591 ZHONGTONG BUS HOLDING CO., LTD.: PRODUCT LAUNCHES
- TABLE 592 ZHONGTONG BUS HOLDING CO., LTD.: EXPANSIONS
- TABLE 593 ZHONGTONG BUS HOLDING CO., LTD.: OTHERS
- TABLE 594 CRRC CORPORATION LIMITED: COMPANY OVERVIEW
- TABLE 595 CRRC CORPORATION LIMITED: PRODUCTS/SOLUTIONS OFFERED
- TABLE 596 CRRC CORPORATION LIMITED: PRODUCT LAUNCHES
- TABLE 597 CRRC CORPORATION LIMITED: DEALS
- TABLE 598 CRRC CORPORATION LIMITED: EXPANSIONS
- TABLE 599 CRRC CORPORATION LIMITED: OTHERS
- TABLE 600 VDL GROEP: COMPANY OVERVIEW
- TABLE 601 VDL GROEP: PRODUCTS/SOLUTIONS OFFERED
- TABLE 602 VDL GROEP: PRODUCT LAUNCHES
- TABLE 603 VDL GROEP: DEALS
- TABLE 604 VDL GROEP: EXPANSIONS
- TABLE 605 VDL GROEP: OTHERS
- TABLE 606 EBUSCO: COMPANY OVERVIEW
- TABLE 607 EBUSCO: PRODUCTS/SOLUTIONS OFFERED
- TABLE 608 EBUSCO: PRODUCT ENHANCEMENTS
- TABLE 609 EBUSCO: DEALS
- TABLE 610 EBUSCO: OTHERS
- TABLE 611 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.: COMPANY OVERVIEW
- TABLE 612 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.: PRODUCTS/SOLUTIONS OFFERED
- TABLE 613 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.: PRODUCT LAUNCHES
- TABLE 614 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD: DEALS
- TABLE 615 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD: EXPANSIONS
- TABLE 616 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.: OTHERS
List of Figures
- FIGURE 1 MARKET SCENARIO
- FIGURE 2 GLOBAL ELECTRIC BUSES MARKET SCENARIO, 2022-2035
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN ELECTRIC BUSES MARKET
- FIGURE 4 DISRUPTIONS INFLUENCING GROWTH OF ELECTRIC BUSES MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS IN ELECTRIC BUSES MARKET
- FIGURE 6 NORTH AMERICA TO BE LEADING MARKET DURING FORECAST PERIOD
- FIGURE 7 INCREASING DEMAND FOR SUSTAINABLE TRANSPORT SOLUTIONS AND GREEN TRANSPORTATION TO DRIVE MARKET
- FIGURE 8 BATTERY ELECTRIC BUSES TO DOMINATE AS FALLING BATTERY COSTS AND MATURE CHARGING ECOSYSTEMS IMPROVE ROUTE-LEVEL ECONOMICS
- FIGURE 9 ELECTRIC BUSES UP TO 300-MILE RANGE TO DOMINATE AS THEY OFFER AN OPTIMAL BALANCE OF RANGE, BATTERY COST, AND URBAN/REGIONAL ROUTE REQUIREMENTS
- FIGURE 10 BATTERIES HOLD THE LARGEST MARKET SHARE IN ELECTRIC BUSES BECAUSE THEY ARE THE MOST EXPENSIVE AND TECHNOLOGICALLY COMPLEX PART OF THE VEHICLE.
- FIGURE 11 PUBLIC SEGMENT DOMIANTES THE SEGMENT AS ELECTRIC PUBLIC BUSES ARE FUNDED WITH GREE SUBSIDIES AND SUPPORTED BY DECARBONISATION MANDATES
- FIGURE 12 UP TO 400 KWH TO BE DOMINANT SEGMENT AS THEY ARE MOSTLY OFFERED IN TRANSIT BUSES
- FIGURE 13 LFP DOMAINTED THE MARKET AS THEY ARE 20% TO 30% CHEAPER TO MANUFACTURE WHICH HELPS LOWERING THE HIGHER UPFRONT COST.
- FIGURE 14 CITY/TRANSIT BUSES TO BE LARGEST SEGMENT AS THEY HAVE PREDICTABLE, SHORT-DISTANCE ROUTES THAT MAKE THEM PERFECTLY SUITED FOR BATTERY ELECTRIFICATION.
- FIGURE 15 UP TO 250 KW TO BE DOMINANT SEGMENT AS THEES ARE USED MOSTLY IN CITY TRANSIT WHICH DOES NOT NEED HIGH TOP SPEEDS
- FIGURE 16 9-14 M TO BE LARGEST SEGMENT IN 2035
- FIGURE 17 40-70 SEATS TO BE LARGEST SEGMENT IN 2035
- FIGURE 18 10-20 TONNES TO BE LARGEST SEGMENT DURING FORECAST PERIOD
- FIGURE 19 ASIA PACIFIC TO LEAD ELECTRIC BUSES MARKET IN 2026
- FIGURE 20 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN CAR DETAILING PRODUCTS MARKET
- FIGURE 21 ELECTRIC BUSES MARKET SUPPLY CHAIN
- FIGURE 22 ELECTRIC BUSES MARKET ECOSYSTEM MAPPING
- FIGURE 23 IMPORT SCENARIO FOR HS CODE 870240-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021-2025 (USD THOUSAND)
- FIGURE 24 EXPORT SCENARIO FOR HS CODE 340220-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021-2025 (USD THOUSAND)
- FIGURE 25 TRENDS INFLUENCING ELECTRIC BUSES MARKET
- FIGURE 26 INVESTMENT AND FUNDING SCENARIO, 2022-2026
- FIGURE 27 TOTAL COST OF OWNERSHIP FOR DIESEL BUSES, 2026
- FIGURE 28 TOTAL COST OF OWNERSHIP FOR ELECTRIC BUSES, 2026
- FIGURE 29 BILL OF MATERIALS ANALYSIS
- FIGURE 30 ELECTRIC AND ICE BUS MODELS: BUS LENGTH VS. NUMBER OF SEATS
- FIGURE 31 ELECTRIC BUS MODELS: BUS LENGTH VS. NUMBER OF SEATS
- FIGURE 32 ELECTRIC BUS - BATTERY CAPACITY VS. DRIVE RANGE VS. PAX FOR MERCEDES-BENZ E-CITARO
- FIGURE 33 KEY BUYING CRITERIA FOR ELECTRIC BUSES, BY PROPULSION
- FIGURE 34 GOVERNMENT TARGETS FOR 100% ZERO-EMISSION BUS SALES
- FIGURE 35 PATENTS GRANTED, 2016-2026
- FIGURE 36 ELECTRIC BUSES MARKET, BY APPLICATION, 2026 VS. 2035 (USD MILLION)
- FIGURE 37 ELECTRIC BUSES MARKET, BY BATTERY CAPACITY, 2026 VS. 2035 (USD MILLION)
- FIGURE 38 ELECTRIC BUSES MARKET, BY BATTERY TYPE, 2026 VS. 2035 (USD MILLION)
- FIGURE 39 ELECTRIC BUSES MARKET, BY COMPONENT, 2026 VS. 2035 (USD MILLION)
- FIGURE 40 ELECTRIC BUSES MARKET, BY CONSUMER, 2026 VS. 2035 (USD MILLION)
- FIGURE 41 ELECTRIC BUSES MARKET, BY GROSS VEHICLE WEIGHT, 2026 VS. 2035 (UNITS)
- FIGURE 42 ELECTRIC BUSES MARKET, BY LENGTH OF BUSES, 2026 VS. 2035 (USD MILLION)
- FIGURE 43 ELECTRIC BUSES MARKET, BY POWER OUTPUT, 2026 VS. 2035 (USD MILLION)
- FIGURE 44 ELECTRIC BUSES MARKET, BY PROPULSION, 2026 VS. 2035 (USD MILLION)
- FIGURE 45 ELECTRIC BUSES MARKET, BY RANGE, 2026 VS. 2035 (USD MILLION)
- FIGURE 46 ELECTRIC BUSES MARKET: RANGE VS. APPLICATION
- FIGURE 47 ELECTRIC BUSES MARKET, BY SEATING CAPACITY, 2026 VS. 2035 (USD MILLION)
- FIGURE 48 ELECTRIC BUSES MARKET, BY REGION, 2025 VS. 2035 (USD MILLION)
- FIGURE 49 ASIA PACIFIC: ELECTRIC BUSES MARKET SNAPSHOT
- FIGURE 50 EUROPE: ELECTRIC BUSES MARKET SNAPSHOT, BY COUNTRY (USD MILLION)
- FIGURE 51 NORTH AMERICA: ELECTRIC BUSES MARKET SNAPSHOT
- FIGURE 52 LATIN AMERICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026 VS. 2035 (USD MILLION)
- FIGURE 53 MIDDLE EAST & AFRICA: ELECTRIC BUSES MARKET, BY COUNTRY, 2026 VS. 2035 (USD MILLION)
- FIGURE 54 REVENUE ANALYSIS FOR TOP LISTED PLAYERS, 2021-2025
- FIGURE 55 ASIA: MARKET SHARE OF KEY PLAYERS, 2025
- FIGURE 56 EUROPE: MARKET SHARE OF KEY PLAYERS, 2025
- FIGURE 57 NORTH AMERICA: MARKET SHARE OF KEY PLAYERS, 2025
- FIGURE 58 COMPANY VALUATION FOR KEY PLAYERS, 2025 (USD BILLION)
- FIGURE 59 EV/EBITDA OF KEY PLAYERS, 2025
- FIGURE 60 BRAND PRODUCT COMPARISON
- FIGURE 61 ELECTRIC BUS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 62 ELECTRIC BUS MARKET: COMPANY FOOTPRINT, 2025
- FIGURE 63 ELECTRIC BUS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 64 BYD COMPANY LTD.: COMPANY SNAPSHOT
- FIGURE 65 YUTONG BUS CO., LTD.: COMPANY SNAPSHOT
- FIGURE 66 ZHEJIANG GEELY HOLDING GROUP: COMPANY SNAPSHOT
- FIGURE 67 DAIMLER TRUCK AG: COMPANY SNAPSHOT
- FIGURE 68 NFI GROUP: COMPANY SNAPSHOT
- FIGURE 69 AB VOLVO: COMPANY SNAPSHOT
- FIGURE 70 CAF (SOLARIS BUS & COACH SP. Z O.O.): COMPANY SNAPSHOT
- FIGURE 71 ZHONGTONG BUS HOLDING CO., LTD.: COMPANY SNAPSHOT
- FIGURE 72 CRRC CORPORATION LIMITED: COMPANY SNAPSHOT
- FIGURE 73 VDL GROEP: COMPANY SNAPSHOT
- FIGURE 74 EBUSCO: COMPANY SNAPSHOT
- FIGURE 75 XIAMEN KING LONG INTERNATIONAL TRADING CO., LTD.: COMPANY SNAPSHOT
- FIGURE 76 RESEARCH DESIGN
- FIGURE 77 RESEARCH DESIGN MODEL
- FIGURE 78 BREAKDOWN OF PRIMARY INTERVIEWS
- FIGURE 79 RESEARCH METHODOLOGY: HYPOTHESIS BUILDING
- FIGURE 80 BOTTOM-UP APPROACH
- FIGURE 81 DATA TRIANGULATION
- FIGURE 82 MARKET GROWTH PROJECTIONS FROM DEMAND-SIDE DRIVERS AND OPPORTUNITIES

 2034年電動巴士和公共交通電氣化市場預測-全球分析(按推進方式、巴士類型、電池類型、馬達類型、充電方式、充電地點、充電基礎設施、應用、最終用戶和地區分類)
 燃料電池電動巴士全球市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 燃料電池電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)亞太地區電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)非洲電動巴士:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 公共運輸電氣化市場:按組件、應用、電池類型、全球價值鏈 (GVC)、推進系統、國家和地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 電動微型巴士市場:2026-2032年全球市場預測(按驅動系統、座位數、續航里程、電池容量、應用和最終用戶分類)電動校車市場:按驅動系統、車身長度、電池容量、校車類型、充電方式和最終用戶分類-2026-2032年全球市場預測電動巴士市場:2026-2032年全球市場預測(按推進系統、電池類型、底盤類型、座位數、續航里程、應用和最終用戶分類)