


 |
市場調查報告書
商品編碼
2124178
歐洲施工機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Europe Construction Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
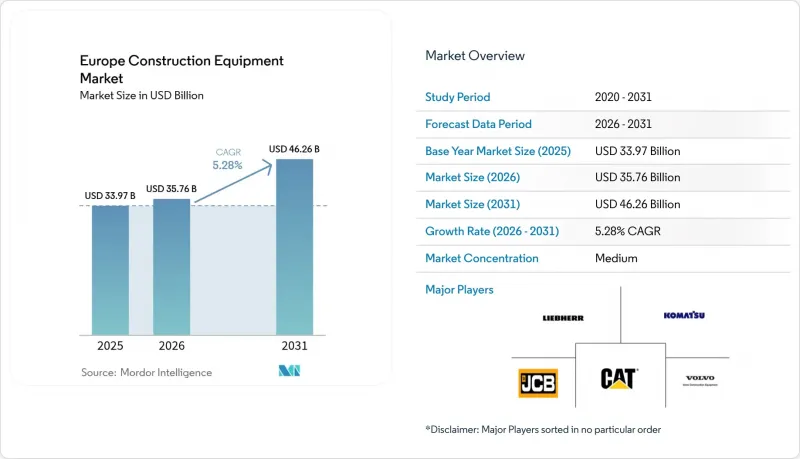
據 Mordor Intelligence 稱,2025 年歐洲施工機械市場價值為 339.7 億美元,預計到 2031 年將達到 462.6 億美元,而 2026 年為 357.6 億美元,預測期(2026-2031 年)的複合年成長率為 5.28%。
本報告按機器類型(起重機、伸縮臂叉裝車等)、動力來源(內燃機、混合動力等)、終端用戶行業(基礎設施和建築、採礦和採石等)、應用領域(土方工程、起重和物料輸送等)以及地區進行細分。市場預測以價值(美元)和數量(台)表示。
歐洲施工機械市場趨勢與洞察
與歐盟綠色交易相關的公共產業計畫
成員國正以前所未有的規模投資於氣候適應基礎設施,將採購週期從18-24個月縮短至最短12個月。受德國預算外資金的影響,2024年實際建築支出略有下降,但2025年已開始小幅成長。這波支出熱潮推動了對挖土機、平地平土機和小型機械的需求,這些設備是安裝可再生能源設施所必需的。為了獲得綠色新政的競標,承包商越來越傾向於選擇符合第五階段排放標準或電動型號的設備,即使這些設備的價格高出10%以上。因此,供應商面臨越來越大的壓力,需要維持更大的庫存緩衝,才能跟上不斷加速的專案進度。
隨著歐洲央行降息週期的開始,預計2025-2026年住宅量將有所復甦。
2025年第一季住宅投資略有回升,這是自2022年以來的首次復甦。抵押房屋抵押貸款核准和建築融資需求正在增強,尤其是在德國,該國在高利率時期累積的住宅需求持續成長。由於新建住宅建設活動主要由都市區改造項目主導,小型挖土機、小型裝載機和加長型堆高機從中受益最大。此外,信貸環境的寬鬆使得小規模建築公司能夠重新進入設備融資市場,從而擴大了入門級電動機械的基本客群。
租賃車隊的過剩導致新車的平均售價(ASP)下降。
2021年至2022年間激進的車隊擴張導致2024年租賃運轉率僅63.4%,且租賃價格較去年同期下降。租賃需求成長疲軟迫使企業削減車隊支出,造成庫存過剩6至9個月。製造商正透過延長貸款期限和提供服務抵扣來應對,但這些措施擠壓了利潤空間,並延遲了用於技術創新的預算撥款。
細分市場分析
預計到2025年,挖土機將佔據歐洲施工機械市場44.78%的佔有率,並預計在2031年之前以5.32%的複合年成長率成長,超過歐洲施工機械市場的整體成長速度。伸縮臂堆高機的成長緊接在挖土機之後,這主要得益於倉庫自動化專案對高空精準定位的需求。起重機的銷售量保持穩定,但受到低價進口產品的衝擊,利潤率面臨壓力;而平地平土機受益於運輸走廊投資的增加。
電氣化正在重塑各細分領域的競爭格局。利勃海爾L 507 E輪式裝載機實現了16小時的運作,展現出與柴油動力機械相媲美的性能。儘管裝載機和後鏟市場面臨中國OEM廠商的激烈價格競爭,但由於複雜的安全認證,專用隧道掘進設備仍保持較高的進入門檻。建築公司越來越傾向於選擇多功能附件,這些配件可以將挖掘機改裝成拆除、回收或整平工具,這推高了單機平均售價,並將買家綁定到他們自己的液壓介面上。
即使到了2025年,內燃機仍將佔據歐洲施工機械市場80.66%的佔有率,但電池電動設備的成長速度最快,年複合成長率達5.39%。混合動力系統克服了充電基礎設施不足地區的局限性,但就整體擁有成本而言,對於高運轉率的工地來說,純電動設備更具優勢。挪威和荷蘭地方政府的法規限制了公共工程項目中柴油設備的使用,這導致部分地區電動設備的訂單激增,使得生產週期超過了工廠的交貨週期。
雖然電動機械的初始投資成本大約高出五分之一,但一家每年運作1500小時的建築公司可以透過節省燃料和維護成本,在四年內收回成本差額。氫燃料電池目前仍屬於小眾產品,但利勃海爾公司開發的一款氫動力測試挖掘機因其在電網不穩定的偏遠風電場的應用前景而備受關注。製造商現在必須同時管理柴油和電動兩種產品平台,這給研發預算和供應鏈帶來了壓力。鋰和稀土元素的價格波動使電池採購更加複雜,並推高了零件成本。這些限制因素導致歐洲施工機械市場的預期複合年成長率下降了0.5個百分點。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 與歐盟綠色新政相關的公共產業計畫
- 隨著歐洲央行降息週期的開始,預計2025-2026年住宅量將有所復甦。
- 加速車輛電氣化進程,以滿足第五/六階段二氧化碳和氮氧化物排放上限要求
- 都市區改造區域對小型施工機械的需求日益成長。
- OEM廠商主導的訂閱服務和車載資訊服務方案正在提升售後市場收入。
- 隨著倉庫自動化程度的提高,電池驅動加長型堆高機的使用量正在迅速增加。
- 市場限制因素
- 租賃車輛供應過剩導致新車平均售價下降。
- 合格操作人員短缺導致專案工期延長。
- 鋰和稀土元素的價格波動正在影響電動車設備的物料清單 (BOM) 成本。
- 從中國進口的產品獲得CE標誌/型式認證的進程仍然緩慢。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按機器類型
- 起重機
- 伸縮臂堆高機
- 挖土機
- 裝載機和後鏟
- 平土機機
- 其他
- 透過電源
- 內燃機
- 混合
- 電池式電動車
- 氫燃料電池
- 按最終用戶行業分類
- 基礎設施和建築
- 採礦和採石
- 石油和天然氣
- 製造/倉儲業
- 農業和林業
- 公共產業及可再生能源
- 透過使用
- 土木工程
- 物料輸送
- 挖掘和拆除
- 道路建設和鋪路
- 隧道建設
- 回收和廢棄物管理
- 國家
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 比利時
- 波蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- AB Volvo(Volvo CE)
- Liebherr Group
- CNH Industrial NV
- Komatsu Ltd.
- JCB Ltd.
- Hitachi Construction Machinery
- Deere & Company
- Sandvik AB
- Manitou Group
- Atlas Copco AB
- XCMG Europe
- Sany Europe GmbH
- Doosan Bobcat EMEA
- Wirtgen Group
- Kubota Corp.
- Terex Corp.
- Bomag GmbH
- Wacker Neuson SE
- Hyundai Construction Equipment Europe
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe construction equipment market size was valued at USD 33.97 billion in 2025 and estimated to grow from USD 35.76 billion in 2026 to reach USD 46.26 billion by 2031, at a CAGR of 5.28% during the forecast period (2026-2031).
This report is Segmented by Machinery Type (Cranes, Telescopic Handler, and More), Power Source (Internal-Combustion, Hybrid, and More), End-User Industry (Infrastructure & Construction, Mining & Quarrying, and More), Application (Earthmoving, Lifting & Material Handling, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Europe Construction Equipment Market Trends and Insights
EU Green Deal-Linked Public-Works Pipeline
Member states are channeling unprecedented capital into climate-resilient infrastructure, compressing procurement cycles from 18-24 months to as few as 12 months. Germany's off-budget fund is already lifting real construction outlays by minimal in 2025 after a slight contraction in 2024. This spending wave boosts demand for excavators, motor graders, and compact machines needed for renewable-energy installations. Contractors increasingly favor Stage V-compliant or electric models, even when premiums exceed more than one-tenth, to secure eligibility for Green Deal tenders. Suppliers therefore face mounting pressure to maintain higher inventory buffers that match accelerated project timelines.
Recovery Of Residential Starts As Ecb Rate-Cut Cycle Begins (2025-26)
Housing investment turned positive slightly in Q1 2025, the first upturn since 2022. Mortgage approvals and construction loan demand have strengthened, especially in Germany, where pent-up housing needs accumulated during the high-rate period. Compact excavators, mini loaders, and telehandlers benefit the most because urban infill projects dominate new housing activity. Easier credit is also pulling small contractors back into the equipment-financing market, widening the customer base for entry-level electric machines.
Rental-Fleet Oversupply Suppressing New-Unit ASPs
Aggressive fleet expansion during 2021-2022 left rental utilization at only 63.4% in 2024, pushing rental rates down on year over year. Sluggish rental growth has forced companies to cut fleet spending by minimal, creating channel inventory bulges of six to nine months. Manufacturers respond with longer financing terms and service credits, but these steps erode margins and slow innovation budgets.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Fleet Electrification To Meet Stage V/Vi Co2 & Nox Caps
- Growing Demand For Compact Equipment On Urban Infill Sites
- Scarcity of Certified Operators Inflating Project Timelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Excavators captured 44.78% of the Europe construction equipment market share in 2025 and are projected to grow at a 5.32% CAGR to 2031, outpacing the overall Europe construction equipment market. Telescopic handlers follow closely in growth, fuelled by warehouse automation projects that demand precision placement at height. Cranes maintain steady volume but see margin pressure from lower-priced imports, while motor graders gain from transport-corridor spending.
Electrification reshapes competitive dynamics within each subcategory. Liebherr's L 507 E wheel loader delivers 16-hour run-time, showing functional parity with diesel units. Loader and backhoe segments face intense price competition from Chinese OEMs, whereas specialized tunneling equipment retains higher entry barriers thanks to complex safety certifications. Contractors increasingly prefer multi-functional attachments that turn excavators into demolition, recycling, or grading tools, boosting average selling price per unit and locking buyers into proprietary hydraulic interfaces.
Internal combustion engines still hold 80.66% of the Europe construction equipment market size in 2025, but battery-electric units are climbing fastest at a 5.39% CAGR. Hybrid drive-trains bridge constraints where charging infrastructure is lacking, yet total cost of ownership advantages favor full electrics on high-utilization sites. Provincial mandates in Norway and the Netherlands restrict diesel equipment on public projects, triggering regional spikes in electric orders that outstrip factory lead times.
Capital costs for electric machines are one-fifth higher, but contractors running 1,500 hours annually recoup premiums in under four years through fuel and maintenance savings. Hydrogen fuel cells remain niche, but Liebherr's pilot hydrogen excavator has sparked interest for use in remote wind farms where grid supply is thin. Manufacturers must now manage dual product platforms-diesel and electric-stretching R&D budgets and supply chains. Battery sourcing is complicated by lithium and rare-earth price swings that raise bills of material, a restraint subtracting 0.5 percentage points from Europe construction equipment market CAGR projections.
Complete Report Scope:
- By Machinery Type
- Cranes
- Telescopic Handler
- Excavator
- Loader and Backhoe
- Motor Graders
- Others
- By Power Source
- Internal-Combustion
- Hybrid
- Battery-Electric
- Hydrogen Fuel-Cell
- By End-user Industry
- Infrastructure & Construction
- Mining & Quarrying
- Oil & Gas
- Manufacturing & Warehousing
- Agriculture & Forestry
- Utilities & Renewable Energy
- By Application
- Earthmoving
- Lifting & Material Handling
- Excavation & Demolition
- Road Building & Paving
- Tunnelling
- Recycling & Waste Management
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Netherlands
- Belgium
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Caterpillar Inc.
- AB Volvo (Volvo CE)
- Liebherr Group
- CNH Industrial N.V.
- Komatsu Ltd.
- JCB Ltd.
- Hitachi Construction Machinery
- Deere & Company
- Sandvik AB
- Manitou Group
- Atlas Copco AB
- XCMG Europe
- Sany Europe GmbH
- Doosan Bobcat EMEA
- Wirtgen Group
- Kubota Corp.
- Terex Corp.
- Bomag GmbH
- Wacker Neuson SE
- Hyundai Construction Equipment Europe
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Green Deal-Linked Public-Works Pipeline
- 4.2.2 Recovery Of Residential Starts As Ecb Rate-Cut Cycle Begins (2025-26)
- 4.2.3 Accelerated Fleet Electrification To Meet Stage V/Vi Co2 & Nox Caps
- 4.2.4 Growing Demand For Compact Equipment On Urban Infill Sites
- 4.2.5 OEM-Led Subscription & Telematics Bundles Boosting Aftermarket Revenue
- 4.2.6 Surge In Battery-Electric Telehandlers For Warehouse-Automation Build-Outs
- 4.3 Market Restraints
- 4.3.1 Rental-Fleet Oversupply Suppressing New-Unit Asps
- 4.3.2 Scarcity Of Certified Operators Inflating Project Timelines
- 4.3.3 Lithium & Rare-Earth Price Volatility Hitting Ev-Equipment Bom Costs
- 4.3.4 Persistent Ce-Mark/Homologation Delays For Chinese Imports
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Machinery Type
- 5.1.1 Cranes
- 5.1.2 Telescopic Handler
- 5.1.3 Excavator
- 5.1.4 Loader and Backhoe
- 5.1.5 Motor Graders
- 5.1.6 Others
- 5.2 By Power Source
- 5.2.1 Internal-Combustion
- 5.2.2 Hybrid
- 5.2.3 Battery-Electric
- 5.2.4 Hydrogen Fuel-Cell
- 5.3 By End-user Industry
- 5.3.1 Infrastructure & Construction
- 5.3.2 Mining & Quarrying
- 5.3.3 Oil & Gas
- 5.3.4 Manufacturing & Warehousing
- 5.3.5 Agriculture & Forestry
- 5.3.6 Utilities & Renewable Energy
- 5.4 By Application
- 5.4.1 Earthmoving
- 5.4.2 Lifting & Material Handling
- 5.4.3 Excavation & Demolition
- 5.4.4 Road Building & Paving
- 5.4.5 Tunnelling
- 5.4.6 Recycling & Waste Management
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Russia
- 5.5.7 Netherlands
- 5.5.8 Belgium
- 5.5.9 Poland
- 5.5.10 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 AB Volvo (Volvo CE)
- 6.4.3 Liebherr Group
- 6.4.4 CNH Industrial N.V.
- 6.4.5 Komatsu Ltd.
- 6.4.6 JCB Ltd.
- 6.4.7 Hitachi Construction Machinery
- 6.4.8 Deere & Company
- 6.4.9 Sandvik AB
- 6.4.10 Manitou Group
- 6.4.11 Atlas Copco AB
- 6.4.12 XCMG Europe
- 6.4.13 Sany Europe GmbH
- 6.4.14 Doosan Bobcat EMEA
- 6.4.15 Wirtgen Group
- 6.4.16 Kubota Corp.
- 6.4.17 Terex Corp.
- 6.4.18 Bomag GmbH
- 6.4.19 Wacker Neuson SE
- 6.4.20 Hyundai Construction Equipment Europe
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 泰國施工機械市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)義大利施工機械市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 2026-2030年全球挖溝機市場
 2026-2030年全球施工機械市場
 2035年前施工機械輪胎市場分析和預測:按類型、產品、技術、組件、應用、材料類型、製程、最終用戶和安裝方法進行分析和預測。對 2035 年前施工機械引擎市場進行分析和預測:按類型、產品、服務、技術、組件、應用、材料類型、製程、最終用戶和功能分類。
 輪式挖溝機市場規模、佔有率和成長分析:按產品類型、動力來源、應用、最終用戶、銷售管道和地區分類-2026-2033年產業預測
 道路堆垛機市場規模、佔有率和成長分析:按產品類型、負載容量、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測中國施工機械市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 施工機械市場-2026-2032年全球市場預測