


 |
市場調查報告書
商品編碼
2122504
行動商業情報:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Mobile Business Intelligence - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,行動商業情報市場在 2026 年的價值將達到 243.5 億美元,從 2025 年的 199.3 億美元成長到 2031 年的 662.8 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 22.18%。
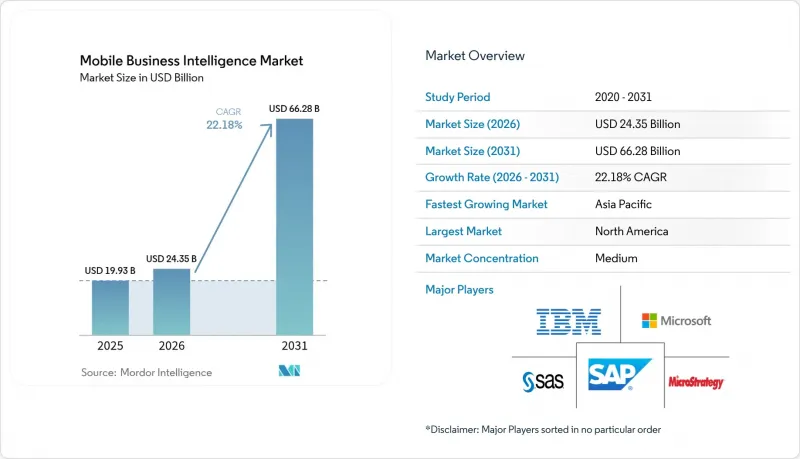
本報告按解決方案(軟體和服務)、組織規模(大型企業和中小企業)、應用(銷售和市場分析、財務和風險分析等)、最終用戶行業(銀行、金融服務和保險 (BFSI)、IT 和電信、醫療保健和生命科學等)以及地區進行細分。市場預測以價值(美元)表示。
全球行動商業情報市場趨勢與洞察
大型企業採用雲端優先移動 BI
大型企業正從本地系統遷移到雲端原生行動 BI,讓全球員工無需 VPN 即可存取儀表板。超過 52,000 家公司正在積極使用 Microsoft Power BI,並將分析功能整合到其 Microsoft 365 工作流程中。這種遷移透過消除伺服器維護需求並允許資源在高峰使用期間彈性擴展,從而降低了總體擁有成本 (TCO)。 SAP Analytics Cloud 也以類似的方式將即時交易資料與行動視覺化連接起來,同時保持嚴格的身份管理。隨著這種模式的日益普及,行動商業情報市場正在蓬勃發展,甚至在以前不願遷移到雲端的受監管行業中也獲得了發展動力。
5G/邊緣部署的快速成長使得即時分析成為可能。
目前,亞太地區七個國家已運作獨立的5G網路,支撐著價值8,800億美元的區域移動經濟,而快速反應的分析能力是該經濟的基石。邊緣運算將處理任務卸載到本機閘道器,使行動儀錶板能夠在毫秒級內更新。這對於工廠的預測性維護警報和零售業的庫存決策至關重要。東京的金融交易部門已經開始利用亞毫秒的資料流,在手持終端機上進行衍生性商品定價。這些例子表明,5G和邊緣運算的結合正在提高行動商業情報市場的利用率。
個人設備持續存在的安全和隱私問題
儘管銷售業績顯著提升,但60%的公司仍認為行動安全是商業智慧(BI)廣泛應用的主要障礙。自備設備辦公室(BYOD)政策導致消費者應用和企業應用混雜,增加了資料外洩的風險,而蘋果公司新推出的隱私保護措施也只能部分緩解此風險。銀行和醫院通常限制行動BI的使用,僅允許在公司配發的設備上使用。儘管加密和生物生物識別登入功能有所改進,但在高價值產業中,行動BI的普及速度仍在放緩。
細分市場分析
軟體仍是主要的收入來源,提供視覺化工具、查詢引擎和管治層,預計到2025年將佔據65.92%的市場佔有率。這些產品構成了大多數企業分析堆疊的基礎,並與身分管理套件、資料倉儲和低程式碼平台整合。然而,由於對部署、客製化和託管營運的需求激增,服務供應商比許可供應商更快地獲得合約。許多客戶現在將大規模語言模型、邊緣部署腳本和零信任控制的微調外包出去,因為他們的內部團隊缺乏這些資源。隨著企業從純粹的軟體支出轉向基於結果的契約,行動商業情報市場服務規模預計將在2031年之前以兩位數的複合年成長率高速成長。
顧問公司將資料工程、使用者培訓和部署後最佳化打包在一起,使客戶能夠在運作上線後立即獲得價值。託管服務合作夥伴簽訂多年契約,負責修復行動應用程式、監控使用情況並改進語義層,從而使業務部門能夠專注於利用洞察而非平台維護。 MicroStrategy 在 Google Cloud Marketplace 上的產品清單清楚地體現了這一趨勢。自動化配置縮短了部署時間,而認證合作夥伴則提供持續的管治。這些趨勢表明,即使自助服務工具不斷改進,以服務主導的成長軌跡仍將持續。
預計到2025年,大型企業將佔總營收的74.35%。這企業發展、龐大的IT團隊以及推動其部署強大的行動BI套件的合規義務。大型企業正在將分析圖表整合到其ERP和CRM工作流程中,使數千名員工能夠在現場追蹤KPI。多租戶管治、單一登入和精細的角色控制滿足了金融、醫療保健和公共部門負責人。儘管大型企業佔據主導地位,但得益於承包SaaS降低了進入門檻,中小企業(SME)領域目前正經歷著最快的成長。
中小企業 (SME) 青睞按需計量收費訂閱、自動擴展以及整合到常用辦公室套件中的嚮導式報表產生器。隨著創辦人尋求在無需建立昂貴的本地資料庫的情況下,即時了解現金流、庫存和客戶情緒,面向中小企業的行動商業情報市場預計將快速成長。克羅埃西亞的研究數據顯示,成功的實施與經營團隊的支持和明確的績效目標密切相關。應用程式商店充斥著適用於 Shopify、QuickBooks 和 Stripe 的現成連接器,中小企業無需聘請資料科學家即可擁抱資料驅動型文化。這清楚地解釋了為什麼該細分市場有望超越整個行動商業情報產業的成長速度。
區域分析
到2025年,北美將佔全球整體收入的36.25%。這主要得益於LTE-Advanced的廣泛應用、5G的快速部署以及企業在行動安全框架方面的熟練運用。矽谷供應商正在北美地區率先試用語音查詢和基於攝影機的數據採集等新功能,然後再在全球範圍內發布,從而為該地區帶來早期生產力提升。與微軟Entra ID和Okta的緊密整合簡化了從桌面端到智慧型手機的身份同步,從而提高了有效用戶數量。不斷上漲的人事費用也促使企業追求以數據分析為主導的效率提升,確保了行動商業情報市場升級所需的預算持續到位。
亞太地區正呈現顯著成長,預計到2031年將維持22.85%的複合年成長率。這主要得益於各國政府對5G頻段的津貼以及強制推行資料在地化政策,優先使用境內的雲端服務。中國電商巨頭正將Petabyte遙測資料即時導入儀錶板,以在幾分鐘內最佳化閃購活動。印度的統一支付介面(UPI)每天向分析雲端平台發送數十億筆交易數據,使銀行能夠改進本地代理商智慧型手機上的詐欺偵測模型。東南亞國協的許多製造商跳過了傳統的MES系統,率先採用行動儀錶板,這項「突破」正推動行動商業情報市場以超過其他任何地區的速度擴張。
在歐洲,受GDPR、永續發展目標和工業5.0策略的推動,行動商業智慧(BI)市場呈現穩定成長。公共產業利用行動BI監控可再生能源發電,汽車製造商則使用手持分析工具協調即時交付。嚴格的隱私法規推動了偽匿名化和設備內加密技術的發展,雖然增加了開發複雜性,但也使透過合規性審計的供應商脫穎而出。同時,拉丁美洲、中東和非洲等新興市場正在湧現。巴西的即時支付網路PIX正在向渴望獲得行動洞察的金融科技公司提供行為數據。沿岸地區的電信業者將分析儀表板與企業資料方案捆綁銷售,向油田營運商、醫院和智慧城市管理者提供整合行動性和智慧功能的一站式解決方案。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 大型企業採用雲端優先移動 BI
- 5G/邊緣部署的快速成長使得即時分析成為可能。
- 中小企業中自帶設備辦公室 (BYOD) 的擴展和主資料管理 (MDM) 的整合
- 已將分析功能整合到 SaaS 應用和行動工作流程中。
- 由生成式人工智慧驅動的自然語言查詢介面
- 主導的「網路分析即服務」的提供。
- 市場限制因素
- 人們對個人設備的安全和隱私問題仍然存在擔憂。
- 在進行複雜分析時,行動儀錶板的便利性有其限制。
- 多重雲端環境中資料管治的碎片化
- 由於 App Store 政策的變更,SDK 的資料收集受到限制。
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 評估宏觀經濟趨勢對市場的影響
第5章 市場規模與成長預測
- 透過解決方案
- 軟體
- 行動 BI 平台
- 數據視覺化工具
- 儀錶板和報告應用程式
- 服務
- 專業服務
- 託管服務
- 軟體
- 按組織規模
- 大公司
- 中小企業
- 透過使用
- 銷售和行銷分析
- 財務和風險分析
- 業務和供應鏈分析
- 人力資源和勞動力分析
- 客戶體驗分析
- 按最終用戶行業分類
- BFSI
- 資訊科技/通訊
- 醫療保健和生命科學
- 零售與電子商務
- 政府/公共部門
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- SAP SE
- IBM Corporation
- Salesforce Inc.(Tableau)
- Oracle Corporation
- QlikTech International AB
- SAS Institute
- MicroStrategy Inc.
- TIBCO Software
- Sisense Inc.
- ThoughtSpot Inc.
- Google LLC(Looker)
- Domo Inc.
- Yellowfin International
- Phocas Software
- Zoho Corporation
- Board International
- Dundas Data Visualization
- TARGIT A/S
- e-Zest Solutions Ltd.
- Information Builders Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, mobile business intelligence market size in 2026 is estimated at USD 24.35 billion, growing from 2025 value of USD 19.93 billion with 2031 projections showing USD 66.28 billion, growing at 22.18% CAGR over 2026-2031.
This report is Segmented by Solution (Software and Services), Organization Size (Large Enterprises and Small and Medium Enterprises (SMEs)), Application (Sales and Marketing Analytics, Finance and Risk Analytics, and More), End-User Vertical (BFSI, IT and Telecommunications, Healthcare and Life Sciences, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Mobile Business Intelligence Market Trends and Insights
Cloud-first Mobile BI Adoption Among Large Enterprises
Large corporations are swapping on-premises stacks for cloud-native mobile BI so global staff can reach dashboards without VPN friction. More than 52,000 companies actively use Microsoft Power BI, embedding analytics into Microsoft 365 work streams. The shift lowers total cost of ownership because server upkeep disappears and elastic resources scale during peak usage. SAP Analytics Cloud similarly links live transactional data with mobile visualizations while preserving strict identity controls. As this model proliferates, mobile business intelligence market penetration deepens across regulated sectors that once resisted cloud migration.
Surge in 5G/Edge Deployments Enabling Real-time Analytics
Standalone 5G networks now run in seven Asia-Pacific countries, undergirding a USD 880 billion regional mobile economy that prizes responsive analytics. Edge computing moves processing to local gateways so mobile dashboards refresh in milliseconds, a necessity for factory predictive-maintenance alerts and retail shelf-stocking decisions. Financial-trading desks in Tokyo already exploit sub-millisecond feeds to price derivatives on handheld devices. These examples illustrate how 5G plus edge collectively raise usage intensity inside the mobile business intelligence market.
Persistent Security and Privacy Concerns on Personal Devices
Sixty percent of enterprises cite mobile security as the main barrier to broader BI rollout despite clear sales-performance gains. BYOD policies mingle consumer and corporate apps, raising leakage risks that new Apple privacy manifests only partly mitigate. Banks and hospitals often restrict mobile BI to company-issued phones, slowing penetration in high-value verticals even as encryption and biometric log-ins improve.
Other drivers and restraints analyzed in the detailed report include:
- BYOD Expansion and MDM Integration in SMEs
- Embedded Analytics Within SaaS Apps and Mobile Workflows
- Limited Mobile Dashboard Usability for Complex Analysis
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software remains the revenue cornerstone, supplying visualization tools, query engines and governance layers that earned a 65.92% share in 2025. These offerings anchor most enterprise analytics stacks and integrate with identity suites, data warehouses and low-code platforms. Still, surging demand for implementation, customization and managed operations means service providers are booking faster contracts than license vendors. Many clients now outsource fine-tuning of large language models, edge-deployment scripts and zero-trust controls because internal teams lack bandwidth. The mobile business intelligence market size for services is projected to expand at high double-digit CAGR through 2031 as organizations shift from pure software spend toward outcome-based engagements.
Consulting firms bundle data engineering, user-training and day-two optimization so clients can unlock value soon after go-live. Managed-services partners sign multiyear agreements to keep mobile apps patched, monitor usage and refine semantic layers, freeing business units to focus on insight consumption instead of platform care. MicroStrategy's listing on Google Cloud Marketplace illustrates the trend: automated provisioning trims deployment timelines, while certified partners step in for ongoing governance. These patterns reinforce a service-rich growth arc likely to continue even as self-service tooling improves.
Large enterprises controlled 74.35% revenue in 2025 because they possess global operations, ample IT staff, and compliance obligations that favor robust mobile BI suites. They embed analytic graphs into ERP and CRM workflows so thousands of employees can track KPIs in the field. Multi-tenant governance, single sign-on, and fine-grained role controls satisfy auditors in finance, healthcare, and public-sector domains. Despite this dominance, the small-business segment now logs the briskest expansion as turnkey SaaS lowers entry barriers.
SMEs appreciate pay-as-you-go subscriptions, automated scaling, and wizard-based report builders that appear within familiar productivity suites. The mobile business intelligence market size for SMEs is forecast to climb steeply as founders seek instant visibility into cash flow, inventory, and customer sentiment without spinning up expensive on-prem databases. Croatian survey data shows that adoption success correlates with top-management sponsorship and clear performance targets. As app stores flood with pre-built connectors to Shopify, QuickBooks, and Stripe, smaller firms can join data-driven cultures without hiring data scientists, underscoring why this cohort will keep outpacing the overall mobile business intelligence industry.
Complete Report Scope:
- By Solution
- Software
- Mobile BI Platforms
- Data Visualization Tools
- Dashboard and Reporting Apps
- Services
- Professional Services
- Managed Services
- Software
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Application
- Sales and Marketing Analytics
- Finance and Risk Analytics
- Operations and Supply-chain Analytics
- HR and Workforce Analytics
- Customer Experience Analytics
- By End-user Vertical
- BFSI
- IT and Telecommunications
- Healthcare and Life Sciences
- Retail and E-commerce
- Government and Public Sector
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America kept 36.25% of global revenue in 2025, anchored by ubiquitous LTE-Advanced coverage, swift 5G roll-outs, and enterprise familiarity with mobile security frameworks. Silicon Valley vendors pilot novel features-voice query, camera-based data capture-domestically before global releases, giving the region early productivity gains. Tight integrations with Microsoft Entra ID and Okta simplify identity propagation from desktop to phone, boosting active-user counts. High labor costs also motivate firms to chase analytics-driven efficiency, ensuring continued budget allocation for upgrades in the mobile business intelligence market.
Asia-Pacific stands out with a projected 22.85% CAGR through 2031 as governments subsidize 5G spectrum and mandate data-localization that favors cloud regions inside national borders. China's e-commerce giants stream petabyte-scale telemetry into real-time dashboards that optimize flash sales in minutes. India's Unified Payments Interface pushes billions of daily transactions into analytics clouds, letting banks refine fraud models on smartphones carried by rural agents. Many ASEAN manufacturers skip legacy MES systems and adopt mobile dashboards first, illustrating a leapfrog effect that expands the mobile business intelligence market size faster than any other region.
Europe posts steady expansion under the weight of GDPR, sustainability targets, and Industry 5.0 strategies. Utilities use mobile BI to monitor renewable generation, while carmakers rely on handheld analytics to coordinate just-in-sequence deliveries. Strict privacy rules encourage pseudonymization and on-device encryption, raising development complexity but also differentiating vendors that pass compliance audits. Meanwhile, Latin America and the Middle East and Africa open fresh territory. Brazil's PIX instant-payment network feeds behavioral data to fintechs hungry for mobile insights. Gulf telcos bundle analytics dashboards with enterprise data plans, selling one-stop mobility plus intelligence to oil-field operators, hospitals, and smart-city managers.
- Microsoft Corporation
- SAP SE
- IBM Corporation
- Salesforce Inc. (Tableau)
- Oracle Corporation
- QlikTech International AB
- SAS Institute
- MicroStrategy Inc.
- TIBCO Software
- Sisense Inc.
- ThoughtSpot Inc.
- Google LLC (Looker)
- Domo Inc.
- Yellowfin International
- Phocas Software
- Zoho Corporation
- Board International
- Dundas Data Visualization
- TARGIT A/S
- e-Zest Solutions Ltd.
- Information Builders Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-first mobile BI adoption among large enterprises
- 4.2.2 Surge in 5G/edge deployments enabling real-time analytics
- 4.2.3 BYOD expansion and MDM integration in SMEs
- 4.2.4 Embedded analytics within SaaS apps and mobile workflows
- 4.2.5 Generative-AI-powered natural language query interfaces
- 4.2.6 Telco-led "network analytics-as-a-service" offerings
- 4.3 Market Restraints
- 4.3.1 Persistent security and privacy concerns on personal devices
- 4.3.2 Limited mobile dashboard usability for complex analysis
- 4.3.3 Data-governance fragmentation across multi-cloud estates
- 4.3.4 App-store policy changes throttling SDK data capture
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of the Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 Software
- 5.1.1.1 Mobile BI Platforms
- 5.1.1.2 Data Visualization Tools
- 5.1.1.3 Dashboard and Reporting Apps
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Software
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium Enterprises (SMEs)
- 5.3 By Application
- 5.3.1 Sales and Marketing Analytics
- 5.3.2 Finance and Risk Analytics
- 5.3.3 Operations and Supply-chain Analytics
- 5.3.4 HR and Workforce Analytics
- 5.3.5 Customer Experience Analytics
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 IT and Telecommunications
- 5.4.3 Healthcare and Life Sciences
- 5.4.4 Retail and E-commerce
- 5.4.5 Government and Public Sector
- 5.4.6 Other End-user Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 SAP SE
- 6.4.3 IBM Corporation
- 6.4.4 Salesforce Inc. (Tableau)
- 6.4.5 Oracle Corporation
- 6.4.6 QlikTech International AB
- 6.4.7 SAS Institute
- 6.4.8 MicroStrategy Inc.
- 6.4.9 TIBCO Software
- 6.4.10 Sisense Inc.
- 6.4.11 ThoughtSpot Inc.
- 6.4.12 Google LLC (Looker)
- 6.4.13 Domo Inc.
- 6.4.14 Yellowfin International
- 6.4.15 Phocas Software
- 6.4.16 Zoho Corporation
- 6.4.17 Board International
- 6.4.18 Dundas Data Visualization
- 6.4.19 TARGIT A/S
- 6.4.20 e-Zest Solutions Ltd.
- 6.4.21 Information Builders Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 英國商業智慧:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)競爭資訊服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)商業智慧(BI):市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)醫療保健商業智慧:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 商業情報市場-2026-2032年全球市場預測
 2026年全球即時商業智慧市場報告
 全球行動商業情報(BI)市場
 2026-2030年全球醫療保健產業商業智慧市場
 銀行業、金融服務業和保險業 (BFSI) 的客戶體驗成長機會:2025-2026 年
 2026-2030年全球商業智慧(BI)市場