


 |
市場調查報告書
商品編碼
2122273
越南數位電子看板市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Vietnam Digital Signage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
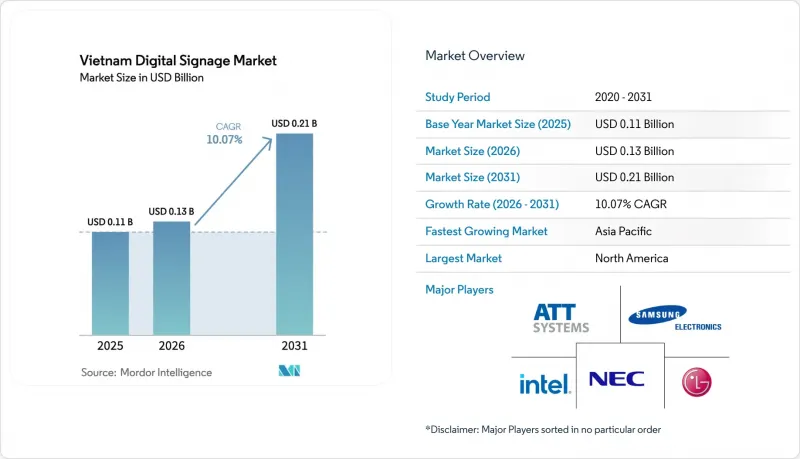
根據 Mordor Intelligence 預測,越南數位電子看板市場規模預計將在 2026 年達到 1.3 億美元,到 2031 年達到 2.1 億美元,預測期內複合年成長率為 10.07%。
本報告按類型(單面板顯示器、電視牆、圖騰式數位海報及其他)、組件(硬體、軟體、服務)、螢幕尺寸(32英寸以下、32-52英寸、52-75英寸及其他)、位置(店內/室內、室外)和最終用戶行業(零售、交通運輸、酒店、快餐、企業及其他)進行細分。市場預測以美元計價。
越南數位電子看板市場趨勢與洞察
LED顯示器的成本正在迅速下降。
三星顯示器在北寧省擴大OLED生產線,以及LG顯示器在海防的投資,已將越南打造成為面板製造中心,交貨週期從八週縮短至不到四周。京東方科技位於巴地-頭頓的工廠預計將於2025年投產,年產700萬塊顯示器和4000萬塊電子紙,預計這將為服務於越南數位電子看板市場的系統整合商降低20-25%的交付成本。如今,本地零售商能夠以以往只有批量進口才能享受到的價格購買到55英寸商用顯示螢幕,從而將更換週期從36-48個月縮短至18-24個月。成本降低在32-52英吋尺寸範圍內最為顯著,而此尺寸範圍的產品廣泛應用於快餐店和藥局。微型LED試點生產線預計將降低40%的功耗,並具有超過10萬小時的使用壽命,這些特性對於越南潮濕氣候下的戶外廣告業者來說具有重要價值。
零售連鎖店的擴張和對動態廣告的需求
WinCommerce計畫從2025年的4,300家門市擴展到2030年的10,000家門市,旨在收銀台和貨架末端建立標準化的數位電子看板。在越南3,500億美元的零售業中,預計到2030年,現代零售將佔據約30%的市場佔有率,推動從紙本媒體向連網螢幕的穩定轉變。永旺娛樂正與Beta Media合作,在全國推廣影院。這些影院將在特許經營區配備電視牆、數位海報和自助服務終端,以實現客流量的變現。 CGV越南2024年的銷售額激增部分得益於螢幕廣告,凸顯了連網顯示器帶來的額外優勢。反過來,這又促使內容更新頻率的提高,進一步鞏固了越南數位電子看板市場作為維護品牌一致性戰術性工具的地位。
大型LED幕牆需要大量的初始資本投入
對於尺寸超過100吋的螢幕,安裝成本在5萬至15萬美元之間,這使得小規模的場館難以收回成本。雖然擁有6萬個座位的PVF體育場和由Vingroup運營的擁有13.5萬個座位的奧運場館表明,財力雄厚的讚助商可以承擔這些成本,但芹苴和榮市的購物中心卻面臨著兩位數的利率和30%至40%的首付要求。儘管像BrightSign和Scala這樣按螢幕計費的訂閱租賃模式正在逐漸普及,但它們仍然依賴廣告商簽訂多年合約的意願。在其他資金籌措結構成熟之前,該市場資本密集的性質可能會減緩小城市的普及速度,從而導致越南數位電子看板市場的成長軌跡較為溫和。
細分市場分析
到2025年,單面板顯示器將佔據越南數位電子看板市場43.88%的佔有率,其在藥局、便利商店和銀行分店的「即插即用」便利性推動了其普及。電視牆雖然能提供更佳的沉浸式體驗,但需要結構加固和精確校準,因此其應用範圍僅限於旗艦店和控制室,兩者合計約佔市場需求的五分之一。投影和其他替代方案,例如透明OLED、電子紙和全像投影,預計將在2031年前以11.34%的複合年成長率成長,這主要得益於高階零售店和博物館的試點部署,這些場所的新穎性吸引了許多參觀者。
身臨其境型設施也正在推動進一步成長。在可容納 6 萬人的 PVF 體育場,環繞的 LED 燈帶可獨立於門票銷售產生贊助收入;艾比森為越南 80 週年慶典安裝的 2000平方公尺顯示螢幕,則凸顯了應對力大規模部署的能力。這些案例研究正在提高人們的認知度,加速實驗性措施的發展,並擴大越南數位電子看板市場的潛在基本客群。
預計到2025年,硬體將佔越南數位電子看板市場規模的55.83%,而包括安裝、維護、創新服務和營運管理在內的服務領域,到2031年將以每年11.43%的速度成長。三星、LG和京東方等廠商的本地面板生產正在縮短供應鏈,但附加價值正轉向遠端營運和運轉率保障。基於雲端的內容管理系統(CMS)平台,每個螢幕每月僅需10-15美元,無需支付與許可相關的資本支出(CAPEX),使中小企業能夠以最小的風險進行試點營運。
分析功能將進一步推動網路變現。 HPT 的人工智慧指示牌解決方案可將廣告投放率提升高達 20%,但根據第 13/2023 號法令,人口統計日誌必須加密。隨著 5G 覆蓋率接近 90%,即時韌體更新將減少 30-40% 的現場支持,從而進一步提升服務需求。因此,收入將轉向週期性契約,進一步強化越南數位電子看板市場從硬體依賴型轉變為服務型經濟模式的趨勢。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- LED顯示器的成本正在迅速下降。
- 零售連鎖店的擴張和對動態廣告的需求
- 政府推動智慧城市和智慧交通的舉措
- 新冠疫情後引進非接觸式互動指示牌
- 5G部署和基於雲端的內容管理系統,可實現即時內容更新。
- 越南工業園區節能微型LED生產本地化
- 市場限制因素
- 大型LED幕牆需要大量的初始資本投入
- 網路連線型數指示牌的網路安全與資料隱私問題
- 由於本地內容創作生態系統分散,投資報酬率有限。
- 歷史街區的相關規定限制了戶外展示品的亮度。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資趨勢和當前資金籌措狀況
第5章 市場規模與成長預測
- 按類型
- 單面板顯示器
- 電視牆
- 圖騰數位海報
- 自助服務終端/互動終端
- 戶外LED廣告看板和街道家具(DOOH)
- 其他類型的指示牌(投影等)
- 按組件
- 硬體
- 顯示面板
- 媒體播放機控制器
- 安裝支架
- 其他
- 軟體
- 服務
- 硬體
- 按螢幕尺寸
- 32英吋或更小
- 32-52英寸
- 52-75英寸
- 75吋或更大
- 特大號,100吋或更大
- 按位置
- 商店/室內
- 戶外的
- 按最終用戶行業分類
- 零售
- 運輸
- 飯店業
- QSR
- 公司
- 體育娛樂
- 衛生保健
- 其他
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Net and Com Integrated Telecom Co., Ltd.
- Vodatel Integrated Solutions (Vietnam) Co., Ltd.
- NEC Corporation
- ATT Systems (Vietnam) Pte. Ltd.
- Inavate AV Co., Ltd.
- Intel Corporation
- LG Electronics Inc.
- Samsung Electronics Co., Ltd.
- Panasonic Holdings Corporation
- Sony Group Corporation
- Sharp Corporation
- Daktronics, Inc.
- Leyard Optoelectronic Co., Ltd.
- Unilumin Group Co., Ltd.
- Absen Optoelectronic Co., Ltd.
- AOTO Electronics Co., Ltd.
- BrightSign, LLC
- Scala, Inc.(Stratacache Company)
- Advantech Co., Ltd.
- Christie Digital Systems USA, Inc.
- E Ink Holdings Inc.
- Visionect doo
- Vietnam Digital Signage Joint-Stock Company(VDS)
第7章 市場機會與未來展望
According to Mordor Intelligence, the Vietnam digital signage market was valued at USD 0.13 billion in 2026 and is projected to reach USD 0.21 billion by 2031, representing a 10.07% CAGR during the forecast period.
This report is Segmented by Type (Single-Panel Displays, Video Walls, Totems/Digital Posters, and More), Component (Hardware, Software, and Services), Screen Size (Below 32 Inch, 32-52 Inch, 52-75 Inch, and More), Location (In-store/Indoor, Outdoor), and End-User Industry (Retail, Transportation, Hospitality, QSR, Corporate, and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Digital Signage Market Trends and Insights
Rapid Decline in LED Display Costs
Samsung Display's Bac Ninh OLED expansion and LG Display's Haiphong investment have transformed Vietnam into a panel-manufacturing hub, reducing delivery lead times from eight weeks to less than four. BOE Technology's Ba Ria-Vung Tau factory will produce 7 million displays and 40 million ePaper units annually from 2025, reducing landed costs by an estimated 20-25% for integrators serving the Vietnam digital signage market. Local retailers can now acquire 55-inch commercial-grade screens at prices that were previously reserved for bulk imports, accelerating replacement cycles from 36-48 months to 18-24 months. Cost deflation is most pronounced in the 32-52 inch bracket that dominates quick-service restaurants and pharmacies. Pilot lines for micro-LEDs promise a 40% lower power draw and lifespans exceeding 100,000 hours, attributes that outdoor operators value in Vietnam's humid climate.
Retail Chain Expansion and Demand for Dynamic Advertising
WinCommerce plans to grow from 4,300 stores in 2025 to 10,000 by 2030, cementing standardized digital signage at checkout queues and end-caps. The modern trade share of Vietnam's USD 350 billion retail sector is expected to reach approximately 30% by 2030, leading to a steady shift from printed media to connected screens. AEON Entertainment's partnership with Beta Media to open cinemas nationwide will feature video walls, digital posters, and concession-area kiosks that monetize foot traffic. CGV Vietnam's 2024 revenue surge, driven partly by on-screen advertising, underscores the incremental margin that networked displays deliver. The driver therefore amplifies content-refresh frequencies and elevates the Vietnam digital signage market as a tactical tool for brand consistency.
High Upfront Capital Expenditure for Large-Format LED Walls
Screens above 100 inches cost USD 50,000-150,000 fully installed, an outlay that smaller venues struggle to amortize. The 60,000-seat PVF Stadium and Vingroup's 135,000-seat Olympic complex illustrate how deep-pocketed sponsors absorb these costs, yet shopping centers in Can Tho or Vinh face double-digit financing rates and 30-40% down-payment requirements. Leasing models from BrightSign and Scala, priced on a per-screen subscription, are gaining favor but still depend on advertisers' willingness to commit to multi-year contracts. Until alternative funding structures mature, capital intensity will temper rollout velocity in secondary cities, thereby moderating the Vietnam digital signage market growth trajectory.
Other drivers and restraints analyzed in the detailed report include:
- Government Smart-City and Smart-Transport Initiatives
- Adoption of Contactless Interactive Signage Post-COVID
- Cyber-Security and Data-Privacy Concerns in Networked Signage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Single-panel displays held 43.88% of the Vietnam digital signage market in 2025, underscoring their plug-and-play appeal for pharmacies, convenience stores, and branch banks. Video walls, although immersive, require structural reinforcement and precision calibration, limiting adoption to flagship stores and control rooms that collectively account for roughly one-fifth of demand. Projection and other alternative formats, including transparent OLED, ePaper, and holography, are set to expand at an 11.34% CAGR through 2031, driven by luxury retail and museum pilots where novelty attracts foot traffic.
Immersive venues provide further traction. The 60,000-seat PVF Stadium features perimeter LED ribbons that generate sponsorship revenue independently of ticket sales, while Absen's 2,000-square-meter installation for Vietnam's 80th National Day highlights its scale readiness. Such deployments widen awareness and accelerate experimentation, thereby broadening the addressable base for the Vietnam digital signage market.
Hardware contributed 55.83% to the Vietnam digital signage market size in 2025, yet the services segment, including installation, maintenance, creative, and managed operations, is forecast to grow 11.43% annually through 2031. Local panel output from Samsung, LG, and BOE shortens supply chains, but value shifts toward remote orchestration and uptime guarantees. Cloud CMS platforms, priced at USD 10-15 per screen monthly, eliminate licensing CAPEX, allowing small enterprises to launch pilots with minimal risk.
Analytics layers further monetize networks. HPT's AI-enabled signage solution boosts ad fill rates up to 20% but must encrypt demographic logs to comply with Decree 13/2023. As 5G coverage approaches 90%, real-time firmware updates reduce truck rolls by 30-40%, further amplifying service demand. The outcome tilts revenue toward recurring contracts, reinforcing the Vietnam digital signage market's shift from hardware dependency to service-centric economics.
Complete Report Scope:
- By Signage Type
- Single-Panel Displays
- Video Walls
- Totems / Digital Posters
- Kiosks / Interactive Terminals
- Outdoor LED / Billboard / Street Furniture (DOOH)
- Other Signage Types (Projection, Etc.)
- By Component
- Hardware
- Display Panels
- Media Players and Controllers
- Mounts and Stands
- Other Hardwares
- Software
- Services
- Hardware
- By Screen Size
- Below 32 inch
- 32-52 inch
- 52-75 inch
- Above 75 inch
- Ultra-large Above 100"
- By Location
- In-store/Indoor
- Outdoor
- By End-user Industry
- Retail
- Transportation
- Hospitalitiy
- QSR
- Corporate
- Sports and Entertainment
- Healthcare
- Other End-user Industries
List of Companies Covered in this Report:
- Net and Com Integrated Telecom Co., Ltd.
- Vodatel Integrated Solutions (Vietnam) Co., Ltd.
- NEC Corporation
- ATT Systems (Vietnam) Pte. Ltd.
- Inavate AV Co., Ltd.
- Intel Corporation
- LG Electronics Inc.
- Samsung Electronics Co., Ltd.
- Panasonic Holdings Corporation
- Sony Group Corporation
- Sharp Corporation
- Daktronics, Inc.
- Leyard Optoelectronic Co., Ltd.
- Unilumin Group Co., Ltd.
- Absen Optoelectronic Co., Ltd.
- AOTO Electronics Co., Ltd.
- BrightSign, LLC
- Scala, Inc. (Stratacache Company)
- Advantech Co., Ltd.
- Christie Digital Systems USA, Inc.
- E Ink Holdings Inc.
- Visionect d.o.o.
- Vietnam Digital Signage Joint-Stock Company (VDS)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid decline in LED display costs
- 4.2.2 Retail chain expansion and demand for dynamic advertising
- 4.2.3 Government smart-city and smart-transport initiatives
- 4.2.4 Adoption of contactless interactive signage post-COVID
- 4.2.5 Roll-out of 5G and cloud CMS enabling real-time content updates
- 4.2.6 Localization of energy-efficient micro-LED production in Vietnam's industrial parks
- 4.3 Market Restraints
- 4.3.1 High upfront capital expenditure for large-format LED walls
- 4.3.2 Cyber-security and data-privacy concerns in networked signage
- 4.3.3 Fragmented local content-creation ecosystem limiting ROI
- 4.3.4 Heritage-zone regulations capping outdoor display brightness
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Trends and Funding Landscape
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Signage Type
- 5.1.1 Single-Panel Displays
- 5.1.2 Video Walls
- 5.1.3 Totems / Digital Posters
- 5.1.4 Kiosks / Interactive Terminals
- 5.1.5 Outdoor LED / Billboard / Street Furniture (DOOH)
- 5.1.6 Other Signage Types (Projection, Etc.)
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.1.1 Display Panels
- 5.2.1.2 Media Players and Controllers
- 5.2.1.3 Mounts and Stands
- 5.2.1.4 Other Hardwares
- 5.2.2 Software
- 5.2.3 Services
- 5.2.1 Hardware
- 5.3 By Screen Size
- 5.3.1 Below 32 inch
- 5.3.2 32-52 inch
- 5.3.3 52-75 inch
- 5.3.4 Above 75 inch
- 5.3.5 Ultra-large Above 100"
- 5.4 By Location
- 5.4.1 In-store/Indoor
- 5.4.2 Outdoor
- 5.5 By End-user Industry
- 5.5.1 Retail
- 5.5.2 Transportation
- 5.5.3 Hospitalitiy
- 5.5.4 QSR
- 5.5.5 Corporate
- 5.5.6 Sports and Entertainment
- 5.5.7 Healthcare
- 5.5.8 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Net and Com Integrated Telecom Co., Ltd.
- 6.4.2 Vodatel Integrated Solutions (Vietnam) Co., Ltd.
- 6.4.3 NEC Corporation
- 6.4.4 ATT Systems (Vietnam) Pte. Ltd.
- 6.4.5 Inavate AV Co., Ltd.
- 6.4.6 Intel Corporation
- 6.4.7 LG Electronics Inc.
- 6.4.8 Samsung Electronics Co., Ltd.
- 6.4.9 Panasonic Holdings Corporation
- 6.4.10 Sony Group Corporation
- 6.4.11 Sharp Corporation
- 6.4.12 Daktronics, Inc.
- 6.4.13 Leyard Optoelectronic Co., Ltd.
- 6.4.14 Unilumin Group Co., Ltd.
- 6.4.15 Absen Optoelectronic Co., Ltd.
- 6.4.16 AOTO Electronics Co., Ltd.
- 6.4.17 BrightSign, LLC
- 6.4.18 Scala, Inc. (Stratacache Company)
- 6.4.19 Advantech Co., Ltd.
- 6.4.20 Christie Digital Systems USA, Inc.
- 6.4.21 E Ink Holdings Inc.
- 6.4.22 Visionect d.o.o.
- 6.4.23 Vietnam Digital Signage Joint-Stock Company (VDS)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 美國數位電子看板:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)中東和非洲數位電子看板市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 LED指示牌市場-全球市場預測(2026-2032年)數位電子看板:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)北美數位電子看板市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)數位電子看板市場:2026-2032年全球市場預測(按組件、顯示技術、內容類型、解析度、螢幕大小、連接方式、應用、安裝位置和部署模式分類)數位電子看板服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 透明數位電子看板冷卻器市場規模、佔有率和成長分析:按產品類型、顯示技術、容量、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 智慧LED室內指示牌市場報告:螢幕大小、最終用戶和地區分類(2026-2034年)
 2026-2030年全球商用大尺寸顯示指示牌市場