


 |
市場調查報告書
商品編碼
2121210
印刷標籤:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Print Label - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
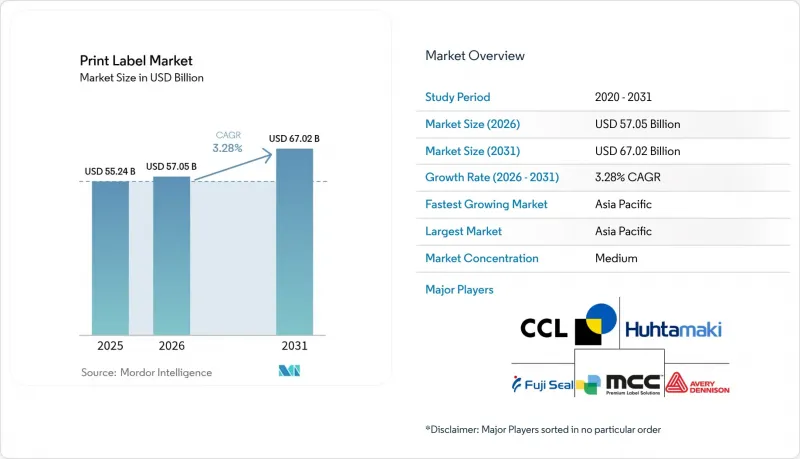
根據 Mordor Intelligence 估計,印刷標籤市場在 2026 年的價值將達到 570.5 億美元,高於 2025 年的 552.4 億美元,預計到 2031 年將達到 670.2 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 3.28%。
本報告按印刷過程(平張膠印、凹版印刷、彈性凸版印刷、網版印刷、凸版印刷、靜電複印、噴墨印刷)、標籤形式(濕膠標籤、壓敏膠標籤、無底紙標籤、多聯追蹤標籤、套模標籤、收縮標籤和拉伸套)、終端用戶行業(食品、飲料、醫療保健和製藥等)以及地區進行細分。市場預測以美元計價。
全球印刷標籤市場趨勢與洞察
加快引進高速數位印刷機進行小批量生產。
數位噴墨平台能夠以低至 500 件的小批量實現盈利性生產,而傳統的柔版印刷則需要 10,000 件的起印閾值,這為消費品牌開闢了新的 SKU 策略。 RR Donnelly 在喬治亞斥資 2500 萬美元進行升級改造,體現了加工商為提升處理能力和可變數據柔軟性而進行的巨額投資。整合式噴墨和柔版印刷塔的混合生產線簡化了設定變更,但也造成了操作人員技能的差距。彈性凸版印刷技術協會等行業組織正透過「FIRST 5.0」課程來應對這項挑戰。隨著高速數位印刷的生產效率與類比印刷的經濟性相融合,標籤印刷市場將轉向混合技術生產單元,從而縮短前置作業時間並減少庫存。
品牌所有者正逐步轉向無底紙標籤以減少廢棄物
取消離型紙可減少高達 30% 的標籤廢棄物,提高捲材密度,並降低物流成本,這也符合永續性指標。市場領導者報告稱,無離型紙產品的銷售額實現了兩位數成長,尤其是在食品零售領域,這主要得益於生產者延伸責任制 (EPR) 費用的推動。轉型面臨的障礙包括專用貼標機和必須在濕度波動下保持性能的黏合劑配方,但供應商正在擴大產能。 UPM Raflatac 報告稱,2025 年第一季環比成長 13%,部分原因是歐洲對無離型紙標籤的需求。加工商的競爭力將取決於他們掌握與傳統壓敏黏著劑工作流程不同的新型塗佈和分切技術的能力。
原物料價格波動對加工企業的利潤率帶來了壓力。
自2024年以來,紙漿、PET和丙烯酸黏合劑的價格指數一直經歷兩位數的波動,對原料成本佔銷貨成本75%的加工商造成了顯著影響。全球企業正透過避險和規模經濟來應對這項挑戰;艾利丹尼森公司透過成本控制,在銷售額下降0.1%的情況下仍維持了息稅前利潤,而中小加工商則難以將額外成本轉嫁給年度合約下的品牌所有者。像索諾科這樣的大型企業正在投資3,000萬美元擴大黏合劑產能,以確保供應並減輕原物料價格波動的影響。在基材市場穩定之前,利潤率面臨的壓力可能會抑制中小企業在印刷標籤市場的投資。
細分市場分析
噴墨技術5.3%的複合年成長率凸顯了其在重塑印刷標籤市場中的重要角色。儘管柔版印刷憑藉其成熟的製版生態系統,仍然佔據大批量SKU的大部分佔有率,但噴墨承印物的多功能性和一鍵切換功能,正使加工商能夠獲得高利潤的小批量訂單,用於促銷宣傳活動。由於設備成本更低,且白色油墨的遮蓋力可與網版印刷媲美,預計與噴墨印刷相關的印刷標籤市場規模將穩定成長。將噴墨印刷條添加到柔版印刷生產線的混合架構正逐漸成為加工商資本投資計畫中的主流,這種架構既能實現可變資料印刷,又能保留成熟的模擬模切工作流程。
AstroNova在2024年德魯巴印刷展上發布的「TrojanLabel」平台,是中幅印刷領域的一個典型代表,其目標客戶是精釀飲料和化妝品行業的加工商,這些加工商需要達到膠印級別的套準精度,同時又希望最大限度地減少設置時間。雖然大型飲料代工生產商對超長版印刷的凹版印刷需求依然強勁,但隨著UV噴墨印刷能夠提供媲美Pantone色彩還原的色彩,平張膠印的市場佔有率正在萎縮。網版印刷技術在耐用消費品行業(例如電子產品)中仍然佔有一席之地,因為這些行業的薄膜厚度至關重要,但其在印刷標籤市場的佔有率預計將繼續下降。
區域分析
預計到2025年,亞太地區將以35.86%的市佔率主導印刷標籤市場,並在2031年之前維持4.63%的複合年成長率。中國豐富的製造業資源以及印度包裝市場的擴張(預計2025年將達到2,048.1億美元)是推動該地區成長的主要動力。當地加工商正在投資中幅數位印刷機,以滿足消費者品牌日益成長的需求。同時,日本和韓國政府的回收政策正在促進可回收面材和水洗油墨的採用。東南亞國家正在轉型為電子商務履約中心,刺激了對熱敏運輸標籤和QR碼退貨標籤的需求。
北美地區持續引領技術發展,大型零售商的相關法規推動了雲端連接RFID標籤的快速普及。 2024年,樹脂價格下跌擠壓了利潤空間,並對銷售造成了負面影響,但加工商透過自動化和拓展高價值應用領域抵消了這些不利因素。該地區藥品序列化於2024年11月的最後期限促使全國各地的工廠進行硬體升級,進一步提升了智慧標籤在印刷標籤市場的滲透率。
在歐洲,成熟的市場需求與嚴格的循環經濟法規並存。法國和德國推行的生產者延伸責任制(EPR)促進了無底紙和單一材料標籤的發展。英國的《基本要求條例》指南標籤厚度的降低和可回收性的提升,從而刺激了無溶劑黏合劑的研發。東歐的加工商正從歐盟範圍內的品牌商那裡獲得契約製造訂單,這些品牌商在確保符合法規的前提下,優先考慮成本效益。
拉丁美洲、中東和非洲雖然貢獻較小,但都呈現成長趨勢。巴西和墨西哥正在擴大飲料收縮膜的生產能力,而海灣合作理事會成員國則正向包裝食品領域多元化發展,進口波灣合作理事會設備和技術訣竅。非洲市場面臨貿易壁壘和基礎設施限制,但行動商務的成長顯示可變數據標籤解決方案具有長期潛力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在標籤印刷作業中,SKU 的數量在小批量生產中迅速增加,高速數位(噴墨)印刷機的採用正在加速。
- 為了減少廢棄物和物流成本,品牌所有者正在轉向使用無底紙感壓標籤。
- 電子商務的蓬勃發展推動了對能夠處理可變數據的運輸和退貨標籤的需求。
- 監管機構推廣智慧標籤/條碼標籤,以實現端到端可追溯性(例如,歐盟《食品藥物管理局條例》、美國《藥品供應鏈安全法》)
- 精釀飲品和美食對高階裝飾標籤的需求日益成長。
- 一種新型抗菌標籤塗層,可確保冷鏈物流中的食品安全。
- 市場限制因素
- 紙張、薄膜和黏合劑的價格波動給加工商的利潤率帶來了壓力。
- 中小加工企業在操作混合式數位柔版印刷機方面存在技能差距。
- 品牌所有者越來越傾向於在包裝上直接進行數位印刷(無需標籤)。
- 在循環經濟市場中,多層收縮標籤和套模標籤回收所面臨的挑戰。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過印刷過程
- 膠印光刻
- 凹版印刷
- 柔版印刷
- 螢幕
- 凸版印刷
- 靜電照相術
- 噴墨
- 標籤格式
- 濕膠標籤
- 感壓標籤
- 無底紙標籤
- 多部分追蹤標籤
- 套模標籤
- 收縮套圈和拉伸套
- 按最終用戶行業分類
- 食物
- 飲料
- 醫療和藥品
- 化妝品和個人護理
- 家務清潔
- 工業和汽車
- 物流與電子商務
- 電子設備/家用電器
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Fuji Seal International, Inc.
- Mondi plc
- Huhtamaki Oyj
- 3M Company
- Brady Corporation
- Ahlstrom-Munksjo Oyj
- Autajon Group
- Taghleef Industries LLC
- Ravenwood Packaging Ltd.
- SATO Holdings Corporation
- Taylor Corporation
- Weber Packaging Solutions, Inc.
- Resource Label Group, LLC
- Advanced Labelworx, Inc.
- Alliance Prints USA, Inc.
- Clarion Safety Systems, LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, print label market size in 2026 is estimated at USD 57.05 billion, growing from 2025 value of USD 55.24 billion with 2031 projections showing USD 67.02 billion, growing at 3.28% CAGR over 2026-2031.
This report is Segmented by Print Process (Offset Lithography, Gravure, Flexography, Screen, Letterpress, Electrophotography, and Inkjet), Label Format (Wet-Glue, Pressure-Sensitive, Linerless, Multi-Part Tracking, In-Mold, and Shrink and Stretch Sleeves), End-User Industry (Food, Beverage, Healthcare and Pharmaceuticals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Print Label Market Trends and Insights
Accelerated Adoption of High-Speed Digital Presses for Short-Run Production
Digital inkjet platforms enable profitable runs as low as 500 pieces, contrasting with flexography's historical 10,000-unit threshold, thereby unlocking new SKU strategies for consumer brands. Capital outlays, such as R.R. Donnelley's USD 25 million Georgia upgrade, illustrate the scale converters commit to gain throughput and variable-data flexibility. Hybrid lines integrating inkjet and flexo towers streamline changeovers yet create operator-skill gaps that industry groups like the Flexographic Technical Association address through FIRST 5.0 curricula. As high-speed digital productivity converges with analog economics, the print label market will migrate toward mixed-technology production cells that compress lead times and inventory.
Brand-Owner Shift Toward Linerless Labels for Waste Reduction
Eliminating release liners cuts label waste up to 30% and boosts roll density, generating logistics savings that resonate with sustainability scorecards. Market leaders report double-digit linerless revenue growth, especially within food retail, where Extended Producer Responsibility fees spur adoption. Transition barriers include specialized applicators and adhesive formulations that must perform across humidity swings, but suppliers are scaling capacity. UPM Raflatac reported 13% quarter-on-quarter growth in Q1 2025, partly on European linerless demand. Converter competitiveness hinges on mastering new coating and slitting techniques that diverge from conventional pressure-sensitive workflows.
Raw Material Price Volatility Pressuring Converter Margins
Paper pulp, PET, and acrylic adhesive indices have swung by double digits since 2024, leaving converters exposed because materials account for up to 75% of cost of sales. While global players leverage hedging and scale, Avery Dennison reported a 0.1% sales dip yet preserved EBIT via cost controls, SME converters struggle to pass surcharges to brand owners under annual contracts. Consolidators such as Sonoco channel USD 30 million into adhesive capacity expansions to secure supply and dilute input swings. Until substrate markets stabilize, margin compression will temper investment appetite among smaller firms in the print label market.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce Expansion Driving Variable-Data Printing Demand
- Regulatory Traceability Requirements Accelerating Smart-Label Adoption
- Technical Skill Gaps in Hybrid Digital-Flexo Operations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Inkjet technology's 5.3% CAGR underscores its role in reshaping the print label market. Flexography still produces the bulk of long-run SKUs thanks to mature platemaking ecosystems, but inkjet's substrate versatility and 1-click changeovers let converters secure high-margin micro-runs for promotional campaigns. The print label market size associated with inkjet presses is forecast to grow steadily as equipment costs fall and white ink opacity rivals screen-print quality. Across converters, hybrid architectures that bolt inkjet bars onto flexo lines dominate capex roadmaps, enabling variable data without abandoning proven analog die-cutting workflows.
AstroNova's TrojanLabel platform, launched at Drupa 2024, typifies the mid-web category aimed at craft beverage and cosmetics converters seeking near-offset registration with minimal setup. Gravure's niche in ultra-long runs remains secure for large beverage co-packers, yet offset lithography's footprint narrows as UV-inkjet delivers comparable Pantone coverage. Screen technology survives in electronics durables where film thickness is critical, but its share within the print label market will continue to erode.
Complete Report Scope:
- By Print Process
- Offset Lithography
- Gravure
- Flexography
- Screen
- Letterpress
- Electrophotography
- Inkjet
- By Label Format
- Wet-Glue Labels
- Pressure-Sensitive Labels
- Linerless Labels
- Multi-Part Tracking Labels
- In-Mold Labels
- Shrink and Stretch Sleeves
- By End-User Industry
- Food
- Beverage
- Healthcare and Pharmaceuticals
- Cosmetics and Personal Care
- Household Cleaning
- Industrial and Automotive
- Logistics and E-commerce
- Electronics and Appliances
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific dominated the print label market in 2025 with a 35.86% share and is projected to post the highest 4.63% CAGR to 2031. China's extensive manufacturing base and India's packaging expansion valued at USD 204.81 billion for 2025 underpin regional momentum. Local converters invest in mid-web digital presses to handle proliferating consumer brands, while government recycling mandates in Japan and South Korea encourage adoption of recyclable facestock and wash-off inks. Southeast Asian nations pivot toward e-commerce fulfillment hubs, stimulating demand for thermal shipping labels and QR-based return tags.
North America remains a technology bellwether, with rapid uptake of cloud-connected RFID labels driven by big-box retail mandates. Margin pressures from resin deflation challenged revenue in 2024, yet converters offset headwinds via automation and high-value applications. The region's pharma serialization deadline of November 2024 spurred hardware upgrades across U.S. plants, reinforcing smart-label penetration within the print label market.
Europe combines mature demand with stringent circular-economy rules. Extended Producer Responsibility fees in France and Germany favor linerless and mono-material constructions. The UK's Essential Requirements Regulations guide downgauging and recyclability, stimulating R&D into solvent-free adhesives. Eastern European converters attract contract manufacturing for pan-EU brands seeking cost efficiency without sacrificing regulatory compliance.
Latin America, the Middle East, and Africa account for smaller but rising contributions. Brazil and Mexico scale capacity for beverage shrink sleeves, while Gulf Cooperation Council members diversify into packaged foods, importing technical know-how alongside capital equipment. African markets grapple with trade barriers and infrastructure constraints, yet mobile commerce growth signals long-term potential for variable-data label solutions.
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Fuji Seal International, Inc.
- Mondi plc
- Huhtamaki Oyj
- 3M Company
- Brady Corporation
- Ahlstrom-Munksjo Oyj
- Autajon Group
- Taghleef Industries LLC
- Ravenwood Packaging Ltd.
- SATO Holdings Corporation
- Taylor Corporation
- Weber Packaging Solutions, Inc.
- Resource Label Group, LLC
- Advanced Labelworx, Inc.
- Alliance Prints USA, Inc.
- Clarion Safety Systems, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated adoption of high-speed digital (inkjet) presses for short-run, SKU-proliferated label jobs
- 4.2.2 Brand-owner shift toward linerless pressure-sensitive labels to cut waste and logistics costs
- 4.2.3 E-commerce boom driving demand for variable-data shipping and return labels
- 4.2.4 Regulatory push for smart/barcode labels enabling end-to-end traceability (e.g., EU FMD, U.S. DSCSA)
- 4.2.5 Growth of craft beverage and gourmet foods requiring premium, embellishment-rich labels
- 4.2.6 Emerging antimicrobial label coatings for food safety in cold-chain logistics
- 4.3 Market Restraints
- 4.3.1 Volatile paper, film and adhesive prices squeezing converter margins
- 4.3.2 Skill-gap in operating hybrid digital-flexo presses among SME converters
- 4.3.3 Rising brand-owner preference for direct-to-package digital printing (no label)
- 4.3.4 Difficult recycling of multi-layer shrink and in-mold labels in circular-economy markets
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Print Process
- 5.1.1 Offset Lithography
- 5.1.2 Gravure
- 5.1.3 Flexography
- 5.1.4 Screen
- 5.1.5 Letterpress
- 5.1.6 Electrophotography
- 5.1.7 Inkjet
- 5.2 By Label Format
- 5.2.1 Wet-Glue Labels
- 5.2.2 Pressure-Sensitive Labels
- 5.2.3 Linerless Labels
- 5.2.4 Multi-Part Tracking Labels
- 5.2.5 In-Mold Labels
- 5.2.6 Shrink and Stretch Sleeves
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Household Cleaning
- 5.3.6 Industrial and Automotive
- 5.3.7 Logistics and E-commerce
- 5.3.8 Electronics and Appliances
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 United Arab Emirates
- 5.4.5.1.2 Saudi Arabia
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 CCL Industries Inc.
- 6.4.2 Avery Dennison Corporation
- 6.4.3 Multi-Color Corporation
- 6.4.4 Fuji Seal International, Inc.
- 6.4.5 Mondi plc
- 6.4.6 Huhtamaki Oyj
- 6.4.7 3M Company
- 6.4.8 Brady Corporation
- 6.4.9 Ahlstrom-Munksjo Oyj
- 6.4.10 Autajon Group
- 6.4.11 Taghleef Industries LLC
- 6.4.12 Ravenwood Packaging Ltd.
- 6.4.13 SATO Holdings Corporation
- 6.4.14 Taylor Corporation
- 6.4.15 Weber Packaging Solutions, Inc.
- 6.4.16 Resource Label Group, LLC
- 6.4.17 Advanced Labelworx, Inc.
- 6.4.18 Alliance Prints USA, Inc.
- 6.4.19 Clarion Safety Systems, LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 北美印刷標籤:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)美國印刷標籤:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)網版印刷標籤:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 標籤印刷市場:按標籤格式、印刷過程、終端用戶產業和地區分類列印貼標及貼標設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 印刷標籤市場報告:按原料、印刷過程、標籤格式、最終用途行業和地區分類(2026-2034年)
 2026年全球印刷標籤市場報告
 印刷組件和標籤(熱轉印、數位印刷、網版印刷):全球市場佔有率和排名、總收入和需求預測(2025-2031 年)日本印刷標籤市場規模、佔有率、趨勢及預測(按原料、印刷過程、標籤格式、最終用途行業和地區),2025 年至 2033 年
 印刷標籤市場規模、佔有率及成長分析(依印刷製程、標籤格式、原料、最終用途產業、地區及細分市場預測),2025 年至 2032 年