


 |
市場調查報告書
商品編碼
2119753
北美硬質塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)North America Rigid Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
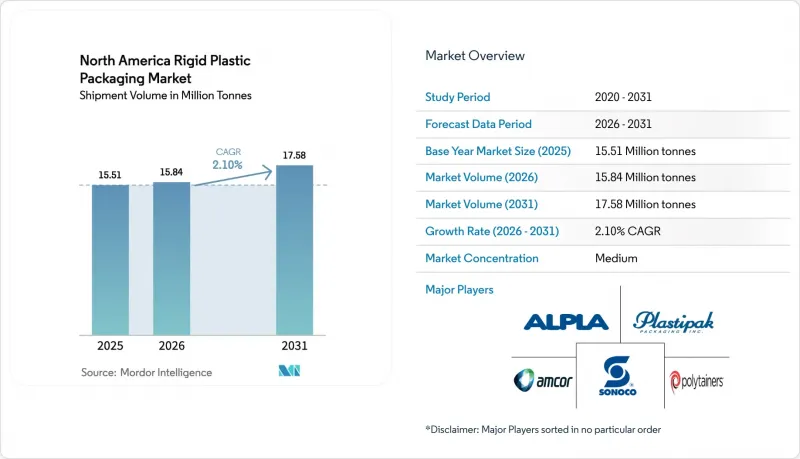
根據 Mordor Intelligence 預測,北美硬質塑膠包裝市場預計將從 2025 年的 1,551 萬噸成長到 2026 年的 1,584 萬噸,到 2031 年將達到 1,758 萬噸,2026 年至 2031 年的複合年成長率為 2.10%。
本報告按樹脂類型(聚乙烯、PET、聚丙烯等)、產品類型(瓶/罐、托盤/容器、瓶蓋/封口、桶等)、終端用戶行業(食品、飲料、醫療保健、化妝品等)、製造流程(射出成型、吹塑成型等)和國家/地區進行細分。市場預測以噸為單位。
北美硬質塑膠包裝市場趨勢及洞察
日常消費品(FMCG)滲透率的不斷提高推動了銷量的成長。
墨西哥和美國南部地區可支配收入的成長和都市化的加快,擴大了現代零售商店的覆蓋範圍,並增加了對包裝食品和飲料的需求。全國連鎖便利商店提高了周轉率,需要使用硬包裝容器來延長保存期限,以保持產品新鮮。品牌商更傾向於使用聚乙烯和聚丙烯瓶來包裝食用油、醬料和家居用品,因為這些材料成本穩定,能夠保證可預測的單位價值。大型零售商也在推廣自有品牌產品,這促進了小批量生產,並增加了柔軟性射出成型和吹塑成型設備的使用。 SKU數量的增加和人均消費量的成長共同支撐了北美硬質塑膠包裝市場的基本成長。因此,快速消費品(FMCG)的滲透率提升抵消了碳酸飲料等成熟品類需求的下滑。
寶特瓶永續發展計畫加速rPET採購
大型飲料生產商已設定目標,到2030年實現至少25%的再生材料含量,這推動了對食品級rPET產能的投資。改良的回收系統使2024年區域寶特瓶回收率達到27.9%。 Plastipak和ALPLA等生產商正透過擴大其解聚和精煉生產線來應對這項挑戰,幫助品牌所有者實現其自願和監管目標。雖然再生塑膠的價格高於原生PET,但有保障的交易量使得長期採購協議成為可能,從而降低了資本投資的風險。隨著rPET應用的日益普及,加工商正透過滿足飲料生產商要求的污染控制和可追溯性審核來提升自身競爭力。這些永續發展項目如今已成為北美硬質塑膠包裝市場的結構性驅動力。
來自柔軟性和紙質包裝的競爭日益激烈。
具有環保意識的消費者認為,一次性硬質塑膠包裝不如輕巧的軟包裝袋和新興的纖維性包裝解決方案永續性。品牌所有者為了回應零售商的評估標準,正在將某些產品(例如乾零食包裝和調味品)的包裝改為複合材料和塗層紙板。包裝器材製造商現在提供多模態填充生產線,降低了硬質和軟質包裝之間轉換的成本。儘管如此,在抗衝擊性、承重能力或防篡改功能至關重要的領域,硬質包裝仍然保持其功能優勢,從而限制了其市場佔有率的下滑,使其僅限於特定類別。這種市場競爭限制了北美硬質塑膠包裝市場加工商的漲價空間。
細分市場分析
到2025年,聚乙烯將佔據最大的市場佔有率,達到29.10%,這反映了其成熟的加工基礎設施和多功能性能。飲料、家居用品和工業化學品製造商將經常使用高密度聚乙烯,因為它具有耐化學性和剛性。到2025年,聚乙烯在北美硬質塑膠包裝市場的規模將達到451萬噸,但其未來的複合年成長率將低於PET。 PET的複合年成長率為3.72%,這得益於其可回收性和透明度,而飲料品牌非常重視這些特性。強制性再生材料含量要求正在加速食品級rPET的使用,為擁有先進淨化反應器的供應商創造了一個高階利基市場。聚丙烯在熱填充和微波爐適用容器中仍然發揮著特殊作用,而聚苯乙烯則由於地方政府的禁令而持續下降。新興的生物基樹脂正以試用規模出現,並吸引了高階化妝品品牌的注意。總體而言,雖然樹脂多樣化正在取得進展,但聚烯和PET仍將是北美硬質塑膠包裝市場的核心支柱。
目前的研究和開發工作重點在於阻隔添加劑和鏈延伸技術,這些技術能夠在不影響機械性能的前提下提高再生材料的含量。加工商正與樹脂製造商合作,根據美國食品藥物管理局 (FDA) 21 CFR 法規對新型食品接觸樹脂進行認證,從而縮短產品上市時間。此類夥伴關係使樹脂供應商能夠深度融入客戶的價值鏈,即使在人們對材料循環利用的期望日益成長的情況下,也能維持穩定的需求。
到2025年,瓶罐將佔出貨量的45.10%,並與飲料、醬料和個人保健產品的成熟填充和分銷系統完美契合。由於其成熟的模具基礎和與現有貼標生產線的兼容性,這些產品在北美硬質塑膠包裝市場保持市場佔有率。托盤和拉環用於調理食品和乳製品領域,這些應用需要一定的剛性以防止在微波加熱過程中變形。中型散貨箱因其高承載能力而用於運輸化學品和潤滑劑,而桶則用於散裝運輸。
瓶蓋和封口件的複合年成長率 (CAGR) 最高,達到 3.1%,主要得益於消費者對安全性和便利性的需求不斷成長。為了符合一次性塑膠製品法規,兒童安全鎖、劑量可調滴管和繫繩式瓶蓋等設計日益複雜,同時也推高了平均單位成本。整合 NFC 晶片的智慧瓶蓋正在試點應用,用於高階烈酒的真偽檢驗。加工商正投資於多成分注塑成型和後成型組裝自動化,以搶佔這一高價值細分市場。因此,瓶蓋和封口件在北美硬質塑膠包裝市場佔有重要的戰略地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 快速消費品(FMCG)的日益普及正在推高需求。
- 寶特瓶永續發展計畫正在加速rPET的採購。
- 電子商務和D2C通路的擴張正在推動對防護包裝需求的成長。
- FDA對過渡限制的修訂正在推動對阻隔塗層的投資。
- 透過利用人工智慧進行缺陷檢測,我們降低了缺陷率,並擴大了利潤來源。
- 北美石化產品生產能力從燃料轉向聚合物,使得樹脂價格保持競爭力。
- 市場限制因素
- 靈活的格式和向紙質媒體的過渡
- 原生樹脂原料價格波動很大。
- 食品用消費後再生材料的供不應求限制了再生材料的使用。
- 州級EPR費用給低利潤的固定格式產品帶來了壓力。
- 產業價值鏈分析
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 依樹脂類型
- 聚乙烯
- 高密度聚苯乙烯(HDPE)
- 低密度聚乙烯(LDPE)
- 線型低密度聚乙烯(LLDPE)
- 聚對苯二甲酸乙二酯
- 聚丙烯
- 聚苯乙烯和EPS
- 其他樹脂類型
- 聚乙烯
- 依產品類型
- 瓶子和罐子
- 托盤和容器
- 蓋子和封口
- 中型散貨箱(IBC)
- 鼓
- 其他產品類型
- 按最終用戶行業分類
- 食物
- 糖果和糖果甜點
- 乳製品和冷凍食品
- 肉類、雞肉、魚貝類
- 其他食物類型
- 飲料
- 醫療和藥品
- 化妝品和個人護理
- 工業化學品
- 建築/施工
- 其他終端用戶產業
- 食物
- 透過製造程序
- 射出成型
- 吹塑成型
- 熱成型
- 壓縮成型
- 擠壓
- 其他製造程序
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- ALPLA Group GmbH
- Gerresheimer AG
- Plastipak Holdings Inc.
- Sonoco Products Company
- Polytainers Inc.
- Graham Packaging Company LP
- Greif Inc.
- Altium Packaging LLC
- Silgan Holdings Inc.
- Pactiv Evergreen Inc.
- Winpak Ltd.
- CCL Industries Inc.
- Consolidated Container Company LLC
- Sealed Air Corporation
- Huhtamaki Oyj
- Reynolds Group Holdings Ltd.
- International Paper Company
- Smurfit WestRock
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America rigid plastic packaging market size is expected to grow from 15.51 million tonnes in 2025 to 15.84 million tonnes in 2026 and is forecast to reach 17.58 million tonnes by 2031 at 2.10% CAGR over 2026-2031.
This report is Segmented by Resin Type (Polyethylene, PET, Polypropylene, and More), Product Type (Bottles/Jars, Trays/Containers, Caps/Closures, Drums, and More), End-User Industry (Food, Beverage, Healthcare, Cosmetics, and More), Manufacturing Process (Injection Molding, Blow Molding, and More), and Country. The Market Forecasts are Provided in Terms of Volume (Tonnes).
North America Rigid Plastic Packaging Market Trends and Insights
Growing FMCG Penetration Drives Volume Expansion
Rising disposable income and urbanization in Mexico and the US South are broadening modern retail footprints and lifting demand for packaged food and beverages. National convenience-store chains drive high product turnover, requiring rigid containers that protect freshness during longer shelf cycles. Brand owners favor polyethylene and polypropylene bottles for oil, sauces, and household goods because material cost stability supports predictable unit economics. Large retailers also promote private-label ranges, stimulating smaller production runs that benefit from flexible injection and blow-molding equipment. The combined effect of more SKUs and higher per-capita consumption underpins baseline growth in the North America rigid plastic packaging market. FMCG penetration therefore offsets sluggish demand in mature categories such as carbonated soft drinks.
PET Bottle Sustainability Programs Accelerate rPET Procurement
Major beverage companies have pledged minimum recycled content thresholds often 25% or higher by 2030, catalyzing investment in food-grade rPET capacity. Collection systems improved, lifting the regional PET bottle recycling rate to 27.9% in 2024. Producers such as Plastipak and ALPLA responded by expanding depolymerization and purification lines, helping brand owners meet voluntary and legislative targets. Recycled resin trades at a premium to virgin PET, but volume commitments enable long-term offtake contracts that de-risk capital spending. As rPET adoption grows, converters differentiate through contamination control and traceability audits demanded by beverage clients. These sustainability programs are now a structural driver of the North America rigid plastic packaging market
Flexible and Paper-Based Format Competition Intensifies
Environment-conscious consumers perceive single-use rigid plastics as less sustainable than lightweight pouches or emerging fiber-based solutions. Brand owners responding to retailer scorecards convert selected SKUs such as dry snack packs and seasoning mixes to laminates or coated paperboard. Packaging machinery suppliers now offer multimodal filling lines, lowering switching costs between rigid and flexible formats. Nevertheless, rigid packaging retains functional advantages where impact resistance, stack strength, or tamper evidence is critical, limiting share erosion to specific categories. The competitive tension suppresses price-increase headroom for converters in the North America rigid plastic packaging market.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce Growth Intensifies Protective-Packaging Requirements
- FDA Migration-Limit Revisions Drive Barrier Technology Investment
- Feedstock Price Volatility Creates Cost Pressures
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene commanded the largest 29.10% share in 2025, reflecting entrenched processing infrastructure and versatile performance. Beverage, household, and industrial chemical producers rely on high-density grades for chemical resistance and rigidity. The North America rigid plastic packaging market size for polyethylene reached 4.51 million tonnes in 2025, yet its forward CAGR trails that of PET. PET's 3.72% CAGR benefits from recyclability credentials and clarity prized by beverage brands. Recycled-content mandates accelerate food-grade rPET use, creating premium niches for suppliers with advanced decontamination reactors. Polypropylene retains specialized roles in hot-fill and microwaveable containers, while polystyrene's decline continues due to municipal bans. Emerging bio-based resins appear in pilot volumes, appealing to premium cosmetic lines. Overall, resin diversification is rising but polyolefins and PET will remain core pillars of the North America rigid plastic packaging market.
Ongoing R&D focuses on barrier additives and chain-extension chemistries that enable higher recycled content without compromising mechanical properties. Converters collaborate with resin producers to qualify new grades under FDA 21 CFR regulations for food contact, shortening commercialization timelines. Such partnerships embed resin suppliers deeper into customer value chains, supporting stable demand even as material circularity expectations climb
Bottles and jars represented 45.10% of 2025 shipments, aligned with long-standing filling and distribution systems across beverages, sauces, and personal care. Their entrenched tooling bases and compatibility with existing labeling lines safeguard share within the North America rigid plastic packaging market. Trays and tubs serve ready-meal and dairy applications that demand rigidity to prevent deformation during microwave heating. Intermediate bulk containers support chemicals and lubricants thanks to stack strength, while drums cater to bulk transport.
Caps and closures exhibit the fastest 3.1% CAGR, propelled by heightened safety and convenience needs. Child-resistant mechanisms, dose-control droppers, and tethered closures to meet single-use-plastic directives drive design complexity and raise average unit revenue. Smart closures integrating NFC chips enter pilot scale in premium spirits, providing authenticity verification. Converters invest in multi-component molding and post-mold assembly automation to capture this high-value segment. As a result, caps and closures gain strategic prominence inside the North America rigid plastic packaging market.
Complete Report Scope:
- By Resin Type
- Polyethylene
- High-Density Polyethylene (HDPE)
- Low-Density Polyethylene (LDPE)
- Linear Low-Density Polyethylene (LLDPE)
- Polyethylene Terephthalate
- Polypropylene
- Polystyrene and EPS
- Other Resin Type
- Polyethylene
- By Product Type
- Bottles and Jars
- Trays and Containers
- Caps and Closures
- Intermediate Bulk Containers (IBCs)
- Drums
- Other Product Types
- By End-user Industry
- Food
- Candy and Confectionery
- Dairy and Frozen
- Meat, Poultry and Seafood
- Other Food Types
- Beverage
- Healthcare and Pharmaceuticals
- Cosmetics and Personal Care
- Industrial Chemicals
- Building and Construction
- Other End-user Industry
- Food
- By Manufacturing Process
- Injection Moulding
- Blow Moulding
- Thermoforming
- Compression Moulding
- Extrusion
- Other End-user Industries
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Amcor plc
- ALPLA Group GmbH
- Gerresheimer AG
- Plastipak Holdings Inc.
- Sonoco Products Company
- Polytainers Inc.
- Graham Packaging Company LP
- Greif Inc.
- Altium Packaging LLC
- Silgan Holdings Inc.
- Pactiv Evergreen Inc.
- Winpak Ltd.
- CCL Industries Inc.
- Consolidated Container Company LLC
- Sealed Air Corporation
- Huhtamaki Oyj
- Reynolds Group Holdings Ltd.
- International Paper Company
- Smurfit WestRock
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing FMCG penetration boosts demand
- 4.2.2 PET bottle sustainability programs accelerate rPET procurement
- 4.2.3 Expansion of e-commerce and D2C channels raises protective-packaging needs
- 4.2.4 FDA migration-limit revisions spur barrier-coating investments
- 4.2.5 AI-enabled defect-detection lowers scrap rates and widens profit pools
- 4.2.6 NA petro-chemical capacity shift from fuels to polymers keeps resin prices competitive
- 4.3 Market Restraints
- 4.3.1 Shift toward flexible and paper-based formats
- 4.3.2 Volatile virgin-resin feedstock prices
- 4.3.3 Shortfall of food-grade PCR supply caps recycled-content adoption
- 4.3.4 State-level EPR fees squeeze low-margin rigid formats
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Resin Type
- 5.1.1 Polyethylene
- 5.1.1.1 High-Density Polyethylene (HDPE)
- 5.1.1.2 Low-Density Polyethylene (LDPE)
- 5.1.1.3 Linear Low-Density Polyethylene (LLDPE)
- 5.1.2 Polyethylene Terephthalate
- 5.1.3 Polypropylene
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Resin Type
- 5.1.1 Polyethylene
- 5.2 By Product Type
- 5.2.1 Bottles and Jars
- 5.2.2 Trays and Containers
- 5.2.3 Caps and Closures
- 5.2.4 Intermediate Bulk Containers (IBCs)
- 5.2.5 Drums
- 5.2.6 Other Product Types
- 5.3 By End-user Industry
- 5.3.1 Food
- 5.3.1.1 Candy and Confectionery
- 5.3.1.2 Dairy and Frozen
- 5.3.1.3 Meat, Poultry and Seafood
- 5.3.1.4 Other Food Types
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Industrial Chemicals
- 5.3.6 Building and Construction
- 5.3.7 Other End-user Industry
- 5.3.1 Food
- 5.4 By Manufacturing Process
- 5.4.1 Injection Moulding
- 5.4.2 Blow Moulding
- 5.4.3 Thermoforming
- 5.4.4 Compression Moulding
- 5.4.5 Extrusion
- 5.4.6 Other End-user Industries
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 ALPLA Group GmbH
- 6.4.3 Gerresheimer AG
- 6.4.4 Plastipak Holdings Inc.
- 6.4.5 Sonoco Products Company
- 6.4.6 Polytainers Inc.
- 6.4.7 Graham Packaging Company LP
- 6.4.8 Greif Inc.
- 6.4.9 Altium Packaging LLC
- 6.4.10 Silgan Holdings Inc.
- 6.4.11 Pactiv Evergreen Inc.
- 6.4.12 Winpak Ltd.
- 6.4.13 CCL Industries Inc.
- 6.4.14 Consolidated Container Company LLC
- 6.4.15 Sealed Air Corporation
- 6.4.16 Huhtamaki Oyj
- 6.4.17 Reynolds Group Holdings Ltd.
- 6.4.18 International Paper Company
- 6.4.19 Smurfit WestRock
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 歐洲硬質塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度硬質塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印尼硬質塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 硬質塑膠包裝市場:2026-2032年全球市場預測(按產品類型、材料類型、製造流程、蓋/密封類型和最終用途行業分類)
 2026-2030年全球硬質塑膠包裝市場
 硬質塑膠包裝市場規模、佔有率、趨勢和預測:按產品、材料、製造程序、最終用途行業和地區分類,2026-2034年
 硬質塑膠包裝市場規模、佔有率和成長分析:按製造流程、原料、包裝類型、最終用戶和地區分類-2026-2033年產業預測
 硬質塑膠包裝市場分析及預測(至2035年):類型、產品類型、材質類型、技術、應用、最終用戶、功能、製程和設備
 全球硬質塑膠包裝市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球硬質塑膠包裝市場報告