


 |
市場調查報告書
商品編碼
2119715
法國資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)France Data Center Rack - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,法國資料中心機櫃市場預計到 2026 年價值 5,373 萬美元,高於 2025 年的 4,631 萬美元,預計到 2031 年將達到 1.1305 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 16.02%。
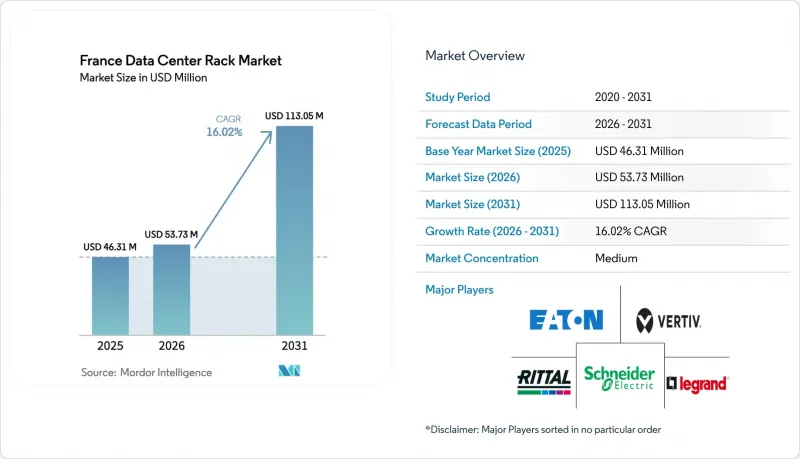
本報告按機架尺寸(四分之一機架、半機架、全機架)、機架高度(42U、45U、48U)、其他高度(52U及以上,以及客製化高度)、機架類型(機櫃式(密封)機架、開放式機櫃、壁掛式機架)、資料中心類型(機櫃式(密封)機架、開放式機架、壁掛式機架)、資料中心類型(機櫃式(鋼等)和材質細分(鋼材等)進行材料。所有細分市場的規模和預測均以美元(USD)計價。
法國資料中心機櫃市場的趨勢與洞察
「雲端優先」企業策略的激增
法國企業正在對其IT基礎設施進行現代化改造,從傳統的本地部署環境轉向混合架構,這需要在本地資料中心部署高容錯性、高密度的機架。 2024年10月的伺服器採購計畫證實了政府向混合基礎設施轉型的趨勢,並加快了對支援私有雲端節點和邊緣微型資料中心機櫃的機架的訂單。目前,Legrander
全國範圍內的光纖骨幹網路擴展
巴黎電信 (RTE) 撥款 3 億歐元用於建立共享電力區,旨在加強骨幹光纖和高容量變電站的協調,鼓勵超大規模資料中心和託管服務供應商在巴黎以外的地區建立計算中心。上法蘭西大區正是這種分散化模式的典型代表,該地區電力價格優惠,且通往倫敦和阿姆斯特丹的線路延遲低於毫秒級。因此,在法國資料中心機櫃市場競爭的供應商正著重強調快速組裝的機櫃套件、遠端鎖定和預測性維護分析等功能——這些功能在缺乏內部工程人才的偏遠地區尤其重要。
網路安全和GDPR合規成本不斷上漲
歐洲資料保護委員會 (EDPB) 2024 年指南中明確的臉部辨識法規迫使營運商在其機櫃上加裝多因素存取控制、RFID 稽核導軌和環境感測器陣列。此外,法國將 NIS2 指令納入國家法規,強制要求即時安全遙測,這將增加每個機架的成本並延長認證週期。對於法國資料中心機櫃市場的供應商而言,差異化價值如今體現在預先符合 GDPR 和企業永續發展要求的承包安全模組上。
細分市場分析
預計到2025年,全機架式機櫃將佔法國資料中心機架市場總銷量的67.85%,並將繼續超越其他規格,到2031年將以18.55%的複合年成長率成長。全機架式機櫃在法國資料中心機櫃市場的主導地位主要得益於超大規模資料中心的需求,這些需求推薦使用標準化的48U和52U機架模板,從而簡化容量規劃並降低物流成本。對於目標密度為30kW及以上的營運商,他們正進一步利用全機架式機櫃,實現相鄰機架行間冷卻液歧管的無縫整合。雖然四分之一機架和半機架在局部邊緣節點仍然十分重要,但負責人擴大將預算分配給包含預先整合匯流排、線槽和液冷接頭的標準化全機架式機櫃套裝。
這種一致性至關重要,尤其是在需要可預測氣流模型的AI叢集中。Schneider Electric與NVIDIA的夥伴關係表明,全封閉式機櫃能夠確保整個資料空間內熱性能的可重複性,這對於數千台GPU伺服器運行同步工作負載而言是一項關鍵的設計要求。因此,在法國資料中心機櫃市場,儘管四分之一機架和半機架的市場規模仍然受到空間受限的通訊機房和相關控制室的限制,但全機架機櫃正在成為新型超大規模資料中心的經濟核心。
預計到2025年,傳統的42U機架將佔法國資料中心機櫃市場規模的52.50%,而48U機架預計到2031年將引領市場,年複合成長率將達到19.02%。更高的機架高度允許容納更高的GPU線程、冗餘電纜配線架和後門式散熱器,而不會影響標準的天花板淨空。雖然高於52U的其他規格機架在法國資料中心機櫃市場中所佔佔有率較小,但它們仍在持續成長,尤其是在新建設的AI實驗室中,這些實驗室力求最大限度地提高單位面積的運算能力。
AMD 收購 ZT Systems 凸顯了精心設計的垂直空間的重要性,這種空間設計便於在節點從風冷升級到水冷時進行重新佈線。在 2018 年之前建造的法國工廠中,通常沒有足夠的通風管道深度來容納 52U 機櫃,因此 42U 仍然是棕地的標準配置。同時,在新園區中,48U 已成為報價請求中的預設配置,而這一高度正逐漸被公認為在工作效率和 GPU 密度之間取得平衡的最佳折衷方案。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 「雲端優先」企業策略的激增
- 擴展全國光纖骨幹網路
- 「Cloud de Confiance」下對主權雲的優先待遇
- AI訓練叢集的密度超過30千瓦/機架
- 為2024年巴黎奧運開發數位遺產的超大規模基礎設施
- 實現低碳核能PUE<1.3目標
- 市場限制因素
- 網路安全和GDPR合規相關的成本增加
- 法國法蘭西島地區可用於發電的土地短缺
- 由於電網連接暫時中斷,新建設被推遲。
- 揭露鋼製貨架的隱含碳排放資訊正在推動對鋼製貨架的資本投資增加。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 市場宏觀經濟趨勢的評估
第5章 市場規模與成長預測
- 按機架尺寸
- 四分之一架
- 半架
- 全機架
- 貨架高度
- 42U
- 45U
- 48U
- 其他高度(52U 以上,以及客製訂單)
- 按機架類型
- 櫃式(密封型)機架
- 開放式機櫃
- 壁掛式機架
- 依資料中心類型
- 託管設施
- 面向超大規模和雲端服務供應商的資料中心
- 企業和邊緣運算
- 材料
- 鋼
- 鋁
- 其他合金和複合材料
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Schneider Electric SE
- Vertiv Group Corp.
- Legrand SA
- Eaton Corporation plc
- Rittal GmbH and Co. KG
- Minkels BV
- nVent Electric plc
- Dell Technologies Inc.
- Hewlett Packard Enterprise Co.
- Black Box Corp.
- Panduit Corp.
- Chatsworth Products Inc.
- Belden Inc.
- AMCO Enclosures(IMS)
- Cisco Systems Inc.
- Huawei Technologies Co., Ltd.
- IBM Corp.
- Fujitsu Ltd.
- Delta Electronics Inc.
- ZTE Corp.
第7章 市場機會與未來展望
According to Mordor Intelligence, France data center rack market size in 2026 is estimated at USD 53.73 million, growing from 2025 value of USD 46.31 million with 2031 projections showing USD 113.05 million, growing at 16.02% CAGR over 2026-2031.
This report is Segmented by Rack Size (Quarter Rack, Half Rack, Full Rack), by Rack Height (42U, 45U, 48U), Other Heights (>=52U and Custom), Rack Type (Cabinet (Closed) Racks, Open-Frame Racks, Wall-Mount Rack), Data Center Type (Colocation Facilities and More), Material (Steel and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD) for all the Segments.
France Data Center Rack Market Trends and Insights
Surge in Cloud-First Enterprise Strategies
French enterprises are modernizing IT estates, migrating from legacy on-premise stacks to hybrid architectures that call for resilient, high-density racks inside local data halls. The October 2024 server-procurement program confirmed the government's pivot toward hybrid infrastructure, unlocking rack orders that support both private-cloud nodes and edge micro-data centers. Legrand now derives 20% of group revenue from data-center activity, confirming the strategic weight of the France data center rack market for diversified industrial suppliers . As edge topologies proliferate, rack designs must deliver uniform power distribution, fast serviceability, and integrated monitoring for AI inference engines as well as conventional enterprise workloads.
Expansion of Nationwide Fiber Backbone
RTE's EUR 300 million allocation for mutualized reception zones tightly couples backbone fiber with high-capacity substations, encouraging hyperscale and colocation players to position compute sites far beyond Paris. The Hauts-de-France region exemplifies this decentralization, pairing favorable electricity pricing with sub-5 ms latency to London and Amsterdam routes. Vendors competing in the France data center rack market therefore emphasize rapid-assembly cabinet kits, remote locking, and predictive failure analytics-features demanded by remote sites where in-house engineering talent is thinner.
Escalating Cyber-Security and GDPR Compliance Costs
Facial-recognition oversight clarified in the 2024 European Data Protection Board guidelines forces operators to retrofit cabinets with multi-factor access controls, RFID audit rails, and environmental sensor arrays. France's transposition of the NIS2 directive compels real-time security telemetry, lifting per-rack outlays and elongating certification cycles. For vendors in the France data center rack market, differentiated value now hinges on turnkey security modules pre-aligned with both GDPR and corporate-sustainability mandates.
Other drivers and restraints analyzed in the detailed report include:
- Cloud de Confiance" Sovereign-Cloud Incentives
- AI Training Clusters Pushing >30 kW/Rack Densities
- Scarcity of Powered Land Parcels in Ile-de-France
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Full-rack cabinets captured 67.85% of 2025 revenue and continue to outpace other formats with an 18.55% CAGR through 2031. This commanding share of the France data center rack market stems from hyperscale mandates favoring uniform 48U and 52U templates, which simplify capacity planning and cut logistics costs. Operators pursuing 30 kW-plus densities further rely on full racks to spread coolant manifolds seamlessly across contiguous rows. Quarter- and half-rack footprints retain relevance for localized edge nodes, yet procurement managers increasingly redirect budget toward standardized full-rack bundles that ship with pre-integrated busbars, cable troughs, and liquid-cooling stubs.
Consistency dovetails with AI clusters demanding predictable airflow modeling. Schneider Electric's NVIDIA partnership validates how fully enclosed columns enable repeatable thermal behavior across data halls, a design imperative when thousands of GPU servers run synchronous workloads. Therefore, the France data center rack market size attached to quarter-rack and half-rack variants remains capped by space-limited telecom huts and ancillary control rooms, whereas full-rack cabinets form the economic backbone of new hyperscale wings.
Although legacy 42U frames still account for 52.50% of the 2025 France data center rack market size, 48U units post a market-leading 19.02% CAGR to 2031. Height gains accommodate taller GPU sleds, redundant cable trays, and rear-door heat exchangers without breaching standard ceiling clearances. The France data center rack market share held by "other" >=52U formats is small yet growing, especially inside greenfield AI labs eager to maximize compute per square foot.
AMD's ZT Systems acquisition underscores the premium on carefully engineered vertical space that avoids recabling when nodes upgrade from air to liquid cooling. French facilities built before 2018 often lack the plenum depth for 52U cabinets, explaining the ongoing dominance of 42U in brownfield sites. New campuses, however, default to 48U in request-for-quotation documents, cementing this height as the median sweet spot between handling ergonomics and GPU density.
Complete Report Scope:
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
List of Companies Covered in this Report:
- Schneider Electric SE
- Vertiv Group Corp.
- Legrand SA
- Eaton Corporation plc
- Rittal GmbH and Co. KG
- Minkels BV
- nVent Electric plc
- Dell Technologies Inc.
- Hewlett Packard Enterprise Co.
- Black Box Corp.
- Panduit Corp.
- Chatsworth Products Inc.
- Belden Inc.
- AMCO Enclosures (IMS)
- Cisco Systems Inc.
- Huawei Technologies Co., Ltd.
- IBM Corp.
- Fujitsu Ltd.
- Delta Electronics Inc.
- ZTE Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in cloud-first enterprise strategies
- 4.2.2 Expansion of nationwide fiber backbone
- 4.2.3 Cloud de Confiance sovereign-cloud incentives
- 4.2.4 AI training clusters pushing >30 kW/rack densities
- 4.2.5 Paris-2024 digital-legacy hyperscale build-outs
- 4.2.6 Low-carbon nuclear grid enabling <1.3 PUE targets
- 4.3 Market Restraints
- 4.3.1 Escalating cyber-security and GDPR compliance costs
- 4.3.2 Scarcity of powered land parcels in le-de-France
- 4.3.3 Grid-connection moratoriums delaying new builds
- 4.3.4 Embodied-carbon disclosure raising steel-rack CAPEX
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Rack Size
- 5.1.1 Quarter Rack
- 5.1.2 Half Rack
- 5.1.3 Full Rack
- 5.2 By Rack Height
- 5.2.1 42U
- 5.2.2 45U
- 5.2.3 48U
- 5.2.4 Other Heights (?52U and Custom)
- 5.3 By Rack Type
- 5.3.1 Cabinet (Closed) Racks
- 5.3.2 Open-Frame Racks
- 5.3.3 Wall-Mount Racks
- 5.4 By Data Center Type
- 5.4.1 Colocation Facilities
- 5.4.2 Hyperscale and Cloud Service Provider DCs
- 5.4.3 Enterprise and Edge
- 5.5 By Material
- 5.5.1 Steel
- 5.5.2 Aluminum
- 5.5.3 Other Alloys and Composites
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Schneider Electric SE
- 6.4.2 Vertiv Group Corp.
- 6.4.3 Legrand SA
- 6.4.4 Eaton Corporation plc
- 6.4.5 Rittal GmbH and Co. KG
- 6.4.6 Minkels BV
- 6.4.7 nVent Electric plc
- 6.4.8 Dell Technologies Inc.
- 6.4.9 Hewlett Packard Enterprise Co.
- 6.4.10 Black Box Corp.
- 6.4.11 Panduit Corp.
- 6.4.12 Chatsworth Products Inc.
- 6.4.13 Belden Inc.
- 6.4.14 AMCO Enclosures (IMS)
- 6.4.15 Cisco Systems Inc.
- 6.4.16 Huawei Technologies Co., Ltd.
- 6.4.17 IBM Corp.
- 6.4.18 Fujitsu Ltd.
- 6.4.19 Delta Electronics Inc.
- 6.4.20 ZTE Corp.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 OCP機架市場規模、佔有率和趨勢分析報告:按組件、機架類型、冷卻技術、最終用途和細分市場預測(2026-2033年)
 中東資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032 年)德國資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)英國資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)西班牙資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)馬來西亞資料中心機櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)資料中心機櫃電源分配單元(PDU):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 資料中心機架市場-2026-2032年全球市場預測