


 |
市場調查報告書
商品編碼
2116795
美國暖通空調設備:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)United States HVAC Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
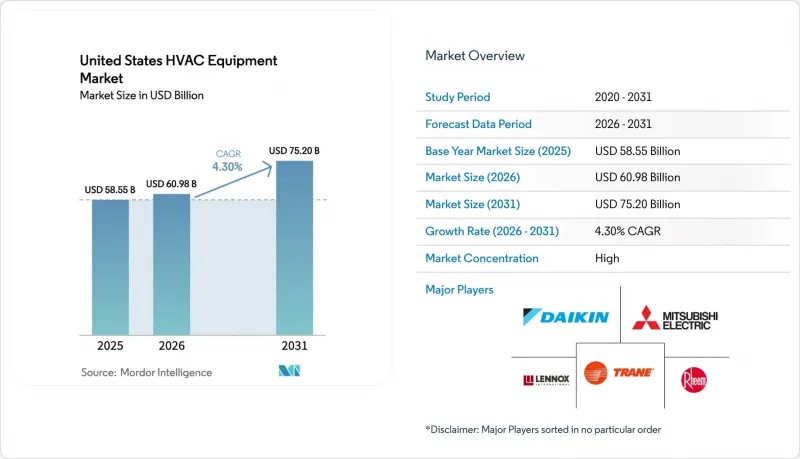
據 Mordor Intelligence 稱,2025 年美國 HVAC 設備市值為 585.5 億美元,預計從 2026 年的 609.8 億美元成長到 2031 年的 752 億美元。
預測期(2026-2031 年)的複合年成長率預計為 4.30%。
本報告按設備類型(空調、暖氣和通風)、最終用戶(住宅、商業和工業)、安裝類型(新建、維修和更換)、能源效率等級(低效和高效)以及地區進行細分。市場預測以美元計價。
美國暖通空調設備市場趨勢與洞察
住宅和大樓自動化系統的擴展
如今,商業房地產開發商和大規模住宅在評估新設備時,不僅重視效率,也優先考慮標準連接性。具備開放API的系統可與設施管理平台無縫整合,從而實現最佳化調度和預測性維護,並降低15-20%的能耗。支援物聯網的溫控器和分區套件正逐漸成為標準配置,而老舊設備無法與最新軟體相容,從而縮短了更換週期。致力於實現ESG(環境、社會和治理)目標的公司將聯網HVAC視為可衡量的碳減排「立竿見影」的成果,這有助於在資本規劃週期中進行批量採購。整合商正從長尾軟體訂閱中獲利,這種模式正在重塑設備整個生命週期的收入模式。
對高效率暖通空調設備的需求日益成長
第24號法規的修訂、最低季節能源效率比(SEER)標準的提高以及智慧電網互通性相關法規的訂定,正推動現場設備規範向高階設備靠攏。雖然高效設備的價格通常高出15%至25%,但不斷上漲的電費和分時電價機制使其在整個生命週期中更具經濟效益。目前,電力公司正透過需量反應獎勵和設備購置補貼相結合的方式,鼓勵用戶採用變速壓縮機和寒冷氣候熱泵。隨著電氣化進程的推進,高峰需求費用日益凸顯,設計階段對千瓦級效能的關注度也越來越高。為此,製造商正逐步將變冷劑流量(VRF)功能引入其主流產品線,以同時滿足監管標準和財務目標。
先進暖通空調系統的初始成本很高
連網式高能源效率比(SEER)熱泵比傳統暖氣系統貴30%至50%,而加裝聯網控制系統又會使專案預算增加15%至20%。對於獨棟住宅業主而言,由於缺乏補貼資金籌措,投資回收期仍超過「3年」的心理閾值。商業住宅者已將投資回報期縮短至5年或更短,導致許多尖端產品被排除在外。補貼在一定程度上減輕了負擔,但資金上限也為長期規劃帶來了不確定性。因此,許多購屋者只能逐步升級,繼續使用次優方案再過一個季節。
細分市場分析
在美國暖通空調設備市場,空調產品細分市場將在2025年成為最大的細分市場,佔總價值的47.35%。冷凍仍然是美國所有氣候區的核心需求,尤其是在快速發展的陽光地帶各州。然而,在聯邦稅額扣抵的推動下,熱泵預計到2031年將維持6.21%的複合年成長率,成為所有類別中成長率最高的。隨著其在寒冷氣候下的性能不斷提升,這些設備正在從燃氣加熱器和純製冷分離式空調手中奪取市場佔有率。
由於法規限制使用某些冷媒,冷卻器的更換速度加快,預計在週期初期,提供與R-32和R-454B相容產品的供應商銷售量將有所成長。同時,隨著空氣品質標準的不斷提高,通風設備的重要性日益凸顯,UV-C和MERV-13過濾器正擴大被整合到飯店和醫療機構的成套設備中。儘管新建專案成長放緩,但這種對室內環境品質的全面重視仍然保持了強勁的需求,從而支撐了美國暖通空調設備市場的長期成長動能。
到2025年,住宅將繼續佔據美國暖通空調設備市場45.68%的佔有率,並以驚人的速度採用智慧控制系統。超過三分之一的新建獨棟住宅將標配連網溫控器,這些溫控器可與熱泵無縫整合,並有資格獲得高達8000美元的個人稅額扣抵。儘管前期成本仍然令人擔憂,但低息公共產業貸款正使高階設備更加經濟實惠。
商業領域的需求主要集中在建築自動化、基於佔用率的通風系統以及符合ESG標準的能源報告。辦公室和零售商店正在轉向採用自適應營運策略,以降低閒置期間的能源消耗。工業用戶需要更嚴格的溫濕度控制以確保生產的穩定性,這推動了對專業化、高容量設計的需求。儘管決策週期不斷延長,但單筆交易的規模卻在擴大,這為美國暖通空調設備市場的整體收入結構提供了穩定性。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 住宅和大樓自動化系統的廣泛應用
- 對節能空調設備的需求日益成長
- 聯邦和州政府實施了嚴格的能源效率法規。
- 加快老舊建築設備的更新換代週期。
- 基於IRA的措施促進熱泵電氣化
- 微型倉配中心的蓬勃發展帶動了對緊湊型暖通空調系統的需求。
- 市場限制因素
- 先進暖通空調系統的初始成本很高。
- 安裝和維護工作中技術純熟勞工短缺
- 全電動化維修中的電網容量限制
- 分階段減少冷媒相關的合規成本尚不明確
- 產業價值鏈分析
- 波特五力分析
第5章 市場規模與成長預測
- 依設備類型
- 空調設備
- 單元空調
- 室內空調
- 包裝式終端空調
- 冷卻器
- 加熱設備
- 暖風機(瓦斯和燃油)
- 鍋爐
- 室內和區域暖氣設備
- 熱泵(空氣源和地熱能)
- 通風設備
- 空調機組
- 風機盤管機組
- 建築物用加濕器和除濕器
- 空調設備
- 最終用戶
- 住宅
- 商業的
- 產業
- 按實現類型
- 新建工程
- 改裝/更換
- 按類型進行效率評估
- 低效率層
- 高效率
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Carrier Global Corporation
- Daikin Industries Ltd.
- Trane Technologies plc
- Johnson Controls International plc
- Lennox International Inc.
- Rheem Manufacturing Company
- Mitsubishi Electric Corporation
- Nortek Air Solutions LLC
- NIBE Industrier AB
- LG Electronics Inc.
- Midea Group Co., Ltd.
- Systemair AB
- Greenheck Fan Corporation
- TROX GmbH
- Goodman Manufacturing Company LP
- Bosch Thermotechnology Corp.
- AAON Inc.
- Fujitsu General America Inc.
- Samsung Electronics America Inc.
- Danfoss A/S
第7章 市場機會與未來展望
According to Mordor Intelligence, the United States HVAC equipment market size was valued at USD 58.55 billion in 2025 and is estimated to grow from USD 60.98 billion in 2026 to reach USD 75.20 billion by 2031, at a CAGR of 4.30% during the forecast period (2026-2031).
This report is Segmented by Equipment Type (Air-Conditioning Equipment, Heating Equipment, and Ventilation Equipment), End User (Residential, Commercial, and Industrial), Implementation Type (New Construction, and Retrofit/Replacement), Efficiency Rating (Low-Efficiency Tier, and High-Efficiency Tier), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
United States HVAC Equipment Market Trends and Insights
Growing Adoption of Home and Building Automation Systems
Commercial developers and large homeowners now evaluate new units by their native connectivity as much as by efficiency. Systems with open APIs integrate seamlessly with facility management platforms, enabling schedule optimization and predictive maintenance that trim energy use by 15-20%. IoT-ready thermostats and zoning kits are becoming base-spec items, shortening replacement cycles because legacy units cannot communicate with modern software. Corporations chasing ESG targets view connected HVAC as low-hanging fruit for measurable carbon cuts, driving bulk procurement during capital-planning cycles. Integrators profit from long-tail software subscriptions, a model that reshapes how revenue is earned throughout the equipment life cycle.
Increasing Demand for Energy-Efficient HVAC Equipment
Title 24 updates, minimum SEER uplifts, and smart-grid interoperability rules have triggered field-level specification shifts toward premium gear. While high-efficiency units carry a 15-25% price premium, rising electricity tariffs and time-of-use billing tilt life-cycle economics in their favour. Utilities now pair demand-response payments with equipment rebates, nudging owners toward variable-speed compressors and cold-climate heat pumps. As electrification marches forward, peak-demand fees become pronounced, sharpening attention on kilowatt-level performance during design. Manufacturers, in response, phase variable refrigerant flow (VRF) features into mainstream product lines to satisfy code and financial metrics simultaneously.
High Upfront Cost of Advanced HVAC Systems
Connected, high-SEER heat pumps cost 30-50% more than legacy furnaces, and adding networked controls lifts project budgets by another 15-20%. For single-family homeowners, the absence of subsidized financing keeps payback periods outside a three-year psychological threshold. Commercial real-estate operators have shortened ROI requirements to five years or less, excluding many cutting-edge offerings. While rebates alleviate some pain, funding caps inject uncertainty into long-term planning. Consequently, many buyers stage upgrades, holding on to sub-optimal solutions for another season.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Federal and State Energy-Efficiency Regulations
- Accelerated Equipment Replacement Cycles in Aging Building Stock
- Skilled Labour Shortages for Installation and Service
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The United States HVAC equipment market size for air-conditioning products stood highest in 2025, when they delivered 47.35% of total value. Cooling remains the core need across U.S. climates, especially in rapidly growing Sun Belt states. Yet heat pumps, aided by federal credits, are forecast to register a 6.21% CAGR through 2031, the fastest among all categories. As cold-climate performance improves, these units take share from both gas furnaces and straight-cool splits.
Regulatory refrigerant bans will accelerate chiller replacements, and vendors that offer R-32 or R-454B compatibility are set to gain volume early in the cycle. Meanwhile, ventilation equipment rises in priority as air-quality norms evolve, and UV-C or MERV-13 filtration is increasingly embedded in packaged units for hospitality and health-care projects. The holistic turn toward indoor environmental quality keeps demand resilient even when new construction slows, supporting the long-run trajectory of the United States HVAC equipment market.
Residential buyers retained a 45.68% slice of the United States HVAC equipment market share in 2025 and are embracing smart controls at an exceptional pace. More than one-third of new single-family homes shipped with connected thermostats that link seamlessly to heat pumps eligible for up to USD 8,000 in IRA credits. While upfront cost sensitivity remains, low-interest utility loans improve the affordability of premium gear.
Commercial demand centers on building automation, occupancy-based ventilation, and ESG-aligned energy reporting. Offices and retail stores pivot toward adaptive operation strategies that cut idle energy draw. Industrial users require tighter temperature and humidity windows for production consistency, reinforcing demand for specialized, high-capacity designs. Though decision cycles lengthen, each transaction is larger, injecting stability into the overall revenue profile of the United States HVAC equipment market.
Complete Report Scope:
- By Equipment Type
- Air-Conditioning Equipment
- Unitary Air Conditioners
- Room Air Conditioners
- Packaged Terminal Air Conditioners
- Chillers
- Heating Equipment
- Warm-Air Furnaces (Gas and Oil)
- Boilers
- Room and Zone Heating Equipment
- Heat Pumps (Air-Source and Geo-thermal)
- Ventilation Equipment
- Air Handling Units
- Fan Coil Units
- Building Humidifiers and Dehumidifiers
- Air-Conditioning Equipment
- By End User
- Residential
- Commercial
- Industrial
- By Implementation Type
- New Construction
- Retrofit / Replacement
- By Efficiency Rating
- Low-Efficiency Tier
- High-Efficiency Tier
List of Companies Covered in this Report:
- Carrier Global Corporation
- Daikin Industries Ltd.
- Trane Technologies plc
- Johnson Controls International plc
- Lennox International Inc.
- Rheem Manufacturing Company
- Mitsubishi Electric Corporation
- Nortek Air Solutions LLC
- NIBE Industrier AB
- LG Electronics Inc.
- Midea Group Co., Ltd.
- Systemair AB
- Greenheck Fan Corporation
- TROX GmbH
- Goodman Manufacturing Company LP
- Bosch Thermotechnology Corp.
- AAON Inc.
- Fujitsu General America Inc.
- Samsung Electronics America Inc.
- Danfoss A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing adoption of home and building automation systems
- 4.2.2 Increasing demand for energy-efficient HVAC equipment
- 4.2.3 Stringent federal and state energy-efficiency regulations
- 4.2.4 Accelerated equipment replacement cycles in aging building stock
- 4.2.5 IRA-driven heat-pump electrification incentives
- 4.2.6 Micro-fulfilment centre boom boosting compact HVAC demand
- 4.3 Market Restraints
- 4.3.1 High upfront cost of advanced HVAC systems
- 4.3.2 Skilled labour shortages for installation and service
- 4.3.3 Electrical-grid capacity constraints for all-electric retrofits
- 4.3.4 Uncertain compliance costs from refrigerant phase-down
- 4.4 Industry Value-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Type
- 5.1.1 Air-Conditioning Equipment
- 5.1.1.1 Unitary Air Conditioners
- 5.1.1.2 Room Air Conditioners
- 5.1.1.3 Packaged Terminal Air Conditioners
- 5.1.1.4 Chillers
- 5.1.2 Heating Equipment
- 5.1.2.1 Warm-Air Furnaces (Gas and Oil)
- 5.1.2.2 Boilers
- 5.1.2.3 Room and Zone Heating Equipment
- 5.1.2.4 Heat Pumps (Air-Source and Geo-thermal)
- 5.1.3 Ventilation Equipment
- 5.1.3.1 Air Handling Units
- 5.1.3.2 Fan Coil Units
- 5.1.3.3 Building Humidifiers and Dehumidifiers
- 5.1.1 Air-Conditioning Equipment
- 5.2 By End User
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Industrial
- 5.3 By Implementation Type
- 5.3.1 New Construction
- 5.3.2 Retrofit / Replacement
- 5.4 By Efficiency Rating
- 5.4.1 Low-Efficiency Tier
- 5.4.2 High-Efficiency Tier
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Carrier Global Corporation
- 6.4.2 Daikin Industries Ltd.
- 6.4.3 Trane Technologies plc
- 6.4.4 Johnson Controls International plc
- 6.4.5 Lennox International Inc.
- 6.4.6 Rheem Manufacturing Company
- 6.4.7 Mitsubishi Electric Corporation
- 6.4.8 Nortek Air Solutions LLC
- 6.4.9 NIBE Industrier AB
- 6.4.10 LG Electronics Inc.
- 6.4.11 Midea Group Co., Ltd.
- 6.4.12 Systemair AB
- 6.4.13 Greenheck Fan Corporation
- 6.4.14 TROX GmbH
- 6.4.15 Goodman Manufacturing Company LP
- 6.4.16 Bosch Thermotechnology Corp.
- 6.4.17 AAON Inc.
- 6.4.18 Fujitsu General America Inc.
- 6.4.19 Samsung Electronics America Inc.
- 6.4.20 Danfoss A/S
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 歐洲暖通空調設備:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 暖通空調設備市場報告:趨勢、預測與競爭分析(至2035年)北美暖通空調設備:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)暖通空調設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 北美暖通空調設備,2023-2031年Frost Radar(TM):暖通空調設備,2026 年暖通空調馬達市場:全球產業分析、市場規模及佔有率和預測(2026-2033 年)-按馬達類型、額定功率、暖通空調設備類型、最終用途、國家和地區分類
 暖通空調設備市場:2026-2032年全球市場預測(按組件、技術、燃料類型、容量、最終用途、安裝類型和分銷管道分類)全球暖通空調設備市場(2026-2031年)暖通空調馬達:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)