


 |
市場調查報告書
商品編碼
2124399
歐洲暖通空調設備:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Europe HVAC Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
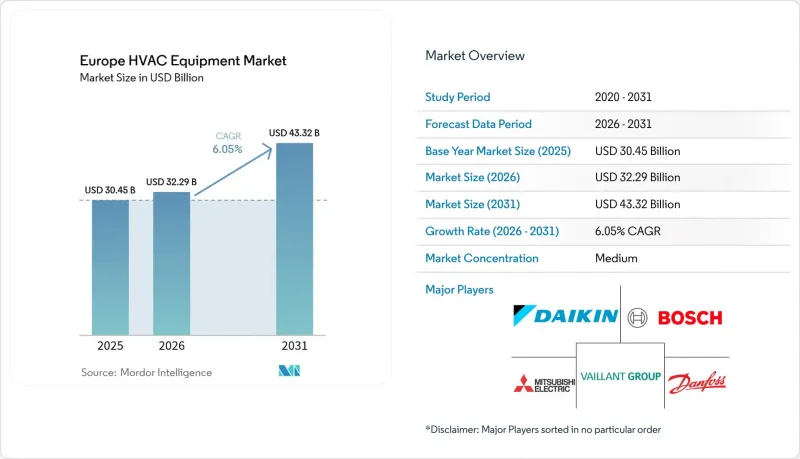
據 Mordor Intelligence 稱,歐洲 HVAC 設備市場預計到 2026 年價值將達到 322.9 億美元,高於 2025 年的 304.5 億美元,預計到 2031 年將達到 433.2 億美元。
預計 2026 年至 2031 年的複合年成長率為 6.05%。
本報告按設備類型(空調和通風系統、暖氣系統)、最終用戶產業(住宅、商業、工業/製造業、其他)、安裝類型(新建、維修/更換)、分銷管道(OEM-安裝商網路、批發商/分銷商、其他)和國家(德國、英國、法國、義大利、西班牙、俄羅斯、其他國家)進行分類。
歐洲暖通空調設備市場趨勢與洞察
歐盟綠色交易的能源效率要求正在推動市場轉型。
歐盟於2024年實施的強制性最低能源效率標準,以及一項560億歐元(約655.7億美元)的熱泵安裝激勵計劃,大大改變了設備需求格局。 2025年第一季,德國的熱泵安裝量達到4.3萬台,較上年同期成長60%。補貼政策推動了空氣源熱泵的銷售量激增,從2.2萬台增加到近3.8萬台,凸顯了政策制定者對熱泵與熱水循環系統整合的重視。儘管荷蘭在2025年減少了ISDE補貼,但該國仍計劃在2030年實現20%的住宅安裝熱泵,這有助於歐洲暖通空調設備市場維持9.7%的複合年成長率。製造商正積極回應,採用天然冷媒設計,並提供免除買家前期成本的資金籌措方案。
更換老舊鍋爐正在加速市場擴張。
2024年,天然氣價格上漲和更嚴格的碳排放處罰導致歐洲約1.3億台老舊鍋爐達到使用壽命終點。原始設備製造商(OEM)加快併購步伐以確保安裝商,大金於2024年8月收購瑞典Kylslaget AB公司就是一個典型例子。專為維修設計的熱泵,在設計時充分考慮了與現有水循環系統的兼容性,從而縮短了安裝時間,提高了安裝人員的工作效率,即使在新建項目相對較少的市場,也刺激了更換需求。
高昂的初始投資成本阻礙了市場滲透。
熱泵系統的成本仍然是鍋爐更換的三到五倍,儘管有補貼,但對於東歐和農村地區的家庭來說,這仍然是一個障礙。原始設備製造商(OEM)實施的複雜資金籌措方案增加了行政障礙,並延長了銷售週期。在可支配收入較低的地區,歐洲暖通空調設備市場的擴張主要依靠公共資助的社會住宅項目,而不是個人購買。
細分市場分析
地源熱泵的成長率最高,到2031年年複合成長率(CAGR)將達到9.78%,而空調和通風設備在歐洲暖通空調設備市場中佔最大佔有率,達到57.95%。機構投資者更青睞地源熱泵解決方案,因為其季節能源效率高、使用壽命長,足以抵消住宅用戶通常不願承擔的鑽井成本。北歐的地質條件適宜建設閉合迴路鑽井場,安裝商報告稱,兆瓦級園區計畫數量正在增加。
同時,在暖氣系統維修,空氣源熱泵仍然是主流技術,由於其能夠利用現有散熱器並簡化石化燃料的淘汰流程,因此在政策層面受到優先考慮。大金公司於2025年3月發布的R-290模組化平台體現了向天然冷媒的過渡,在滿足F-gas法規要求的同時,提高了部分負荷效率。在較冷的內陸地區,混合式鍋爐-水泵組件已被用作臨時解決方案。這些創新技術的結合,正在推動歐洲暖通空調設備市場從燃氣式整體系統轉型為電動系統,性能絲毫不減。
2025年,住宅用戶佔銷售額的46.80%,而公共和機構設施、學校和醫院預計將以10.05%的最高複合年成長率成長,並預計在2031年擴大其在歐洲暖通空調設備市場的佔有率。政府的脫碳預算資助了大規模的維修項目,這些項目結合了熱泵和需量反應通風系統。
儘管機構專案週期長、交易量有保障,但原始設備製造商 (OEM) 仍熱衷於提供能源即服務 (EaaS) 契約,將設備、維護和監控打包在一起。注重環境、社會和治理 (ESG) 的業主對商業辦公大樓的需求持續穩定,而工業設施則在探索整合製程熱回收系統。這些多樣化的用戶需求正促使供應商拓展產品線並開發軟體分析能力,進一步增強其在歐洲暖通空調設備市場的競爭優勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素的影響
- 市場促進因素
- 歐盟綠色新政關於提高能源效率的義務以及對熱泵的補貼
- 老舊鍋爐設備的更換正在加速進行中。
- 夏季高溫天氣日益加劇,導致住宅空調的使用率不斷提高。
- 商用空調系統維修中的快速電氣化
- 隨著 F-gas 法規的修訂,丙烷 (R290) 熱泵已經上市。
- 擴大安裝人員培訓計畫將刺激潛在需求。
- 市場限制因素
- 與燃氣鍋爐相比,初始設備投資較高。
- 供應鏈和商品價格引發的通貨膨脹
- 由於技術純熟勞工短缺,安裝工作延誤了。
- 由於冷媒過渡的不確定性,OEM設備升級面臨風險。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過裝置
- 空調/通風設備
- 單分離式和多分離式空調機組
- 可變冷媒流量(VRF)系統
- 空調機組(AHU)
- 冷卻器
- 風機盤管機組
- 包裝類型/屋頂類型
- 其他空調和通風設備
- 加熱設備
- 空氣-水熱泵
- 地源熱泵
- 鍋爐/爐子/散熱器
- 混合熱泵系統
- 空調/通風設備
- 按最終用戶行業分類
- 住宅
- 商業設施(辦公大樓、零售店、飯店)
- 工業和製造業
- 公共和機構設施
- 按安裝類型
- 新建工程
- 改裝/更換
- 透過分銷管道
- OEM和安裝承包商網路
- 批發商/分銷商
- 直接面對消費者與電子商務
- 國家
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Daikin Industries Ltd.
- Carrier Global Corporation
- Mitsubishi Electric Corporation
- Robert Bosch GmbH(Bosch Thermotechnology)
- Vaillant Group
- Danfoss A/S
- Lennox International Inc.
- Panasonic Corporation
- Ariston Holding NV
- BDR Thermea Group BV
- Hitachi Ltd.(Johnson Controls-Hitachi)
- Johnson Controls International plc
- Systemair AB
- NIBE Industrier AB
- Glen Dimplex Group
- Fujitsu General Limited
- LG Electronics Inc.
- Samsung Electronics Co. Ltd.
- Trane Technologies plc
- Viessmann Climate Solutions SE
- STIEBEL ELTRON GmbH & Co. KG
- Gree Electric Appliances Inc. of Zhuhai
- Midea Group Co. Ltd.
- Arcelik AS
- Riello SpA
- Armacell SA
- Thermondo GmbH
- Enertech AB(CTC)
第7章 市場機會與未來展望
According to Mordor Intelligence, european HVAC equipment market size in 2026 is estimated at USD 32.29 billion, growing from 2025 value of USD 30.45 billion with 2031 projections showing USD 43.32 billion, growing at 6.05% CAGR over 2026-2031.
This report is Segmented by Equipment (Air-Conditioning/Ventilation Equipment, and Heating Equipment), End-User Industry (Residential, Commercial, Industrial and Manufacturing, and More), Installation Type (New Construction, and Retrofit/Replacement), Distribution Channel (OEM-Installer Networks, Wholesale/Distributor, and More), and Country (Germany, United Kingdom, France, Italy, Spain, Russia, and More).
Europe HVAC Equipment Market Trends and Insights
EU Green Deal efficiency mandates drive market transformation
Mandatory minimum-efficiency standards and EUR 56 billion (USD 65.57 billion) in heat-pump incentives rolled out across the bloc in 2024 reshaped equipment demand, pushing heat-pump installations in Germany up 60% year-over-year to 43,000 units in Q1 2025. Subsidies favored air-to-water models whose sales jumped from 22,000 to nearly 38,000 units, underscoring policymakers' bias toward hydronic integration. Although Dutch ISDE rebates were reduced in 2025, the Netherlands still aims to install heat pumps in 20% of homes by 2030, sustaining a 9.7% CAGR for the European HVAC equipment market. Manufacturers have responded with natural-refrigerant designs and financing schemes that shield buyers from upfront costs.
Aging boiler replacement accelerates market expansion
Roughly 130 million legacy boilers across Europe became ripe for swap-out as gas prices climbed in 2024 and carbon penalties tightened. OEMs accelerated M&A to secure installer capacity, highlighted by Daikin's purchase of Sweden-based Kylslaget AB in August 2024. Retrofit-oriented heat-pumps engineered for compatibility with existing hydronic circuits shortened installation times and boosted contractor productivity, lifting replacement demand even in markets with modest new-build volumes.
High upfront capital expenditure constrains market penetration
Heat-pump systems still cost 3-5 times more than a boiler swap, deterring households in Eastern Europe and rural districts despite subsidies. Complex financing packages introduced by OEMs raise administrative hurdles and slow sales cycles. Where disposable income is lower, the European HVAC equipment market expands largely through publicly funded social-housing programs rather than private purchases.
Other drivers and restraints analyzed in the detailed report include:
- Summer heatwave intensity reshapes residential AC demand
- Commercial HVAC electrification gains momentum
- Supply-chain inflation pressures profitability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ground-source heat pumps recorded the fastest 9.78% CAGR through 2031, even though air-conditioning and ventilation maintained the largest 57.95% share within the European HVAC equipment market. Institutional buyers favored geothermal solutions that deliver higher seasonal efficiencies and longer lifespans, justifying the drilling expenses that residential customers often avoid. As Nordic geology supports closed-loop borefields, installers are reporting an increase in multi-megawatt campus-scale projects.
In parallel, air-to-water heat pumps remained dominant in heating retrofits, leveraging existing radiators and earning policy preference due to their simplification of the fossil-fuel phase-out. Daikin's R-290 modular platform, unveiled in March 2025, exemplified the natural-refrigerant progression that meets F-Gas regulations while enhancing part-load efficiency. Hybrid boiler-pump kits gained traction as interim solutions in colder interiors. Collectively, these innovations sustain the European HVAC equipment market's technology shift from gas-fired packages to electrified variants without sacrificing performance.
Residential users contributed 46.80% of 2025 sales, while public and institutional estates, schools, and hospitals are projected to post the highest 10.05% CAGR, increasing their share of the European HVAC equipment market size by 2031. Government decarbonization budgets funded large-scale retrofits that pair heat pumps with demand-controlled ventilation.
Institutional project cycles are longer but guarantee volume, encouraging OEMs to offer energy-as-a-service contracts that bundle equipment, maintenance, and monitoring. Commercial offices continue to experience steady demand from ESG-driven landlords, while industrial sites explore process heat recovery integrations. These varied user needs prompt suppliers to expand their portfolios and develop software analytics capabilities, further driving competitive differentiation in the European HVAC equipment market.
Complete Report Scope:
- By Equipment
- Air-Conditioning / Ventilation Equipment
- Single-Split and Multi-Split Units
- Variable Refrigerant Flow (VRF) Systems
- Air-Handling Units (AHU)
- Chillers
- Fan-Coil Units
- Packaged / Rooftop Units
- Other AC / Ventilation Equipment
- Heating Equipment
- Air-to-Water Heat Pumps
- Ground-Source Heat Pumps
- Boilers / Furnaces / Radiators
- Hybrid Heat-Pump Systems
- Air-Conditioning / Ventilation Equipment
- By End-User Industry
- Residential
- Commercial (Offices, Retail, Hospitality)
- Industrial and Manufacturing
- Institutional and Public Buildings
- By Installation Type
- New Construction
- Retrofit / Replacement
- By Distribution Channel
- OEM-Installer Networks
- Wholesale / Distributor
- Direct-to-Consumer and E-commerce
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Daikin Industries Ltd.
- Carrier Global Corporation
- Mitsubishi Electric Corporation
- Robert Bosch GmbH (Bosch Thermotechnology)
- Vaillant Group
- Danfoss A/S
- Lennox International Inc.
- Panasonic Corporation
- Ariston Holding N.V.
- BDR Thermea Group B.V.
- Hitachi Ltd. (Johnson Controls-Hitachi)
- Johnson Controls International plc
- Systemair AB
- NIBE Industrier AB
- Glen Dimplex Group
- Fujitsu General Limited
- LG Electronics Inc.
- Samsung Electronics Co. Ltd.
- Trane Technologies plc
- Viessmann Climate Solutions SE
- STIEBEL ELTRON GmbH & Co. KG
- Gree Electric Appliances Inc. of Zhuhai
- Midea Group Co. Ltd.
- Arcelik A.S.
- Riello S.p.A.
- Armacell S.A.
- Thermondo GmbH
- Enertech AB (CTC)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Market Drivers
- 4.3.1 EU Green-Deal efficiency mandates and heat-pump subsidies
- 4.3.2 Accelerating replacement of ageing boiler stock
- 4.3.3 Intensifying summer heatwaves boosting residential AC uptake
- 4.3.4 Rapid electrification of commercial HVAC retrofits
- 4.3.5 Propane (R290) heat-pump launches post-F-Gas revision
- 4.3.6 Scale-up of installer-training programs unlocking latent demand
- 4.4 Market Restraints
- 4.4.1 High upfront capex versus gas boilers
- 4.4.2 Supply-chain and commodity-price inflation
- 4.4.3 Skilled-labour bottlenecks delaying installations
- 4.4.4 OEM re-tooling risk amid refrigerant transition uncertainty
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment
- 5.1.1 Air-Conditioning / Ventilation Equipment
- 5.1.1.1 Single-Split and Multi-Split Units
- 5.1.1.2 Variable Refrigerant Flow (VRF) Systems
- 5.1.1.3 Air-Handling Units (AHU)
- 5.1.1.4 Chillers
- 5.1.1.5 Fan-Coil Units
- 5.1.1.6 Packaged / Rooftop Units
- 5.1.1.7 Other AC / Ventilation Equipment
- 5.1.2 Heating Equipment
- 5.1.2.1 Air-to-Water Heat Pumps
- 5.1.2.2 Ground-Source Heat Pumps
- 5.1.2.3 Boilers / Furnaces / Radiators
- 5.1.2.4 Hybrid Heat-Pump Systems
- 5.1.1 Air-Conditioning / Ventilation Equipment
- 5.2 By End-User Industry
- 5.2.1 Residential
- 5.2.2 Commercial (Offices, Retail, Hospitality)
- 5.2.3 Industrial and Manufacturing
- 5.2.4 Institutional and Public Buildings
- 5.3 By Installation Type
- 5.3.1 New Construction
- 5.3.2 Retrofit / Replacement
- 5.4 By Distribution Channel
- 5.4.1 OEM-Installer Networks
- 5.4.2 Wholesale / Distributor
- 5.4.3 Direct-to-Consumer and E-commerce
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Russia
- 5.5.7 Netherlands
- 5.5.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Daikin Industries Ltd.
- 6.4.2 Carrier Global Corporation
- 6.4.3 Mitsubishi Electric Corporation
- 6.4.4 Robert Bosch GmbH (Bosch Thermotechnology)
- 6.4.5 Vaillant Group
- 6.4.6 Danfoss A/S
- 6.4.7 Lennox International Inc.
- 6.4.8 Panasonic Corporation
- 6.4.9 Ariston Holding N.V.
- 6.4.10 BDR Thermea Group B.V.
- 6.4.11 Hitachi Ltd. (Johnson Controls-Hitachi)
- 6.4.12 Johnson Controls International plc
- 6.4.13 Systemair AB
- 6.4.14 NIBE Industrier AB
- 6.4.15 Glen Dimplex Group
- 6.4.16 Fujitsu General Limited
- 6.4.17 LG Electronics Inc.
- 6.4.18 Samsung Electronics Co. Ltd.
- 6.4.19 Trane Technologies plc
- 6.4.20 Viessmann Climate Solutions SE
- 6.4.21 STIEBEL ELTRON GmbH & Co. KG
- 6.4.22 Gree Electric Appliances Inc. of Zhuhai
- 6.4.23 Midea Group Co. Ltd.
- 6.4.24 Arcelik A.S.
- 6.4.25 Riello S.p.A.
- 6.4.26 Armacell S.A.
- 6.4.27 Thermondo GmbH
- 6.4.28 Enertech AB (CTC)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 美國暖通空調設備:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 暖通空調設備市場報告:趨勢、預測與競爭分析(至2035年)北美暖通空調設備:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)暖通空調設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 北美暖通空調設備,2023-2031年Frost Radar(TM):暖通空調設備,2026 年暖通空調馬達市場:全球產業分析、市場規模及佔有率和預測(2026-2033 年)-按馬達類型、額定功率、暖通空調設備類型、最終用途、國家和地區分類
 暖通空調設備市場:2026-2032年全球市場預測(按組件、技術、燃料類型、容量、最終用途、安裝類型和分銷管道分類)全球暖通空調設備市場(2026-2031年)暖通空調馬達:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)