


 |
市場調查報告書
商品編碼
2073237
肉牛飼料添加劑:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Beef Cattle Feed Additives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,肉牛飼料添加劑市場規模將從 2025 年的 40.4 億美元成長到 2026 年的 42.7 億美元,到 2031 年將達到 54.9 億美元,2026 年至 2031 年的複合年成長率為 5.15%。
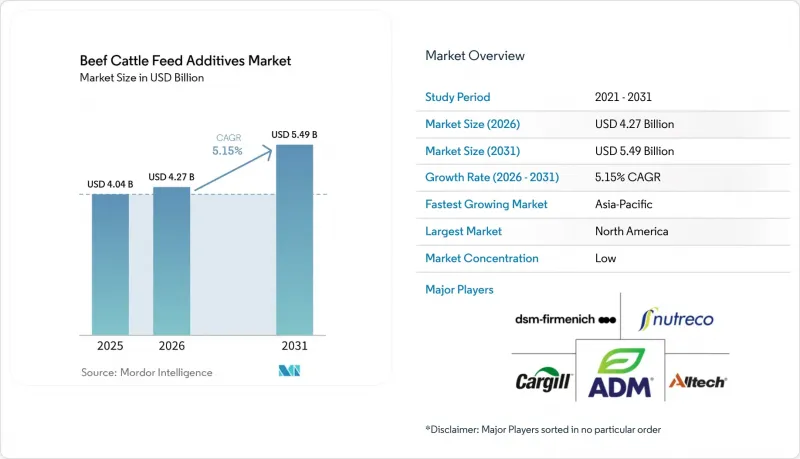
本報告按添加劑類型(酸味劑、抗生素、抗氧化劑、氨基酸、粘合劑、酵素、香料和甜味劑、礦物質、黴菌毒素解毒劑等)、形態(乾燥劑和液體)以及地區(北美、南美、歐洲、亞太、中東和非洲)進行細分。市場預測以價值和銷售量為基礎。
全球肉牛飼料添加劑市場趨勢及洞察
商業育肥場希望提高飼料轉換率和日產量,因此提出了需求。
大規模育肥系統仍然是肉牛飼料添加劑市場最穩定的需求基礎,因為其經濟效益取決於可衡量的飼料轉換率和增重。世界資源研究所 (WRI) 報告稱,2025 年,減甲烷飼料添加劑是商業性程度最高的畜牧業排放技術之一,平均甲烷減量約為 30%,某些技術在受控條件下可實現 90% 以上的減排量。這種程度的普及表明,在大型集約化養殖系統中,性能增強型添加劑不再僅僅被視為可選項,而是被視為營運必需品。隨著穀物價格上漲,即使飼料轉換率略有提高,其經濟價值也隨之增加,有助於在利潤率承壓的情況下維持強勁的需求。基於類似的邏輯,目前南美洲的集約化養殖系統也在擴大應用,越來越多的生產者正在根據當地的育肥經濟情況檢驗高濃度飼料方案的有效性。
從抗生素類生長促進劑過渡到改善腸道環境的添加劑
在受監管的畜牧系統中,減少使用抗生素生長促進劑的做法正在對市場產生積極影響。這項轉變商業性買家將目光轉向益生菌、益生元、有機酸和酵母萃取物等成分,這些成分能夠在接收和育肥階段維持穩定的採食量和腸道功能。事實上,許多生產者並非簡單地用一種抗生素產品取代另一種,而是實施多層次的方案,整合多種添加劑以滿足不同的消化器官系統和健康需求。那些經過權威認證流程的產品,例如美國的「公認安全 (GRAS)」認證或歐洲食品安全局 (EFSA) 的批准,正獲得市場青睞,因為買家越來越重視合規性證明。這種選擇性效應使擁有豐富監管經驗的大型供應商佔據優勢,並提高了整個肉牛飼料添加劑市場的平均技術水平。
嚴格核准和遵守殘留標準所帶來的負擔
嚴格的核准流程顯著延緩了新型生物來源和特種產品的商業化。在美國,食品藥物管理局(FDA) 對藥用飼料配方採用新動物用藥品申請 (NADA) 流程,通常需要三到五年才能完成。在歐盟,(EC) 1831/2003 號法規強制要求進行安全評估,評估內容涵蓋對動物健康、人類健康和環境的影響,並維持著高標準的審查。出口市場進一步加劇了這項流程的複雜性,因為出口到日本、韓國或歐盟等地區的生產商必須遵守最嚴格的殘留限量標準。因此,在肉牛飼料添加劑市場,擁有強大合規能力的公司往往比產品開發週期更快的公司更具優勢。
細分市場分析
到2025年,胺基酸將佔肉牛飼料添加劑市場佔有率的20.8%,成為最大的添加劑類型。這一地位反映了胺基酸在最佳化整個育肥、飼養和牛-牛育肥系統中的蛋白質效率、瘦肉組織積累和氮利用方面所發揮的重要作用。成長最快的添加劑類型是抗氧化劑,預計從2026年到2031年將以6.7%的複合年成長率成長,這主要歸因於飼料儲存期延長以及高能量飼料配方帶來的氧化風險增加。在肉牛飼料添加劑市場,對天然抗氧化劑系統(例如生育酚和檸檬酸)的需求在出口敏感型應用中也日益成長。這種需求模式正在加速抗氧化劑在對品質要求極高的飼餵系統中的成長,而胺基酸仍然是提高生產力計畫的核心。
在肉牛飼料添加劑產業,益生菌和益生元在飼料接受度和過渡方案中發揮越來越重要的作用,因為穩定腸道環境與控制健康管理成本密切相關。隨著買家在抗生素停用後的管理中對更廣泛的消化器官系統支持需求增加,多菌株產品比單菌株產品更具吸引力。酵母產品的作用也在不斷擴大,從小眾補充劑用途擴展到常規添加到育肥飼料中,以滿足改善瘤胃pH平衡和纖維利用率的需求。歐盟委員會已批准釀酒酵母CNCM I-4407於2025年作為育肥牛飼料添加劑,這將提升活性酵母系統在監管市場中的商業性地位。雖然礦物質和維生素仍然是牛飼料添加劑市場的重要基礎類別,但成長構成比正轉向那些能夠更直接解決飼料配方穩定性、腸道健康和飼料保存問題的產品。
區域分析
到2025年,北美將佔肉牛飼料添加劑市場59.1%的佔有率,成為最大的區域市場。這一區域地位反映了美國育肥場模式的技術進步,在這種模式下,多種添加劑已成為高濃度育肥飼料的標準配置。目前,北美肉牛飼料添加劑市場的主要驅動力是甲烷減排項目、精準氨基酸使用以及旨在降低發病率和提高胴體品質的腸道健康產品。與其他成長更快的地區相比,預計北美市場的成長將保持溫和,因為主要商業系統中核心性能增強添加劑的採用率已經很高。未來,該地區的價值創造可能更依賴擁有更可靠實證數據的高級產品,而非簡單的銷售量擴張。
由於南美洲擁有龐大的牛數量和龐大的添加劑應用成長空間,該地區仍然是肉牛飼料添加劑市場成長最快的新興地區。 2024年至2025年間,巴西的牛群數量超過2.2億頭,凸顯了該地區的規模及其在長期添加劑需求中的重要性。最大的成長潛力在於封閉式或半集約化育肥系統中飼養的牛數量不斷增加,這些系統需要系統化的飼餵和更穩定的營養管理。 2024年,帝斯曼-菲美尼奇在巴西塞特拉戈阿斯開設了一家新的動物營養工廠。該工廠每年可生產10萬噸牛和牛補充劑,將加強產業對巴西反芻動物營養價值鏈的投資,並促進未來商業性肉牛牛系統中添加劑的應用。阿根廷的需求也得到了支持。這是因為在銅、鋅和硒缺乏會顯著降低牛生產力的養殖系統中,生產者正在採用更有針對性的礦物質補充方案。
歐洲是成熟且高度專業化的肉牛飼料添加劑市場,需求主要集中在受監管的酵母產品、植物來源成分、胺基酸和甲烷相關解決方案。亞太地區是成長最快的區域市場,預計2026年至2031年將以5.9%的複合年成長率成長,這主要得益於中國及其周邊市場育肥場的擴張和監管現代化。在中國,2026年1月擴大了胍基乙酸在牛全混合日糧(TMR)中的使用範圍。這表明,在不斷發展的商業性體系中,公眾對提高生產力的添加劑的支持日益增強。德赫斯動物營養有限公司(De Heus Animal Nutrition BV)的業務遍及東南亞和撒哈拉以南非洲地區,這些地區不斷成長的牛數量和飼料現代化正在催生對更系統化添加劑方案的初步需求。中東地區為肉牛飼料添加劑市場提供了獨特的機會。熱壓力、對進口飼料的依賴以及較長的儲存週期推動了抗氧化劑、酸化劑和礦物質預混合料的持續使用。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 商業育肥場對提高飼料轉換率和每日增重的需求。
- 從抗生素類生長促進劑過渡到腸道健康添加劑
- 牛飼料中黴菌毒素含量增加,粗飼料的變異性增加。
- 引入精準的礦物質和胺基酸補充劑
- 碳排放對甲烷減量添加劑的需求
- 含有大量特定產品成分的飼料需要添加更多穩定劑。
- 市場限制因素
- 遵守嚴格的核准和保留標準的負擔。
- 維生素、胺基酸和發酵產品的原料成本波動
- 一些甲烷減排物質在放牧系統中的應用有限。
- 由於農場數據收集不足,投資回報率的檢驗被推遲。
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 添加劑
- 酸味劑
- 乳酸
- 丙酸
- 富馬酸
- 其他酸味劑
- 抗生素
- 四環黴素抗生素
- 青黴素
- 泰樂菌素
- 巴氏桿菌
- 其他抗生素
- 抗氧化劑
- 丁基Hydroxyanisole(BHA)
- 二丁基羥基甲苯(BHT)
- 乙氧喹
- 沒食子酸丙酯
- 生育酚
- 檸檬酸
- 其他抗氧化劑
- 胺基酸
- 離胺酸
- 色氨酸
- 甲硫胺酸
- 蘇胺酸
- 其他胺基酸
- 活頁夾
- 天然黏合劑
- 合成黏合劑
- 酵素
- 碳水化合物消化酶
- 植酸酶
- 其他酵素
- 調味劑和甜味劑
- 香味
- 甜味劑
- 礦物
- 主要礦物
- 微量礦物質
- 黴菌毒素清除劑
- 粘合劑
- 生物轉化劑
- 植物源
- 香草和香辛料
- 精油
- 其他植物源性物質
- 顏料
- 類胡蘿蔔素
- 薑黃素和螺旋藻
- 益生元
- 菊糖
- 果寡糖
- 半乳寡糖
- 木寡糖
- 乳果糖
- 甘露聚醣
- 其他益生元
- 益生菌
- 乳酸菌
- 雙歧桿菌
- 鏈球菌
- 片球菌
- 腸球菌
- 其他益生菌
- 維他命
- 維生素A
- 維生素B
- 維生素C
- 維生素E
- 其他維生素
- 東方
- 新鮮酵母
- 用過的酵母
- 托魯拉乾酵母
- 硒酵母
- 乳清酵母
- 酵母衍生成分
- 酸味劑
- 按形式
- 乾燥
- 液體
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 荷蘭
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 紐西蘭
- 韓國
- 印尼
- 泰國
- 越南
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 土耳其
- 伊朗
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 肯亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cargill, Incorporated
- Archer Daniels Midland Company
- Nutreco NV(SHV Holdings NV)
- DSM-Firmenich AG
- Alltech, Inc.
- Kemin Industries, Inc.
- BASF SE
- Evonik Industries AG
- Elanco Animal Health Incorporated
- Novus International, Inc.
- Bluestar Adisseo Company
- Lallemand Inc.
- Zinpro Corporation
- Land O'Lakes, Inc.
- De Heus Animal Nutrition BV(Royal De Heus)
第7章 市場機會與未來展望
According to Mordor Intelligence, the beef cattle feed additives market size is projected to grow from USD 4.04 billion in 2025 to USD 4.27 billion in 2026 and is forecast to reach USD 5.49 billion by 2031 at 5.15% CAGR over 2026-2031.
This report is Segmented by Additive Type (Acidifiers, Antibiotics, Antioxidants, Amino Acids, Binders, Enzymes, Flavors and Sweeteners, Minerals, Mycotoxin Detoxifiers, and More), by Form (Dry and Liquid), and by Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value and Volume.
Global Beef Cattle Feed Additives Market Trends and Insights
Commercial Feedlot Demand for Better Feed Conversion and Daily Gain
Large feedlot systems remain the most stable demand base in the beef cattle feed additives market because their economics depend on measurable feed efficiency and weight gain. In 2025, the World Resources Institute (WRI) reported that methane-inhibiting feed additives are among the most commercially advanced livestock emission-reduction technologies, with average methane reductions of around 30% and some technologies achieving reductions exceeding 90% under controlled conditions. That level of use shows that performance additives in major confinement systems are treated as operating necessities rather than optional inputs. When grain costs rise, the financial value of even modest improvements in feed conversion becomes more apparent, helping keep demand resilient amid margin pressure. The same logic is now strengthening adoption in South American confinement systems, where more producers are validating high-concentrate feeding programs against local finishing economics.
Shift from Antibiotic Growth Promoters to Gut-Health Additives
The market is benefiting from the move away from antibiotic growth promoters in regulated livestock systems. This change is pushing commercial buyers toward probiotics, prebiotics, organic acids, and yeast derivatives that can support intake stability and gut function in receiving and finishing phases. In practice, many producers are not substituting one antibiotic product for another. Instead, they implement layered programs that incorporate multiple additive types to address various digestive and health needs. Products that move through recognized approval pathways, such as the Generally Recognized as Safe (GRAS) route in the United States and authorization reviews under the European Food Safety Authority (EFSA), gain stronger commercial traction because buyers place greater value on documented compliance. That sorting effect favors larger suppliers with regulatory depth and raises the average technical standard across the beef cattle feed additives market.
Tight Approval and Residue-Compliance Burden
The stringent approval processes significantly slow the commercialization of new biological and specialty products. In the United States, the Food and Drug Administration (FDA) employs the New Animal Drug Application (NADA) process for medicated feed combinations, which typically takes 3 to 5 years to complete. In the European Union, Regulation (EC) No 1831/2003 mandates safety evaluations covering animal health, human health, and environmental impact, maintaining a high review standard. Export markets further complicate the process, as producers exporting to regions such as Japan, South Korea, or the European Union must comply with the strictest residue limits. Consequently, the beef cattle feed additives market tends to favor companies with robust regulatory capabilities over those with faster product development cycles.
Other drivers and restraints analyzed in the detailed report include:
- Higher Mycotoxin and Forage Variability in Beef Rations
- Carbon-Insetting Demand for Methane-Reducing Additives
- Limited Grazing-System Fit for Some Methane Inhibitors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Amino acids accounted for 20.8% of the beef cattle feed additives market share in 2025, making them the largest additive type. Their position reflects a clear role in protein efficiency, lean tissue deposition, and nitrogen use optimization across finishing, growing, and cow-calf systems. The fastest-growing additive type is antioxidants, which are projected to expand at a 6.7% CAGR during 2026-2031 as feed storage periods lengthen and higher-energy rations increase oxidation risk. The beef cattle feed additives market is also seeing stronger trade preference for natural antioxidant systems, such as tocopherols and citric acid, in export-sensitive applications. That demand pattern keeps amino acids central to performance programs while giving antioxidants a faster expansion path in more quality-conscious feeding systems.
Within the broader beef cattle feed additives industry, probiotics and prebiotics are gaining a stronger role in receiving and transition programs, where gut stability is closely tied to health cost control. Multi-strain formats are becoming more attractive than single-strain products because buyers want broader digestive support in post-antibiotic management. Yeast products are also advancing from a niche support role to a more regular inclusion in feedlot diets that need rumen pH balance and stronger fiber utilization. The European Commission authorized Saccharomyces cerevisiae CNCM I-4407 as a feed additive for cattle for fattening in 2025, which supports the commercial standing of live yeast systems in regulated markets. The beef cattle feed additives market still relies on minerals and vitamins as foundational categories, but the growth mix is shifting toward products that solve ration stability, gut health, and feed preservation issues more directly.
Complete Report Scope:
- By Additive
- Acidifiers
- Lactic Acid
- Propionic Acid
- Fumaric Acid
- Other Acidifiers
- Antibiotics
- Tetracyclines
- Penicillins
- Tylosin
- Bacitracin
- Other Antibiotics
- Antioxidants
- Butylated Hydroxyanisole (BHA)
- Butylated Hydroxytoluene (BHT)
- Ethoxyquin
- Propyl Gallate
- Tocopherols
- Citric Acid
- Other Antioxidants
- Amino Acids
- Lysine
- Tryptophan
- Methionine
- Threonine
- Other Amino Acid
- Binders
- Natural Binders
- Synthetic Binders
- Enzymes
- Carbohydrases
- Phytases
- Other Enzymes
- Flavors and Sweeteners
- Flavors
- Sweeteners
- Minerals
- Macrominerals
- Microminerals
- Mycotoxin Detoxifiers
- Binders
- Biotransformers
- Phytogenics
- Herbs & Spices
- Essential Oil
- Other Phytogenics
- Pigments
- Carotenoids
- Curcumin & Spirulina
- Prebiotics
- Inulin
- Fructo Oligosaccharides
- Galacto Oligosaccharides
- Xylo Oligosaccharides
- Lactulose
- Mannan Oligosaccharides
- Other Prebiotics
- Probiotics
- Lactobacilli
- Bifidobacteria
- Streptococcus
- Pediococcus
- Enterococcus
- Other Probiotics
- Vitamins
- Vitamin A
- Vitamin B
- Vitamin C
- Vitamin E
- Other Vitamins
- Yeast
- Live Yeast
- Spent Yeast
- Torula Dried Yeast
- Selenium Yeast
- Whey Yeast
- Yeast Derivatives
- Acidifiers
- By Form
- Dry
- Liquid
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- New Zealand
- South Korea
- Indonesia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- Turkey
- Iran
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America held 59.1% of the beef cattle feed additives market share in 2025, which made it the largest regional segment. The region's position reflects the technical intensity of the United States feedlot model, where multiple additive classes are already standard in high-concentrate finishing rations. The beef cattle feed additives market in North America is now driven by demand for methane-reduction programs, precision amino acid use, and gut-health products for the receiving phase that address morbidity and carcass-quality goals. Growth will likely stay moderate compared with faster regions because baseline adoption of core performance additives is already high in the most commercial systems. Future value creation in this region is likely to come more from premium products with stronger documentation than from simple volume expansion.
South America remains the highest-growth emerging region in the beef cattle feed additives market, as its cattle base is large and additive penetration still has room to grow. Brazil's cattle herd exceeded 220 million head during the 2024-2025 period, confirming the region's scale and its relevance to long-term additive demand. The growth case is strongest where more cattle are moving through confinement or semi-intensive finishing systems that require structured feeding and more consistent nutritional intervention. In 2024, DSM-Firmenich inaugurated a new animal nutrition facility in Sete Lagoas, Brazil, with the capacity to produce 100,000 metric tons of supplements annually for beef and dairy cattle, reinforcing industry investment in the Brazilian ruminant nutrition value chain and supporting future additive penetration across commercial beef systems. Argentina also supports demand because producers are using more targeted mineral programs in systems where deficiencies in copper, zinc, and selenium can materially reduce calf performance.
Europe remains a mature but specialized part of the beef cattle feed additives market, with demand centered on regulated yeast products, phytogenics, amino acids, and methane-related solutions. Asia-Pacific is the fastest regional segment and is projected to expand at 5.9% CAGR during 2026-2031, supported by feedlot growth and regulatory modernization in China and nearby markets. China expanded the approved use of guanidinoacetic acid for beef fattening cattle in Total Mixed Ration (TMR) programs in January 2026, which shows official support for performance additives in a growing commercial system. De Heus Animal Nutrition B.V. maintains operations across Southeast Asia and Sub-Saharan Africa, where cattle population growth and feed modernization are creating early-stage demand for more formal additive programs. The Middle East presents a distinct opportunity set for the beef cattle feed additives market, as heat stress, reliance on imported feed, and long storage cycles support steady use of antioxidants, acidifiers, and mineral premixes.
- Cargill, Incorporated
- Archer Daniels Midland Company
- Nutreco N.V. (SHV Holdings N.V.)
- DSM-Firmenich AG
- Alltech, Inc.
- Kemin Industries, Inc.
- BASF SE
- Evonik Industries AG
- Elanco Animal Health Incorporated
- Novus International, Inc.
- Bluestar Adisseo Company
- Lallemand Inc.
- Zinpro Corporation
- Land O'Lakes, Inc.
- De Heus Animal Nutrition B.V. (Royal De Heus)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Commercial feedlot demand for better feed conversion and daily gain
- 4.2.2 Shift from antibiotic growth promoters to gut-health additives
- 4.2.3 Higher mycotoxin and forage variability in beef rations
- 4.2.4 Precision mineral and amino acid supplementation adoption
- 4.2.5 Carbon-insetting demand for methane-reducing additives
- 4.2.6 Byproduct-rich rations need more stabilizing additives
- 4.3 Market Restraints
- 4.3.1 Tight approval and residue-compliance burden
- 4.3.2 Volatile input costs for vitamins amino acids and fermentation products
- 4.3.3 Limited grazing-system fit for some methane inhibitors
- 4.3.4 Weak on-farm data capture slows return on investment validation
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Additive
- 5.1.1 Acidifiers
- 5.1.1.1 Lactic Acid
- 5.1.1.2 Propionic Acid
- 5.1.1.3 Fumaric Acid
- 5.1.1.4 Other Acidifiers
- 5.1.2 Antibiotics
- 5.1.2.1 Tetracyclines
- 5.1.2.2 Penicillins
- 5.1.2.3 Tylosin
- 5.1.2.4 Bacitracin
- 5.1.2.5 Other Antibiotics
- 5.1.3 Antioxidants
- 5.1.3.1 Butylated Hydroxyanisole (BHA)
- 5.1.3.2 Butylated Hydroxytoluene (BHT)
- 5.1.3.3 Ethoxyquin
- 5.1.3.4 Propyl Gallate
- 5.1.3.5 Tocopherols
- 5.1.3.6 Citric Acid
- 5.1.3.7 Other Antioxidants
- 5.1.4 Amino Acids
- 5.1.4.1 Lysine
- 5.1.4.2 Tryptophan
- 5.1.4.3 Methionine
- 5.1.4.4 Threonine
- 5.1.4.5 Other Amino Acid
- 5.1.5 Binders
- 5.1.5.1 Natural Binders
- 5.1.5.2 Synthetic Binders
- 5.1.6 Enzymes
- 5.1.6.1 Carbohydrases
- 5.1.6.2 Phytases
- 5.1.6.3 Other Enzymes
- 5.1.7 Flavors and Sweeteners
- 5.1.7.1 Flavors
- 5.1.7.2 Sweeteners
- 5.1.8 Minerals
- 5.1.8.1 Macrominerals
- 5.1.8.2 Microminerals
- 5.1.9 Mycotoxin Detoxifiers
- 5.1.9.1 Binders
- 5.1.9.2 Biotransformers
- 5.1.10 Phytogenics
- 5.1.10.1 Herbs & Spices
- 5.1.10.2 Essential Oil
- 5.1.10.3 Other Phytogenics
- 5.1.11 Pigments
- 5.1.11.1 Carotenoids
- 5.1.11.2 Curcumin & Spirulina
- 5.1.12 Prebiotics
- 5.1.12.1 Inulin
- 5.1.12.2 Fructo Oligosaccharides
- 5.1.12.3 Galacto Oligosaccharides
- 5.1.12.4 Xylo Oligosaccharides
- 5.1.12.5 Lactulose
- 5.1.12.6 Mannan Oligosaccharides
- 5.1.12.7 Other Prebiotics
- 5.1.13 Probiotics
- 5.1.13.1 Lactobacilli
- 5.1.13.2 Bifidobacteria
- 5.1.13.3 Streptococcus
- 5.1.13.4 Pediococcus
- 5.1.13.5 Enterococcus
- 5.1.13.6 Other Probiotics
- 5.1.14 Vitamins
- 5.1.14.1 Vitamin A
- 5.1.14.2 Vitamin B
- 5.1.14.3 Vitamin C
- 5.1.14.4 Vitamin E
- 5.1.14.5 Other Vitamins
- 5.1.15 Yeast
- 5.1.15.1 Live Yeast
- 5.1.15.2 Spent Yeast
- 5.1.15.3 Torula Dried Yeast
- 5.1.15.4 Selenium Yeast
- 5.1.15.5 Whey Yeast
- 5.1.15.6 Yeast Derivatives
- 5.1.1 Acidifiers
- 5.2 By Form
- 5.2.1 Dry
- 5.2.2 Liquid
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.1.4 Rest of North America
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Chile
- 5.3.2.4 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 France
- 5.3.3.3 United Kingdom
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Netherlands
- 5.3.3.7 Russia
- 5.3.3.8 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 India
- 5.3.4.3 Japan
- 5.3.4.4 Australia
- 5.3.4.5 New Zealand
- 5.3.4.6 South Korea
- 5.3.4.7 Indonesia
- 5.3.4.8 Thailand
- 5.3.4.9 Vietnam
- 5.3.4.10 Rest of Asia-Pacific
- 5.3.5 Middle East
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Turkey
- 5.3.5.3 Iran
- 5.3.5.4 United Arab Emirates
- 5.3.5.5 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Egypt
- 5.3.6.3 Kenya
- 5.3.6.4 Rest of Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Cargill, Incorporated
- 6.4.2 Archer Daniels Midland Company
- 6.4.3 Nutreco N.V. (SHV Holdings N.V.)
- 6.4.4 DSM-Firmenich AG
- 6.4.5 Alltech, Inc.
- 6.4.6 Kemin Industries, Inc.
- 6.4.7 BASF SE
- 6.4.8 Evonik Industries AG
- 6.4.9 Elanco Animal Health Incorporated
- 6.4.10 Novus International, Inc.
- 6.4.11 Bluestar Adisseo Company
- 6.4.12 Lallemand Inc.
- 6.4.13 Zinpro Corporation
- 6.4.14 Land O'Lakes, Inc.
- 6.4.15 De Heus Animal Nutrition B.V. (Royal De Heus)
7 Market Opportunities and Future Outlook

 2026-2030年全球牛飼料市場
 牛飼料:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)乳牛飼料添加劑:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)肉牛飼料:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)乳牛飼料:市場佔有率分析、產業趨勢和統計數據、成長預測(2026-2031)
 全球牛飼料及飼料添加劑市場規模、佔有率、趨勢及成長分析報告:2026-2034年
 牛飼料市場規模、佔有率及成長分析(按來源、通路、應用及地區分類)-2026-2033年產業預測
 乳牛飼料市場至2032年的預測:按產品類型、牛類型、產地、形態、最終用戶和地區的全球分析