


 |
市場調查報告書
商品編碼
2163612
歐洲建築檢測服務:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Europe Building Inspection Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
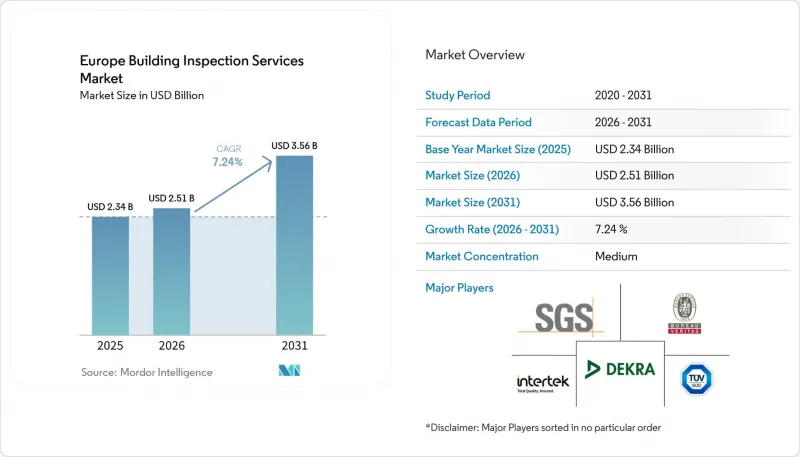
根據 Mordor Intelligence 預測,歐洲建築檢查服務市場規模將從 2025 年的 23.4 億美元和 2026 年的 25.1 億美元成長到 2031 年的 35.6 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 7.24%。
歐洲建築檢驗服務市場的趨勢與洞察
能源性能與建築維修義務
由於非住宅建築的最低能源效率標準,歐洲建築檢測服務市場需求激增。修訂後的指令規定,到2030年,16%的能源效率最低的非住宅建築必須進行維修,其餘26%的翻新目標年份為2033年。成員國必須在2026年12月前提交國家建築維修計劃,這增加了對基準評估和建築數據記錄的需求。大規模維修通常需要更新能源效率證書,這可能會為評估人員帶來重複性工作。義大利於2025年10月修訂了其能源效率計算方法,使暖氣、通風和暖通空調系統的檢查更加嚴格。
消防和建築安全監管
消防安全法規催生了獨立於節能改造之外的檢查需求。在英國,地方政府正面臨建築安全監管機構認證的檢查員短缺問題。 2024年,德國的技術專家對70,447個與安全相關的建築系統進行了檢查。結果顯示,27%的受檢系統有嚴重缺陷,44%有輕微缺陷。在法國,自2025年5月起,對於新建或維修項目,凡提交建築許可申請的,均需遵守電纜分類要求。這些要求增加了安裝前的檢查和認證工作。修訂後的《建築產品法規》進一步加強了對建築項目中產品級資訊和環境文件的重視。
合格的檢驗員和能源專家短缺
合格專業人員供不應求是限制歐洲建築檢驗服務市場的直接因素。歐盟的LIFE計畫在與6000多個機構磋商後,已在15個成員國更新了技能發展藍圖。蘇格蘭報告稱,到2025年,建築標準服務業將出現52名人員缺口。該國的勞動力報告預測,到2028年,缺口將達到120人,2035年將達到144人。目前,約46.5%的從業人員年齡超過50歲,增加了因退休而導致人才流失的風險。當合格專業人員短缺時,服務提供者可能面臨更長的排班時間和更高的員工維修成本。培訓計畫可以緩解這種壓力,但新專業人員需要時間才能勝任受監管的工作。
細分市場分析
2025年,特定構件檢測服務將佔總收入的41.8%,成為歐洲建築檢測服務市場中最大的服務類別。此類別包括對結構構件、暖氣、通風和空調(HVAC)系統、電氣裝置以及外觀的詳細評估。其規模反映了對單一系統和建築構件層面證據的需求。這些檢測有助於頒發證書、確定維護方案、設計維修以及實施整改措施。歐洲建築檢測服務業依賴能夠全面解讀建築狀況和法規要求的專業人員。
其他專業服務預計到2031年將以9.3%的複合年成長率成長。此類別包括基於無人機的外牆檢測、室內空氣品質檢測、聲學調查和數位化狀態監測。 Kiwa的「建築掃描」服務利用無人機、 3D模型和自動化分析來識別裂縫、侵蝕和混凝土劣化。法國對多用戶住宅能源性能證書的要求也推動了住宅評估領域的持續發展。當這些工具被用來補充而非取代專家判斷時,歐洲建築檢測服務市場將從中受益。
到2025年,內部服務收入佔比將達到54.9%,在歐洲建築檢測服務市場保持最大的市場佔有率。政府機構、公共產業和公共物業業者通常保留內部檢測能力,以應對責任問題和敏感資產資訊。內部團隊可以熟悉其建築組合和現場操作流程,並能與更廣泛的設施管理營運部門協調定期檢測工作。然而,即使採用這種模式,當專案需要高階技術能力時,仍然可能需要外部專家的協助。
預計到2031年,外包服務將以8.6%的複合年成長率成長。熱成像、無人機測量、碳排放評估以及複雜的暖通空調(HVAC)審計等服務可能超出典型內部團隊的能力範圍。 2025年9月,SOCOTEC簽署了一份為期六年的契約,將於2026年開始在格羅寧根和德倫特進行超過10萬次的檢查。許多大規模業主可能會將專業任務外包,同時保持內部協調。這種方法可以提高每項資產的檢查次數,而不是簡單地在供應商之間轉移任務。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 能源性能與建築維修義務
- 消防和建築安全監管
- 老舊建築存量
- 綠建築和碳排放報告要求
- 數位建築登記冊及維修護照
- 機構投資人跨國資產管理
- 市場限制因素
- 合格的檢驗員和能源專家短缺
- 每個國家的標準和核准程序都不同。
- 通用資料保護與建構資料管治風險
- 先進測試設備和軟體高成本
- 價值和供應鏈分析
- 監管情勢與政府應對措施
- 技術展望
- 經濟和市場展望
- 主要行業趨勢
- 波特五力分析
第5章:歐洲建築檢測服務市場、市場規模及成長預測
- 按服務
- 住宅檢查服務
- 特定元素檢測服務
- 商業建築檢查服務
- 其他專業服務
- 透過採購方式
- 內部服務
- 外包服務
- 透過使用
- 住宅
- 商業的
- 其他用途
- 最終用戶
- 房地產公司和仲介業者
- 房地產所有者和投資者
- 政府和地方當局
- 保險和金融機構
- 設施管理公司
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 俄羅斯
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 公司簡介
- SGS Group
- Bureau Veritas
- Intertek Group plc
- DEKRA SE
- TUV SUD AG
- TUV Rheinland AG
- DNV Group AS
- Applus+
- Eurofins Scientific SE
- UL Solutions Inc.
- NV5 Global
- Kiwa Group
- SOCOTEC
- RINA SpA
- Criterium Engineers
- Houspect
- Resicert
- InterNACHI
- DEKRA Drone Inspection Services
- Bureau Veritas SIA
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe building inspection services market size is projected to expand from USD 2.34 billion in 2025 and USD 2.51 billion in 2026 to USD 3.56 billion by 2031, registering a CAGR of 7.24% between 2026 and 2031.
Europe Building Inspection Services Market Trends and Insights
Energy Performance and Building Renovation Obligations
The Europe building inspection services market gains demand from minimum energy performance standards for non-residential buildings. The recast directive requires the worst-performing 16% of non-residential stock to be renovated by 2030. It also sets a 2033 target for the worst-performing 26% of that stock. Member states must submit national building renovation plans by December 2026, creating a need for baseline assessments and documented building data. A major renovation generally requires a renewed energy performance certificate, which can create repeat work for assessors. Italy updated its energy-performance calculation methods in October 2025, adding rigor to inspections of heating, ventilation, and air-conditioning systems.
Fire and Building Safety Oversight
Fire and safety rules create inspection needs that are separate from energy upgrades. In the United Kingdom, local authorities have faced shortages of inspectors certified by the Building Safety Regulator. German technical experts inspected 70,447 safety-relevant building systems in 2024. They identified major defects in 27% of inspected systems and minor defects in 44%. France introduced cable classification requirements for new or renovated buildings with planning applications submitted after May 2025. These requirements add inspection and certification work before installation. The revised Construction Products Regulation broadens attention to product-level information and environmental documentation within building projects.
Shortage of Qualified Inspectors and Energy Specialists
The supply of qualified personnel is a direct constraint on the Europe building inspection services market. The EU LIFE program updated skills roadmaps in 15 member states after consultations with more than 6,000 organizations. Scotland reported a 52-post staffing gap in building standards services during 2025. Its workforce report projected a gap of 120 staff by 2028 and 144 staff by 2035. Nearly 46.5% of its current workforce was aged over 50, raising the risk of retirement-related losses. Providers may face longer scheduling periods and higher retention costs when certified expertise is scarce. Training programs can reduce this pressure, but they require time before new specialists can conduct regulated work.
Other drivers and restraints analyzed in the detailed report include:
- Aging Building Stock
- Green Building and Carbon Reporting Requirements
- Divergent National Standards and Approval Procedures
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Specific element inspection services captured 41.8% of revenue in 2025, making them the largest service category in the Europe building inspection services market. The category covers detailed assessments of structural components, heating, ventilation, and air-conditioning systems, electrical installations, and facades. Its scale reflects the need for evidence at the level of individual systems and building elements. These examinations support certificates, maintenance decisions, renovation design, and corrective action. The Europe building inspection services industry depends on personnel who can interpret building conditions and regulatory requirements together.
Other specialized services are forecast to grow at a 9.3% CAGR through 2031. This category includes drone-based facade diagnostics, indoor air-quality testing, acoustic surveys, and digital condition monitoring. Kiwa's Building Scan service uses drones, three-dimensional models, and automated analysis to identify cracks, erosion, and concrete deterioration. France's collective energy performance certificate requirements also support continued work in residential assessments. The Europe building inspection services market benefits when these tools complement professional judgment rather than replace it.
In-house services held 54.9% of revenue in 2025, retaining the largest position within the Europe building inspection services market. Government bodies, utilities, and public real estate operators often keep inspection capability internally to manage liability and sensitive asset information. Internal teams can maintain familiarity with building portfolios and local operating procedures. They can coordinate routine inspections with wider facilities management duties. This model does not remove the need for external specialists when projects require advanced technical capabilities.
Outsourced services are forecast to advance at an 8.6% CAGR through 2031. Thermal imaging, drone surveys, carbon assessments, and complex heating, ventilation, and air-conditioning audits can exceed the capacity of general internal teams. SOCOTEC secured a 6-year contract in September 2025 to conduct more than 100,000 inspections in Groningen and Drenthe from 2026. Many large owners are likely to keep an internal coordination role while purchasing specialized work externally. This approach can increase the inspections completed for each asset instead of merely moving work between providers.
Complete Report Scope:
- By Service
- Home Inspection Services
- Specific Element Inspection Services
- Commercial Building Inspection Services
- Other Specialised Services
- By Sourcing Type
- In-House Services
- Outsourced Services
- By Application
- Residential
- Commercial
- Other Applications
- By End User
- Real-Estate Agencies and Brokers
- Property Owners and Investors
- Government and Municipalities
- Insurance and Financial Institutions
- Facility-Management Firms
- By Countries
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- SGS Group
- Bureau Veritas
- Intertek Group plc
- DEKRA SE
- TUV SUD AG
- TUV Rheinland AG
- DNV Group AS
- Applus+
- Eurofins Scientific SE
- UL Solutions Inc.
- NV5 Global
- Kiwa Group
- SOCOTEC
- RINA S.p.A.
- Criterium Engineers
- Houspect
- Resicert
- InterNACHI
- DEKRA Drone Inspection Services
- Bureau Veritas SIA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Energy-Performance and Building-Renovation Obligations
- 4.2.2 Fire and Building-Safety Oversight
- 4.2.3 Aging Building Stock
- 4.2.4 Green-Building and Carbon-Reporting Requirements
- 4.2.5 Digital Building Logbooks and Renovation Passports
- 4.2.6 Cross-Border Asset Management by Institutional Owners
- 4.3 Market Restraints
- 4.3.1 Shortage of Qualified Inspectors and Energy Specialists
- 4.3.2 Divergent National Standards and Approval Procedures
- 4.3.3 General Data-Protection and Building-Data Governance Risk
- 4.3.4 High Cost of Advanced Inspection Equipment and Software
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape and Government Initiatives
- 4.6 Technological Outlook
- 4.7 Economic and Market Scenario
- 4.8 Key Industry Trends
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
5 Europe Building Inspection Services Market, Market Size & Growth Forecasts (Value In USD)
- 5.1 By Service
- 5.1.1 Home Inspection Services
- 5.1.2 Specific Element Inspection Services
- 5.1.3 Commercial Building Inspection Services
- 5.1.4 Other Specialised Services
- 5.2 By Sourcing Type
- 5.2.1 In-House Services
- 5.2.2 Outsourced Services
- 5.3 By Application
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Other Applications
- 5.4 By End User
- 5.4.1 Real-Estate Agencies and Brokers
- 5.4.2 Property Owners and Investors
- 5.4.3 Government and Municipalities
- 5.4.4 Insurance and Financial Institutions
- 5.4.5 Facility-Management Firms
- 5.5 By Countries
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Russia
- 5.5.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 SGS Group
- 6.3.2 Bureau Veritas
- 6.3.3 Intertek Group plc
- 6.3.4 DEKRA SE
- 6.3.5 TUV SUD AG
- 6.3.6 TUV Rheinland AG
- 6.3.7 DNV Group AS
- 6.3.8 Applus+
- 6.3.9 Eurofins Scientific SE
- 6.3.10 UL Solutions Inc.
- 6.3.11 NV5 Global
- 6.3.12 Kiwa Group
- 6.3.13 SOCOTEC
- 6.3.14 RINA S.p.A.
- 6.3.15 Criterium Engineers
- 6.3.16 Houspect
- 6.3.17 Resicert
- 6.3.18 InterNACHI
- 6.3.19 DEKRA Drone Inspection Services
- 6.3.20 Bureau Veritas SIA
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


