


 |
市場調查報告書
商品編碼
2163611
北美建築檢驗服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)North America Building Inspection Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
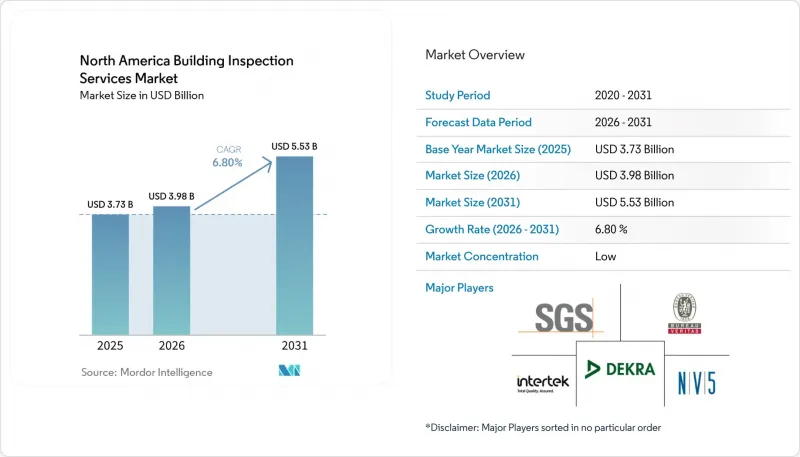
據 Mordor Intelligence 稱,2025 年北美建築檢查服務市值為 37.3 億美元,預計到 2031 年將從 2026 年的 39.8 億美元成長至 55.3 億美元,預測期(2026-2031 年)複合年成長率為 6.80%。
北美建築檢驗服務市場趨勢與洞察
房地產交易中的實質審查
在美國和加拿大,購屋前房屋檢查仍然是住宅交易流程的常規環節。根據美國房地產經紀人協會(NAR)的報告,到2025年,平均每位房地產仲介業者將完成九筆交易,這表明房屋檢查公司擁有穩定的客戶來源。在房價飆升的市場環境下,購屋者面臨更大的財務風險。這種風險的增加促使購屋者更加嚴格地審查房屋的維修需求、建築設施以及隱藏的缺陷。因此,即使由於購買力下降導致交易量減少,房屋檢查報告的重要性仍然存在。此外,商業金融機構在發放貸款前也會進行房產狀況評估,這支撐了住宅二手房交易週期之外的房屋檢查需求。
北美房屋檢驗服務市場的發展主要受檢驗報告在談判和貸款評估中的作用所驅動。買家在簽署合約前會利用檢驗結果來評估維修義務。貸款機構和保險公司則利用這些報告來評估房產的狀況和風險。這些用途創造了市場需求,而這種需求不僅與交易量相關,也與交易品質相關。房地產仲介業者的推薦也能降低現有住宅檢驗服務提供者的客戶獲取成本。這種關係使得服務品質、報告出具速度和本地聲譽成為關鍵的競爭因素。
州和地方政府更嚴格的建築規範。
新修訂的建築和能源標準加強了對設計文件的審查要求,並制定了新的檢查程序。紐約市已開始對2026年3月30日及之後提交的適用建築申請實施「2025年節能條例」。這項變更將增加適用項目所需的文件數量。建築物業主必須在整個規劃和施工過程中證明其符合相關規定。檢查員可以透過審查、現場考察和記錄核查來協助完成此過程。從一次性的專案合規期限轉向更穩定的業務機會,將為北美建築檢查服務市場帶來更穩定的工作。
建築性能要求可能導致持續數年的工作。業主必須追蹤建築物的能源性能、整改措施和檢驗需求。這使得檢查不再局限於與銷售或許可證相關的單一事件。對於一些大型物業而言,這成為合規計畫中至關重要的一部分。熟悉建築規範和數位證據管理系統的公司能夠很好地處理這項持續性工作。因此,這項工作對短期房地產市場趨勢的依賴性降低。
合格檢驗員短缺
合格檢查員供不應求仍然是限制服務能力的主要阻礙因素。威斯康辛州的學徒計畫公告引述美國勞工統計局的數據預測,2024年至2034年間,建築檢查員的年度職缺將達到14,800個。退休人員數量的增加加劇了對訓練有素的接班人的需求。許多地區要求工作人員既了解建築規範要求,也了解當地的核准流程。核准延誤會導致許可證發放、檢查和住宅交付的延遲。擁有充足檢查員儲備的服務提供者有機會在市政部門無法滿足需求時訂單工作。
威斯康辛州於2026年秋季推出了首個註冊商業建築檢查員學徒計畫。該計劃結合了288小時的培訓和超過2000小時的實務經驗。雖然這類計畫從長遠來看可以擴大勞動力隊伍,但它們並不能解決高需求領域目前的勞動力短缺問題。培訓要求和執照頒發流程可能會阻礙其他建築業的工人進入該行業。北美建築檢查服務市場仍供不應求,合格人員的需求成長速度超過了供應速度。
細分市場分析
2025年,住宅檢驗服務佔北美建築檢驗服務市場的45.6%。這一領域與住宅購買、貸款機構要求以及房地產仲介業者的推薦密切相關。買家利用住宅檢驗來識別可見的缺陷和維護需求。檢驗報告會影響銷售合約最終簽訂前的維修談判。因此,速度、清晰度和本地知識是關鍵的服務特徵。標準住宅檢驗仍然是許多企業的主要切入點。 「特定項目檢驗服務」增加了與氡氣、黴菌、害蟲、結構問題和其他隱患相關的檢驗。 「商業建築檢驗服務」則協助企業進行收購、金融機構審查及設施管理。將這些服務結合起來,企業可以企業發展到單一物業類型之外。
其他專業服務預計到2031年將以8.9%的複合年成長率成長。該領域包括能源審計、熱成像以及基於無人機的屋頂和外牆檢測。 EagleView於2026年4月推出了其房地產智慧平台Horizon。據該公司稱,該平台利用超過35億張空拍照片的資料庫,覆蓋了96%的美國人口。這些工具可能使一些業務從一次性專案轉向投資組合監控。資產管理公司和保險公司可能會優先考慮在大規模投資組合中獲取更一致的房地產數據。這將支撐北美建築檢測服務市場對專業服務的需求。然而,服務提供者仍需要經驗豐富的檢測人員來解讀複雜的檢測結果並處理特定地點的具體情況。
截至2025年,「內部服務」佔北美建築檢驗服務市場的57.8%。大規模市政機構和機構投資者利用內部團隊來管理工作品質和進度。全國性公司也可能聘請內部專家來負責複雜的設施。內部團隊直接了解公司的資產和營運標準,並且可以與資本規劃和維護部門密切合作。這種模式對於擁有大量且穩定的檢驗工作量的機構來說最為實用。然而,如果招募需求激增,管理起來就會變得困難。檢驗員短缺會增加繼續由內部團隊負責所有營運的成本。由於許多大型資產所有者優先考慮直接管理,因此這種模式在北美建築檢驗服務市場中仍然被廣泛採用。
預計到2031年,外包服務市場將以8.4%的複合年成長率成長。市政當局在無法僱用或確保足夠數量的檢查員時,會利用第三方供應商。 SAFEbuilt的業務遍及41個州和哥倫比亞特區,這顯示共享市政服務模式已被廣泛採用。外部供應商還可以提供結構、能源審計和無人機操作等領域的專業知識。單一市政當局很難獨立建立這些能力。認證和正式的品管程序可以增強人們對外包服務的信心。因此,這種採購方式的轉變不僅滿足了人員需求。它使客戶能夠利用專業能力和通用的報告系統。獲得認證的公司可以利用這些優勢來競爭大規模的合約。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 房地產交易中的實質審查
- 州和地方層級制定更嚴格的建築規範。
- 破舊的住宅和商業建築存量
- 維修、整修和氣候變遷適應力提升項目
- 訂閱投資組合等級房地產資訊服務
- 數位化可審計的檢查證據
- 市場限制因素
- 合格檢驗員短缺
- 各州許可證制度和法規的複雜性
- 利用數位和人工智慧技術進行研究所帶來的專業責任風險。
- 本地企業與加盟商之間的價格競爭
- 價值和供應鏈分析
- 監管情勢與政府應對措施
- 技術展望
- 經濟和市場展望
- 主要行業趨勢
- 波特五力分析
第5章 市場規模與成長預測
- 按服務
- 住宅檢查服務
- 特定部件檢測服務
- 商業建築檢查服務
- 其他專業服務
- 透過採購方式
- 內部服務
- 外包服務
- 透過使用
- 住宅
- 商業的
- 其他用途
- 最終用戶
- 房地產公司和仲介業者
- 房地產所有者和投資者
- 政府和地方當局
- 保險和金融機構
- 設施管理公司
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 公司簡介
- SGS Group
- Bureau Veritas
- Intertek Group plc
- DEKRA SE
- NV5 Global
- AmeriSpec Inspection Services
- HouseMaster
- National Property Inspections
- Pillar To Post
- WIN Home Inspection
- SAFEbuilt
- Quality Built
- Criterium Engineers
- Houspect
- Resicert
- HomeTeam Inspection Service
- InterNACHI
- DEKRA Drone Inspection Services
- AeroSpect NY
- Drone Fly Inspect
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America building inspection services market size was valued at USD 3.73 billion in 2025 and is estimated to grow from USD 3.98 billion in 2026 to reach USD 5.53 billion by 2031, at a CAGR of 6.80% during the forecast period (2026-2031).
North America Building Inspection Services Market Trends and Insights
Real-Estate Transaction Due Diligence
Pre-purchase inspections remain part of the normal residential transaction process in the United States and Canada. The National Association of Realtors reported that the typical agent completed 9 transaction sides during 2025, which supports a regular referral base for inspection providers. Buyers face greater financial exposure when property prices are high. That exposure increases scrutiny of repair needs, building systems, and concealed defects. Inspection reports can therefore remain relevant even when affordability reduces transaction volumes. Commercial lenders also use property condition assessments before financing, which supports demand outside the housing resale cycle.
The North America building inspection services market is supported by the role of inspection reports in negotiations and underwriting. Buyers use findings to evaluate repair obligations before closing. Lenders and insurers use reports to assess property condition and risk. These uses create demand that is tied to the quality of a transaction, not only its number. Agent referrals also reduce customer-acquisition costs for established residential providers. This relationship makes service quality, report speed, and local reputation important competitive factors.
Stricter State and Municipal Building Codes
New building and energy code editions increase plan-review requirements and create new inspection steps. New York City began enforcing its 2025 Energy Conservation Code for relevant building applications filed from March 30, 2026. The change expands the documentation needed for affected projects. Building owners must demonstrate compliance during planning and construction. Inspectors can support this process through reviews, site visits, and records. The North America building inspection services market gains steadier work when compliance deadlines replace one-time project decisions.
Building performance requirements can also create repeat work over several years. Owners must track building energy performance, corrective actions, and verification needs. This changes inspection from an event linked only to a sale or permit. It becomes part of a compliance schedule for some large properties. Firms with code knowledge and digital evidence systems are better placed to handle repeat assignments. The resulting work is less dependent on short-term real estate sentiment.
Shortage of Qualified Inspectors
The supply of qualified inspectors remains a central limit on service capacity. The Bureau of Labor Statistics projects 14,800 annual openings for construction and building inspectors from 2024 to 2034, as cited by Wisconsin's apprenticeship announcement. Retirements increase the need for trained replacements. Many jurisdictions need staff who understand both code requirements and local approval processes. Delays can slow permits, inspections, and housing delivery. Providers with deeper inspector pools can gain assignments when municipal departments cannot meet demand.
Wisconsin introduced its first Commercial Building Inspector Registered Apprenticeship in the fall of 2026. The program combines 288 hours of instruction with more than 2,000 hours of work experience. Such programs can expand the workforce over time. They do not remove immediate shortages in high-demand locations. Training requirements and licensing pathways can deter workers from entering from other construction roles. The North America building inspection services market remains constrained when demand rises faster than qualified staff.
Other drivers and restraints analyzed in the detailed report include:
- Aging Residential and Commercial Building Stock
- Renovation, Retrofit, and Climate-Resiliency Projects
- State-by-State Licensing and Code Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Home Inspection Services held 45.6% of the North America building inspection services market size in 2025. The segment is linked to residential purchases, lender expectations, and agent referrals. Buyers use home inspections to identify visible defects and maintenance needs. Reports can influence repair negotiations before a sale closes. This makes speed, clarity, and local knowledge important service attributes. Standard home inspections remain a high-volume entry point for many providers. Specific Element Inspection Services add work related to radon, mold, pests, structures, and other hidden risks. Commercial Building Inspection Services support acquisitions, lender reviews, and facility management. Together, these services broaden provider exposure beyond a single property type.
Other Specialized Services is forecast to grow at an 8.9% CAGR through 2031. This area includes energy audits, thermal imaging, and drone-based reviews of roofs and exterior walls. EagleView launched its Horizon property intelligence platform in April 2026. The company said the platform uses a library of more than 3.5 billion aerial images. It also stated that coverage reaches 96% of the U.S. population. These tools can shift some work from single projects toward portfolio monitoring. Asset managers and insurers may value more consistent property data across large portfolios. This supports specialized service demand within the North America building inspection services market. Providers still need experienced inspectors to interpret complex findings and address site-specific conditions.
In-House Services held 57.8% of the North America building inspection services market size in 2025. Large municipalities and institutional owners use internal teams to control work quality and scheduling. National companies may also retain in-house professionals for complex facilities. Internal teams have direct familiarity with their assets and operating standards. They can coordinate closely with capital planning and maintenance functions. This model is most practical for organizations with a large, stable inspection workload. It can become difficult when hiring needs rise quickly. Inspector shortages increase the cost of maintaining full internal coverage. The North America building inspection services market continues to include this model because many large asset owners value direct control.
Outsourced Services is forecast to grow at an 8.4% CAGR through 2031. Municipalities use third-party providers when they cannot recruit or retain enough inspectors. SAFEbuilt operates across 41 states and the District of Columbia, demonstrating the reach of a pooled municipal services model. External providers can also supply specialists in structures, energy audits, and drone operations. This access can be difficult for each municipality to build separately. Accreditation and formal quality procedures can strengthen confidence in outsourced work. The sourcing shift is therefore more than a staffing response. It gives clients access to specialized capabilities and common reporting systems. Credentialed firms can use these strengths to compete for larger contracts.
Complete Report Scope:
- By Service
- Home Inspection Services
- Specific Element Inspection Services
- Commercial Building Inspection Services
- Other Specialised Services
- By Sourcing Type
- In-House Services
- Outsourced Services
- By Application
- Residential
- Commercial
- Other Applications
- By End User
- Real-Estate Agencies and Brokers
- Property Owners and Investors
- Government and Municipalities
- Insurance and Financial Institutions
- Facility-Management Firms
- By Countries
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- SGS Group
- Bureau Veritas
- Intertek Group plc
- DEKRA SE
- NV5 Global
- AmeriSpec Inspection Services
- HouseMaster
- National Property Inspections
- Pillar To Post
- WIN Home Inspection
- SAFEbuilt
- Quality Built
- Criterium Engineers
- Houspect
- Resicert
- HomeTeam Inspection Service
- InterNACHI
- DEKRA Drone Inspection Services
- AeroSpect NY
- Drone Fly Inspect
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Real-Estate Transaction Due Diligence
- 4.2.2 Stricter State and Municipal Building Codes
- 4.2.3 Aging Residential and Commercial Building Stock
- 4.2.4 Renovation, Retrofit, and Climate-Resiliency Projects
- 4.2.5 Portfolio-Level Property Intelligence Subscriptions
- 4.2.6 Digitally Auditable Inspection Evidence
- 4.3 Market Restraints
- 4.3.1 Shortage of Qualified Inspectors
- 4.3.2 State-by-State Licensing and Code Complexity
- 4.3.3 Professional-Liability Exposure From Digital and AI-Assisted Findings
- 4.3.4 Price Competition From Local and Franchise Operators
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape and Government Initiatives
- 4.6 Technological Outlook
- 4.7 Economic and Market Scenario
- 4.8 Key Industry Trends
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Service
- 5.1.1 Home Inspection Services
- 5.1.2 Specific Element Inspection Services
- 5.1.3 Commercial Building Inspection Services
- 5.1.4 Other Specialised Services
- 5.2 By Sourcing Type
- 5.2.1 In-House Services
- 5.2.2 Outsourced Services
- 5.3 By Application
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Other Applications
- 5.4 By End User
- 5.4.1 Real-Estate Agencies and Brokers
- 5.4.2 Property Owners and Investors
- 5.4.3 Government and Municipalities
- 5.4.4 Insurance and Financial Institutions
- 5.4.5 Facility-Management Firms
- 5.5 By Countries
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 SGS Group
- 6.3.2 Bureau Veritas
- 6.3.3 Intertek Group plc
- 6.3.4 DEKRA SE
- 6.3.5 NV5 Global
- 6.3.6 AmeriSpec Inspection Services
- 6.3.7 HouseMaster
- 6.3.8 National Property Inspections
- 6.3.9 Pillar To Post
- 6.3.10 WIN Home Inspection
- 6.3.11 SAFEbuilt
- 6.3.12 Quality Built
- 6.3.13 Criterium Engineers
- 6.3.14 Houspect
- 6.3.15 Resicert
- 6.3.16 HomeTeam Inspection Service
- 6.3.17 InterNACHI
- 6.3.18 DEKRA Drone Inspection Services
- 6.3.19 AeroSpect NY
- 6.3.20 Drone Fly Inspect
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


