


 |
市場調查報告書
商品編碼
2154885
南美洲訂閱和計費管理:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)South America Subscription and Billing Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
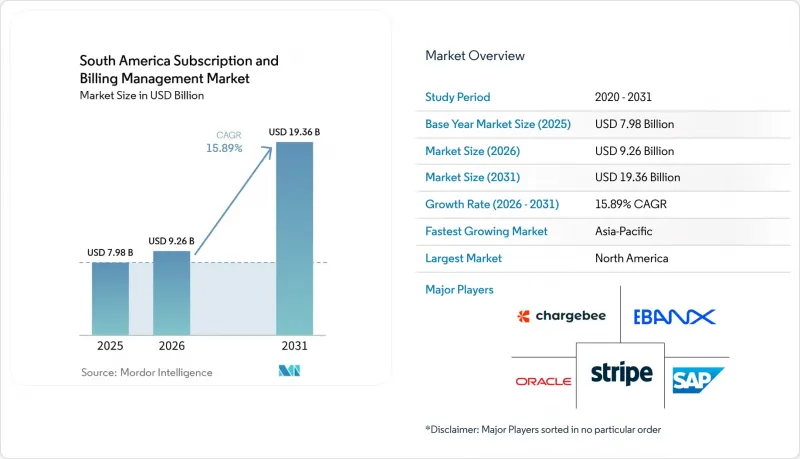
據 Mordor Intelligence 稱,2025 年南美訂閱和收費管理市場價值為 79.8 億美元,預計將從 2026 年的 92.6 億美元成長到 2031 年的 193.6 億美元。
預計 2026 年至 2031 年的預測期內複合年成長率將達到 15.89%。
南美訂閱和收費管理市場的趨勢和洞察。
訂閱式經營模式的擴展
在巴西,2026年第一季(不包括Pix Automatico交易)的循環信用卡消費額較上年同期顯著成長。根據Vindi發布的2026年消費者調查,僅訂閱數位服務的消費者比例高於2025年,預計未來五年訂閱支出將增加的消費者比例也創下該調查開展以來的最高紀錄。與成熟的數位企業類似,醫療保健、教育、物流和硬體服務等行業正在採用循環收費模式。這些模式需要靈活的套餐配置、按比例計費以及客戶生命週期的自動化管理。隨著服務提供者從基礎計費處理轉向能夠滿足這些營運需求的系統,南美訂閱和計費管理市場將從中受益。
數位支付和即時支付基礎設施的成長
巴西的Pix Automatico和哥倫比亞的Bre-B正在為循環收費業務重構支付基礎設施。根據哥倫比亞共和國銀行(Banco de la Republica)的一份報告顯示,自Bre-B推出以來,其用戶交易活躍度高,支付金鑰也得到了廣泛應用。 Worldwide也報告了Bre-B的快速成長,預計到2026年3月,其平台交易量將超過5億筆。每個支付網路對授權、試驗和收款都有其獨特的要求。能夠透過單一介面管理這些要求的服務提供者可以降低在多個國家/地區營運的商家的營運複雜性。因此,支付編配已成為拉丁美洲訂閱和計費管理市場的核心產品需求。
跨境支付詐騙和扣回爭議帳款風險
根據萬事達卡的報告,巴西的扣回爭議帳款率高於美國和法國。報告也指出,由於第三方詐欺行為,巴西商家的扣回爭議帳款顯著上升。萬事達卡和Datos Insights預測,扣回爭議帳款將在整個南美洲持續成長。隨著支付失敗和糾紛的發生,試驗、令牌化和證據管理成為收費管理中不可或缺的功能。這些挑戰可能會增加在南美洲訂閱和收費管理市場實施這些功能所需的工作量和營運成本。
細分市場分析
2025年,該軟體在南美洲訂閱和收費管理市場佔據了78.14%的市場。這款整合軟體整合了信用和收款管理、應收帳款管理、報價和定價管理、訂閱訂單管理以及爭議管理等功能。這些功能提高了配置柔軟性,但也使得部署後難以切換平台。 2026年6月,Zuora發布了“AI貨幣化套件”,在報價到付款的工作流程中加入了AI定價模擬器和計量型授權管理功能。 2026年2月,SAP發布了“訂閱訂單管理2025 FPS01”,擴展了對循環服務合約的支援。
預計到2031年,服務市場將以15.92%的複合年成長率成長。隨著企業將Pix Automatico、Bre-B、Nequi和Yape等系統與其稅務和財務系統整合,實施支援和管理服務的重要性日益凸顯。巴西資料傳輸標準合約條款已於2025年8月全面生效,新增了國際資料傳輸的配置要求。中型企業客戶通常需要持續的收款和對帳支援。由本地實施團隊負責這項工作可以縮短從實施到首個計費週期的時間。因此,在南美訂閱和計費管理行業,除了平台銷售之外,對服務的需求也在不斷成長。
到了2025年,雲端技術在南美訂閱和計費管理市場佔78.22%的佔有率。預計到2031年,該市場將以16.11%的複合年成長率成長,這反映了市場對持續產品更新的需求。雲端系統允許新增付款方式、修改收款規則以及應用程式合規更新,而無需客戶自行進行升級專案。來自TOTVS和H2R Insights的巴西雲採用數據顯示,客戶對SaaS產品的親和性已經很高。 Claro發布的2025年雲端投資數據也顯示,電信業者正在支援SaaS功能向小規模客戶推廣。
對於受監管的金融機構和有數據主權要求的公共產業公司而言,本地部署系統仍然發揮著至關重要的作用。這些產業的新合約擴大採用混合模式,將計費功能遷移到託管平台,同時保留部分本地處理。這種模式使公司能夠在不一次性替換所有核心系統的情況下實現支付和計劃管理的現代化。巴西的資料保護要求使得資料儲存位置和合約條款對實施至關重要。因此,南美訂閱和計費管理市場正從簡單的「雲端或本地部署」選擇轉向雲端驅動架構。混合營運模式也有助於長期使用ERP環境的組織實現平穩過渡。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 訂閱式經營模式的擴展
- 數位支付的成長和即時支付基礎設施的擴展
- 對自動化客戶維繫和收入恢復的需求
- SaaS、媒體、零售和通訊業的雲端採用情況
- Pix Automatico 和銀行間定期付款
- 為銀行服務取得受限的用戶提供本地化支付編配。
- 市場限制因素
- 跨境支付的詐欺和扣回爭議帳款風險
- 整合傳統ERP和CRM系統的複雜性。
- 貨幣波動性和動態價格指數
- 稅收體系碎片化、資料居住要求和資本管制
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 軟體
- 信貸和債務管理
- 應收帳款管理
- 報價和定價管理
- 訂閱訂單管理
- 衝突管理
- 其他軟體功能
- 服務
- 專業服務
- 託管服務
- 軟體
- 部署模式
- 現場
- 雲
- 按公司規模
- 大公司
- 中小企業
- 按最終用戶行業分類
- 零售與電子商務
- BFSI
- 資訊科技/通訊
- 媒體與娛樂
- 公共部門和公共產業
- 其他終端用戶產業
- 按地區
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- EBANX Ltda.
- DLocal Limited
- Zuora, Inc.
- Stripe, Inc.
- Chargebee, Inc.
- Oracle Corporation
- SAP SE
- Salesforce, Inc.
- PayPal Holdings, Inc.
- Fiserv, Inc.
- Block, Inc.
- Vindi Tecnologia Ltda.
- Kushki SA
- Recurly, Inc.
- Paddle.com Market Ltd.
- Vindicia, Inc.
- BillingPlatform, Inc.
- GoTransverse, Inc.
- Zoho Corporation Pvt. Ltd.
- CloudBlue LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the South America subscription and billing management market size was valued at USD 7.98 billion in 2025 and estimated to expand from USD 9.26 billion in 2026 to reach USD 19.36 billion by 2031, at a CAGR of 15.89% during the forecast period 2026-2031.
South America Subscription and Billing Management Market Trends and Insights
Expansion of Subscription-Based Business Models
Brazilian recurring card spending increased significantly in the first quarter of 2026 compared with the previous year, excluding Pix Automatico transactions. Vindi's 2026 consumer study found a higher share of consumers held only digital subscriptions than in 2025, while the share expecting higher subscription spending over the next 5 years was the highest since the study began. Health services, education, logistics, and hardware services are adopting recurring pricing alongside more established digital businesses. These models require flexible plans, proration, and automated customer lifecycle controls. The South America subscription and billing management market benefits when providers move from basic invoicing to systems that can manage these operating requirements.
Growth of Digital Payments and Real-Time Payment Rails
Pix Automatico in Brazil and Bre-B in Colombia are reshaping the payment infrastructure for recurring commerce. Banco de la Republica reported strong transaction activity and widespread adoption of payment keys among Bre-B users following its launch. Worldwide also reported rapid early adoption of Bre-B, with the platform passing 500 million transactions in March 2026. Each rail has its own consent, retry, and payment-recovery requirements. Providers that manage these requirements through one interface can reduce operating complexity for merchants active in several countries. This makes payment orchestration a central product requirement in the South America subscription and billing management market.
Cross-Border Payment Fraud and Chargeback Exposure
Mastercard reported that Brazil recorded a higher chargeback rate than the United States and France. The report also indicated that Brazilian merchants experienced a notable increase in third-party fraud chargebacks. Mastercard and Datos Insights project that chargeback volumes will continue to rise across South America. Payment failures and disputes make retries, tokenization, and evidence management essential billing functions. These pressures can increase implementation effort and operating costs in the South America subscription and billing management market.
Other drivers and restraints analyzed in the detailed report include:
- Cloud Adoption Across SaaS, Media, Retail, and Telecom
- Pix Automatico and Account-to-Account Recurring Payments
- Currency Volatility and Dynamic Price Indexation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 78.14% of the South America subscription and billing management market share in 2025. Integrated software combines credit and collections management, receivables, quote and pricing management, subscription order management, and dispute management. These capabilities create configuration depth and make platform replacement more difficult after implementation. Zuora launched its AI Monetization Suite in June 2026, adding an AI Pricing Simulator and metered entitlements to its quote-to-cash workflow. SAP expanded recurring service contract support in its Subscription Order Management 2025 FPS01 release in February 2026.
Services are projected to expand at a CAGR of 15.92% through 2031. Implementation and managed services are becoming more important as companies connect Pix Automatico, Bre-B, Nequi, and Yape with tax and finance systems. Brazil's data-transfer standard contractual clauses took full effect in August 2025, adding configuration considerations for international data transfers. Mid-market customers often need ongoing support for payment recovery and reconciliation. Local implementation teams can shorten the time between deployment and the first billing cycle. The South America subscription and billing management industry, therefore, has a rising services need alongside platform sales.
Cloud accounted for 78.22% of the South America subscription and billing management market share in 2025. Its projected CAGR of 16.11% through 2031 reflects demand for continuous product updates. Cloud systems can add payment methods, revise recovery rules, and apply compliance updates without a customer-led upgrade project. The Brazilian cloud adoption data from TOTVS and H2R Insights indicates that customer familiarity with SaaS delivery is already high. Claro's 2025 cloud investment also shows that telecommunications providers are helping distribute SaaS capabilities to smaller customers.
On-premise systems remain relevant to regulated financial institutions and utilities with data sovereignty requirements. New agreements in these sectors increasingly use hybrid models that keep some processing locally while moving billing functions to hosted platforms. This model allows firms to modernize payment and plan management without replacing every core system at once. Brazil's data protection requirements make data location and contract terms important during deployment. The South America subscription and billing management market is consequently moving toward cloud-led architectures rather than a simple cloud or on-premise choice. Hybrid operating models can also ease migration for organizations with long-standing ERP environments.
Complete Report Scope:
- By Component
- Software
- Credit and Collection Management
- Receivables Management
- Quote and Pricing Management
- Subscription Order Management
- Dispute Management
- Other Software Functions
- Services
- Professional Services
- Managed Services
- Software
- By Deployment Mode
- On-Premise
- Cloud
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-User Industry
- Retail and E-Commerce
- BFSI
- IT and Telecom
- Media and Entertainment
- Public Sector and Utilities
- Other End-User Industries
- By Geography
- Brazil
- Argentina
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- EBANX Ltda.
- DLocal Limited
- Zuora, Inc.
- Stripe, Inc.
- Chargebee, Inc.
- Oracle Corporation
- SAP SE
- Salesforce, Inc.
- PayPal Holdings, Inc.
- Fiserv, Inc.
- Block, Inc.
- Vindi Tecnologia Ltda.
- Kushki S.A.
- Recurly, Inc.
- Paddle.com Market Ltd.
- Vindicia, Inc.
- BillingPlatform, Inc.
- GoTransverse, Inc.
- Zoho Corporation Pvt. Ltd.
- CloudBlue LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Subscription-Based Business Models
- 4.2.2 Growth of Digital Payments and Real-Time Payment Rails
- 4.2.3 Demand for Automated Churn Reduction and Revenue Recovery
- 4.2.4 Cloud Adoption Across SaaS, Media, Retail, and Telecom
- 4.2.5 Pix Automatico and Account-to-Account Recurring Payments
- 4.2.6 Localized Payment Orchestration for Underbanked Subscribers
- 4.3 Market Restraints
- 4.3.1 Cross-Border Payment Fraud and Chargeback Exposure
- 4.3.2 Legacy ERP and CRM Integration Complexity
- 4.3.3 Currency Volatility and Dynamic Price Indexation
- 4.3.4 Tax, Data-Residency, and Capital-Control Fragmentation
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.1.1 Credit and Collection Management
- 5.1.1.2 Receivables Management
- 5.1.1.3 Quote and Pricing Management
- 5.1.1.4 Subscription Order Management
- 5.1.1.5 Dispute Management
- 5.1.1.6 Other Software Functions
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Software
- 5.2 By Deployment Mode
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By Enterprise Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By End-User Industry
- 5.4.1 Retail and E-Commerce
- 5.4.2 BFSI
- 5.4.3 IT and Telecom
- 5.4.4 Media and Entertainment
- 5.4.5 Public Sector and Utilities
- 5.4.6 Other End-User Industries
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 EBANX Ltda.
- 6.4.2 DLocal Limited
- 6.4.3 Zuora, Inc.
- 6.4.4 Stripe, Inc.
- 6.4.5 Chargebee, Inc.
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Salesforce, Inc.
- 6.4.9 PayPal Holdings, Inc.
- 6.4.10 Fiserv, Inc.
- 6.4.11 Block, Inc.
- 6.4.12 Vindi Tecnologia Ltda.
- 6.4.13 Kushki S.A.
- 6.4.14 Recurly, Inc.
- 6.4.15 Paddle.com Market Ltd.
- 6.4.16 Vindicia, Inc.
- 6.4.17 BillingPlatform, Inc.
- 6.4.18 GoTransverse, Inc.
- 6.4.19 Zoho Corporation Pvt. Ltd.
- 6.4.20 CloudBlue LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 物聯網計費和貨幣化軟體:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)網路API貨幣化:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)訂閱收費管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 個人財務管理及訂閱管理應用市場預測至2034年-全球平台類型、功能、獲利模式、產品類型、應用、使用者類型及區域分析
 訂閱收費管理市場機會、成長要素、產業趨勢分析及 2026-2035 年預測。
 2026年全球訂閱與計費管理市場報告2026年全球訂閱計費管理市場報告
 全球訂閱計費管理市場:依軟體、服務、部署類型、企業規模、最終用途和地區劃分 - 市場規模、行業趨勢、機會分析和預測(2026-2035年)全球訂閱收費管理市場:預測至 2032 年-按組件、部署方式、公司規模、技術、最終用戶和地區進行分析拉丁美洲訂閱和收費管理 -市場佔有率分析、行業趨勢和統計、成長預測(2025-2030)