


 |
市場調查報告書
商品編碼
2125344
中東和非洲容積式幫浦:市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)MEA Positive Displacement Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
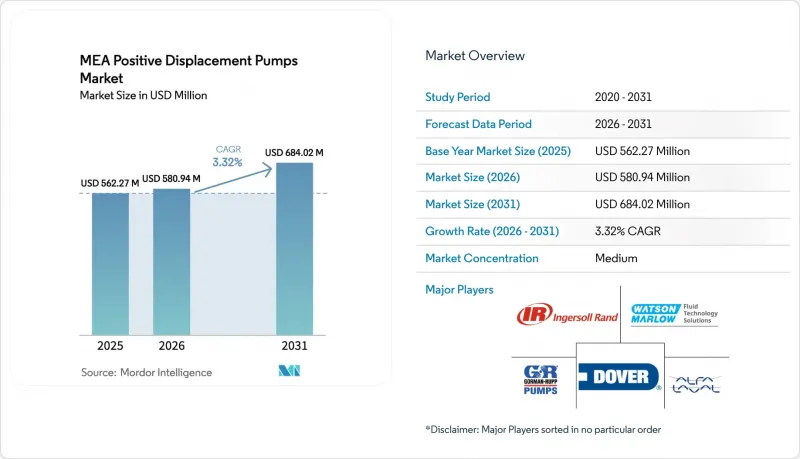
根據Mordor Intelligence預測,2026年中東和非洲容積式泵浦市場規模預計將達到5.8094億美元,高於2025年的5.6227億美元。預計到2031年,該市場規模將達到6.8402億美元,從2026年到2031年,該市場預計將以3.32%的複合年成長率成長。
本報告依容積式泵浦原理(旋轉泵浦、往復泵)、終端用戶產業(石油天然氣、化學及石化、其他)、材質(鑄鐵、其他)、潤滑方式(潤滑式、非潤滑式)、流量(小於10立方公尺/小時、10-50立方公尺/小時、50-200立方公尺/小時、大於200立方公尺/小時、大於200立方公尺/小時、大於200立方公尺/小時、大於200立方公尺/小時、大於200立方公尺/小時、大於200立方公尺/小時)。市場預測以美元計價。
中東及非洲容積式幫浦市場趨勢及洞察
上游工程油氣專案管道已恢復運作。
2024年透過最終投資決定(FID)的30個上游項目釋放了1,250億美元的投資潛力。各國國家石油公司都渴望利用每桶約47美元的損益平衡點獲利。光是阿布達比國家石油公司天然氣公司(ADNOC Gas)就已撥款50億美元用於擴建三座天然氣處理廠,每座廠都需要高壓柱塞泵和隔膜泵。沙烏地阿美承諾在2030年將天然氣產量提高60%,將進一步擴大目標裝置量。這些發展導致對能夠處理酸性氣體和多相流的堅固耐用的旋轉螺旋泵和往復泵的需求持續激增,推動了中東和非洲容積式泵市場的短期訂單。
工業用水的快速強制再利用
由於嚴重缺水,沙烏地阿拉伯設定了100%污水回用的目標,遠超過目前18%的基準值。國家水務局正投資230億美元用於污水處理設施的維修。工業設施現在必須安裝化學藥劑注入系統和污泥處理系統,即使在腐蝕性環境下也能可靠地運作。沙烏地阿美公司進行的陶瓷薄膜示範試驗已達到85-90%的回收率,每年可減少2,200萬加侖淡水的使用。這些舉措推動了對雙相不銹鋼隔膜泵、蠕動泵和單軸螺旋泵浦的需求,為中東和非洲的容積式泵市場提供了持續的中期發展動力。
與離心式幫浦相比,資本支出和總擁有成本更高。
採購團隊通常根據初始成本評估設備,而就此指標而言,離心式幫浦在高流量、低黏度應用中可節省 20-30% 的成本。在非洲經濟體中,物價與大宗商品價格掛鉤,融資有限的企業可能會選擇單級離心泵,即使其運作條件更適合容積式泵。供應商正透過節能升級來應對這項需求。韋爾的 WARMAN AH 系列採用了“磨損減少技術”,可將能耗降低高達 5%,從而縮小生命週期成本差距。
細分市場分析
預計到2025年,旋轉泵的銷售額將佔總銷售額的28.15%,顯示其在上游油氣產業以及瀝青混合過程中高黏度流體輸送領域發揮重要作用。隔膜泵和活塞往復泵在處理高腐蝕性化學品時能夠實現無洩漏運行,也正在開闢一個可觀的細分市場。隨著製藥企業為確保無菌性而轉向使用一次性軟管,預計中東和非洲蠕動式容積泵的市場規模將以3.67%的複合年成長率成長。
根據技術藍圖,齒輪泵在中壓(10 bar以下)應用中保持成本優勢,而單軸螺旋泵浦憑藉其耐用的定子材料,在漿料處理應用中正日益受到青睞。 Vogelsang 的 EP 系列(一體成型泵殼,額定壓力 260 psi/392°F)展示了一種面向更高壓力範圍的創新方法。此外,製造商正在整合旋轉式和往復式設計,以最佳化不同流量需求下的效率,這一趨勢有望拓寬解決方案選擇,並保持中東和非洲容積式泵浦市場的價格競爭力。
預計到2025年,石油和天然氣行業將佔銷售額的30.85%,這主要得益於市場對能夠處理多相輸送、化學注入和防噴器(BOP)迴路中氣體夾帶問題的堅固耐用的柱塞式和雙螺桿式裝置的需求。緊隨其後的是水和污水處理產業,預計佔26.52%,這主要得益於海水淡化和污水管網維修。化工和石化產業正受惠於區域整合策略。儘管製藥市場規模較小,但隨著阿拉伯聯合大公國、埃及和沙烏地阿拉伯等國新建工廠中無菌生產線的日益普及,預計到2031年,製藥市場將以3.74%的複合年成長率成長。
海灣國家推行的食品安全計畫優先發展本地生產,這提振了食品飲料製造商的需求。在採礦和金屬行業,用於脫水和精礦輸送的耐磨泵需求佔9.65%的市場佔有率。終端市場的多元化透過分散風險和降低收入波動,進一步增強了中東和非洲地區容積式泵浦的強勁市場前景。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 迅速推出有關工業用水再利用的法規
- 恢復上游油氣工程的管道
- 非洲礦業和金屬產業資本支出(CAPEX)增加
- 對符合 FSSC 22000 標準的食品級幫浦的需求
- 用於本地使用的綠色氫電解裝置的精確計量
- 乾旱地區的離網太陽能水井泵
- 市場限制因素
- 與離心式產品相比,資本支出(CAPEX)和總擁有成本(TCO)更高。
- 複雜維修任務中技術純熟勞工短缺
- 假冒零件的氾濫會降低可靠性。
- 外匯波動導致進口零件成本上升。
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 容積式泵浦原理
- 旋轉泵
- 齒輪
- 長袍
- 螺桿(單螺桿、雙螺桿、三螺桿)
- 貝恩
- 往復泵
- 隔膜
- 活塞/柱塞
- 蠕動
- 旋轉泵
- 按最終用戶行業分類
- 石油和天然氣
- 化工/石油化工
- 水和污水處理
- 食品/飲料
- 發電
- 製藥和生命科學
- 採礦和金屬
- 其他行業
- 材料
- 鑄鐵
- 不銹鋼
- 合金/特殊金屬
- 潤滑類型
- 潤滑
- 未潤滑
- 按流量(立方米/小時)
- 少於10
- 10~50
- 50~200
- 200人或以上
- 按地區
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 科威特
- 阿曼
- 巴林
- 土耳其
- 其他中東國家
- 非洲
- 奈及利亞
- 埃及
- 阿爾及利亞
- 南非
- 肯亞
- 其他非洲國家
- 中東
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Dover Corporation
- Ingersoll Rand Inc.
- Watson-Marlow Fluid Technology Solutions
- Alfa Laval AB
- Gorman-Rupp Company
- Busch Vacuum Solutions
- Celeros Flow Technology
- Flowserve Corporation
- Atlas Copco AB
- Xylem Inc.
- Grundfos Holding A/S
- KSB SE & Co. KGaA
- NETZSCH Pumps & Systems
- SPX FLOW Inc.
- EBARA Corporation
- Desmi A/S
- NOV Inc.(Mono Pumps)
- Verder Group
- PSG(Dover)
- IDEX Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the Middle East and Africa positive displacement pump market size in 2026 is estimated at USD 580.94 million, growing from 2025 value of USD 562.27 million with 2031 projections showing USD 684.02 million, growing at 3.32% CAGR over 2026-2031.
This report is Segmented by Displacement Principle (Rotary Pumps, Reciprocating Pumps), End-User Industry (Oil and Gas, Chemicals and Petrochemicals, and More), Material (Cast Iron, and More), Lubrication (Lubricated, Non-Lubricated), Flow-Rate (Less Than 10, 10-50, 50-200, More Than 200 M3/H), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
MEA Positive Displacement Pumps Market Trends and Insights
Upstream oil and gas project pipeline revival
Thirty upstream projects passing final investment decision in 2024 unlocked USD 125 billion in spending, with national oil companies eager to capitalize on breakeven costs near USD 47 per barrel. ADNOC Gas alone earmarked USD 5 billion for three gas-processing facility expansions, each requiring high-pressure plunger and diaphragm pumps. Saudi Aramco's initiative to raise gas output by 60% before 2030 further enlarges the addressable installed base. These developments translate into recurrent demand spikes for rugged rotary screw and reciprocating units able to handle sour gas and multiphase flow, lifting short-cycle orders in the Middle East and Africa positive displacement pump market.
Rapid industrial water-reuse mandates
Severe water scarcity has pushed Saudi Arabia to target 100% wastewater reuse against an 18% baseline, with the National Water Company committing USD 23 billion to sewage upgrades. Industrial facilities are now obliged to install chemical dosing and sludge-handling systems that operate reliably in corrosive environments. Ceramic membrane pilots at Saudi Aramco have already achieved 85-90% recovery rates, cutting fresh-water draws by 22 million gallons annually. These initiatives favor diaphragm, peristaltic and progressive-cavity pumps configured in duplex stainless steel, sustaining medium-term tailwinds for the Middle East and Africa positive displacement pump market.
High CAPEX and TCO versus centrifugal alternatives
Procurement teams frequently judge equipment on upfront cost, a metric where centrifugal pumps offer savings of 20-30% for high-volume, low-viscosity duties. In commodity-linked African economies, cash-constrained operators select single-stage volutes even when duty conditions favor positive displacement geometry. Vendors respond with energy-efficient upgrades: Wear Reduction Technology embedded in Weir's WARMAN AH line cuts power draw by up to 5%, narrowing lifetime-cost differentials.
Other drivers and restraints analyzed in the detailed report include:
- Rising CAPEX in African mining and metals
- Food-grade pump demand under FSSC 22000
- Proliferation of counterfeit spares eroding reliability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rotary pumps generated 28.15% of 2025 revenue, underlining their entrenched role in viscous-fluid transfer across upstream oil and gas and asphalt blending. Diaphragm and piston reciprocating models together carved out a sizable niche on the strength of leak-free operation when handling aggressive chemicals. The Middle East and Africa positive displacement pump market size for peristaltic designs is projected to climb at a 3.67% CAGR as pharmaceutical formulators shift to single-use tubing for sterility assurance.
Technology roadmaps show gear pumps retaining cost leadership for moderate-pressure duties below 10 bar, while progressive-cavity machines penetrate slurry handling owing to resilient stator materials. Vogelsang's EP series one-piece housing rated to 260 psi and 392 °F demonstrates the innovation thrust toward higher pressure envelopes. Providers are also hybridizing rotary and reciprocating architectures to optimize efficiency at variable flow demands, a trend poised to broaden solution palettes and defend pricing in the Middle East and Africa positive displacement pump market.
Oil and gas accounted for 30.85% of 2025 sales thanks to multiphase transfer, chemical injection and blowout-preventer circuits that demand rugged plunger and twin-screw units able to manage gas entrainment. Water and wastewater followed at 26.52% on the back of desalination and sewage-network upgrades. Chemicals and petrochemicals benefiting from regional downstream integration strategies. Pharmaceuticals, while occupying a smaller base, will pace the market with a 3.74% CAGR through 2031 as sterile processing lines proliferate across UAE, Egypt and Saudi greenfield plants.
Food and beverage manufacturers energized by Gulf food-security programs favoring local production. In mining and metals, a 9.65% share hinged on abrasion-resistant pumping during dewatering and concentrate transfer. Diversifying end-markets distributes risk and cushions revenue swings, reinforcing the resilient outlook for the Middle East and Africa positive displacement pump market.
Complete Report Scope:
- By Displacement Principle
- Rotary Pumps
- Gear
- Lobe
- Screw (Single, Twin, Triple)
- Vane
- Reciprocating Pumps
- Diaphragm
- Piston/Plunger
- Peristaltic
- Rotary Pumps
- By End-user Industry
- Oil and Gas
- Chemicals and Petrochemicals
- Water and Wastewater
- Food and Beverage
- Power Generation
- Pharmaceuticals and Life-Sciences
- Mining and Metals
- Other Industries
- By Material
- Cast Iron
- Stainless Steel
- Alloy and Specialty Metals
- By Lubrication
- Lubricated
- Non-lubricated
- By Flow-rate (cubic meter/hour)
- Less than 10
- 10-50
- 50-200
- More than 200
- By Geography
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Kuwait
- Oman
- Bahrain
- Turkey
- Rest of Middle East
- Africa
- Nigeria
- Egypt
- Algeria
- South Africa
- Kenya
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Dover Corporation
- Ingersoll Rand Inc.
- Watson-Marlow Fluid Technology Solutions
- Alfa Laval AB
- Gorman-Rupp Company
- Busch Vacuum Solutions
- Celeros Flow Technology
- Flowserve Corporation
- Atlas Copco AB
- Xylem Inc.
- Grundfos Holding A/S
- KSB SE & Co. KGaA
- NETZSCH Pumps & Systems
- SPX FLOW Inc.
- EBARA Corporation
- Desmi A/S
- NOV Inc. (Mono Pumps)
- Verder Group
- PSG (Dover)
- IDEX Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid industrial water-reuse mandates
- 4.2.2 Upstream oil and gas project pipeline revival
- 4.2.3 Rising CAPEX in African mining and metals
- 4.2.4 Food-grade pump demand under FSSC 22000
- 4.2.5 Precision dosing for regional green-hydrogen electrolyzers
- 4.2.6 Off-grid solar powered wellhead pumping in arid zones
- 4.3 Market Restraints
- 4.3.1 High CAPEX and TCO versus centrifugal alternatives
- 4.3.2 Skilled-labor scarcity for complex maintenance
- 4.3.3 Proliferation of counterfeit spares eroding reliability
- 4.3.4 Currency volatility inflating imported component costs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Displacement Principle
- 5.1.1 Rotary Pumps
- 5.1.1.1 Gear
- 5.1.1.2 Lobe
- 5.1.1.3 Screw (Single, Twin, Triple)
- 5.1.1.4 Vane
- 5.1.2 Reciprocating Pumps
- 5.1.2.1 Diaphragm
- 5.1.2.2 Piston/Plunger
- 5.1.2.3 Peristaltic
- 5.1.1 Rotary Pumps
- 5.2 By End-user Industry
- 5.2.1 Oil and Gas
- 5.2.2 Chemicals and Petrochemicals
- 5.2.3 Water and Wastewater
- 5.2.4 Food and Beverage
- 5.2.5 Power Generation
- 5.2.6 Pharmaceuticals and Life-Sciences
- 5.2.7 Mining and Metals
- 5.2.8 Other Industries
- 5.3 By Material
- 5.3.1 Cast Iron
- 5.3.2 Stainless Steel
- 5.3.3 Alloy and Specialty Metals
- 5.4 By Lubrication
- 5.4.1 Lubricated
- 5.4.2 Non-lubricated
- 5.5 By Flow-rate (cubic meter/hour)
- 5.5.1 Less than 10
- 5.5.2 10-50
- 5.5.3 50-200
- 5.5.4 More than 200
- 5.6 By Geography
- 5.6.1 Middle East
- 5.6.1.1 Saudi Arabia
- 5.6.1.2 United Arab Emirates
- 5.6.1.3 Qatar
- 5.6.1.4 Kuwait
- 5.6.1.5 Oman
- 5.6.1.6 Bahrain
- 5.6.1.7 Turkey
- 5.6.1.8 Rest of Middle East
- 5.6.2 Africa
- 5.6.2.1 Nigeria
- 5.6.2.2 Egypt
- 5.6.2.3 Algeria
- 5.6.2.4 South Africa
- 5.6.2.5 Kenya
- 5.6.2.6 Rest of Africa
- 5.6.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dover Corporation
- 6.4.2 Ingersoll Rand Inc.
- 6.4.3 Watson-Marlow Fluid Technology Solutions
- 6.4.4 Alfa Laval AB
- 6.4.5 Gorman-Rupp Company
- 6.4.6 Busch Vacuum Solutions
- 6.4.7 Celeros Flow Technology
- 6.4.8 Flowserve Corporation
- 6.4.9 Atlas Copco AB
- 6.4.10 Xylem Inc.
- 6.4.11 Grundfos Holding A/S
- 6.4.12 KSB SE & Co. KGaA
- 6.4.13 NETZSCH Pumps & Systems
- 6.4.14 SPX FLOW Inc.
- 6.4.15 EBARA Corporation
- 6.4.16 Desmi A/S
- 6.4.17 NOV Inc. (Mono Pumps)
- 6.4.18 Verder Group
- 6.4.19 PSG (Dover)
- 6.4.20 IDEX Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 亞太地區正壓泵:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 可變排量幫浦市場分析與預測(至2035年):類型、產品、技術、組件、應用、最終用戶、功能、安裝類型、設備、解決方案容積式幫浦:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 容積式幫浦市場-2026-2032年全球市場預測
 2026-2030年全球往復式柱塞泵浦市場
 容積式幫浦市場報告:依產品類型、容量、幫浦特性、原料、終端用戶產業和地區分類(2026-2034 年)
 全球正壓泵市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 容積式幫浦市場:按類型、應用、最終用戶和地區分類活塞泵和柱塞泵市場按泵類型、驅動類型、流量、壓力、安裝方式、最終用途行業和配銷通路分類,全球預測,2026-2032年線性泵浦市場按類型、技術、流量、材料、終端用戶產業和分銷管道分類,全球預測,2026-2032年