


 |
市場調查報告書
商品編碼
2125296
亞太地區感應電動機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Asia-Pacific Induction Motor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
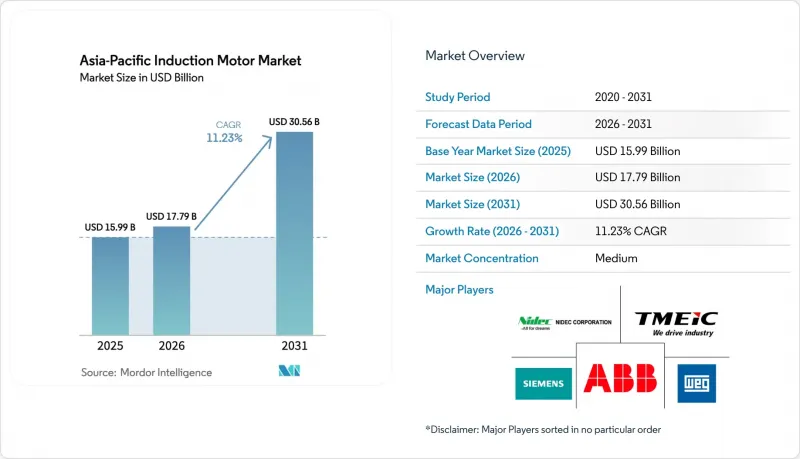
據 Mordor Intelligence 稱,2025 年亞太地區感應電動機市值為 159.9 億美元,預計到 2031 年將從 2026 年的 177.9 億美元成長至 305.6 億美元,預測期(2026-2031 年)複合年成長率為 11.23%。
本報告以相數(單相和三相感應電動機) 、額定功率(小於0.5 kW、0.5 kW至7.5 kW、7.5 kW至37 kW、37 kW至75 kW、大於75 kW)、能源效率等級(IE1、IE2、IE3、IE4)、用戶化工業(石油化和終端發電等地區進行石化)、區域化工、市場預測以美元(USD)計價。
亞太地區感應電動機市場趨勢及洞察
對更高能源效率的需求日益成長
由於電力公司的需量反應計劃、碳定價機制以及企業淨零排放承諾,能源效率已成為亞太地區整個感應電動機市場的首要採購重點。馬達驅動系統消耗了全球約45%的電力,因此提高能源效率對於電網穩定性和減少排放至關重要。非晶質金屬磁芯和最佳化磁路等技術進步已使能源效率超過IE4等級。日立的徑向氣隙原型機在20,000轉/分時即可達到95%的效率,而體積僅為傳統馬達的五分之一。結合變頻驅動裝置和智慧控制演算法,這些創新技術可為採礦、獎勵和數據處理等能源密集產業帶來快速的投資回報。經濟和環境獎勵的融合將確保中期內對高階馬達的穩定需求。
亞太地區政府能源效率法規
監管標準對於推動亞太地區感應電動機市場向更高能源效率等級發展至關重要。在中國,IE3是大多數工業應用的最低標準,而日本的「頂級跑者計畫」(Top Runner Program)則不斷提高基準值。在澳大利亞,功率超過0.73千瓦的馬達必須符合特定的能源效率標準。這些政策觸發了旨在符合監管要求的更新週期,迫使原始設備製造商(OEM)將IE3和IE4馬達整合到面向受監管市場的設備中。東協內部關於監管協調的討論表明,類似的規則將被更廣泛地採用,預計這將增加東南亞地區對高性能馬達的需求。儘早調整產品線的製造商將獲得市場佔有率,並降低最終用戶在時間緊迫的情況下維修的複雜性。
永磁同步馬達的替代方案
永磁同步馬達(PMSM)具有高功率密度和優異的部分負載效率,因此在精密速度控制應用領域逐漸蠶食感應馬達的市場佔有率。中國汽車製造商廣汽集團開發的e-Drive馬達效率高達98.5%,充分展現了PMSM的性能優勢以及稀土元素價格穩定帶來的成本優勢。在機器人和伺服應用領域,PMSM能夠實現微秒級的反應時間和小型化,從而改變了消費者對感應馬達技術的偏好。感應馬達供應商正透過混合設計和改進的控制軟體來應對,但競爭仍然激烈,尤其是在高階功率領域。
細分市場分析
預計到2025年,三相馬達將在亞太地區感應馬達市場佔據78.62%的市場佔有率,凸顯其在工業運作中的核心地位,因為平衡的功率輸出和強大的扭力至關重要。隨著製造地自動化程度的不斷提高,亞太地區三相感應電動機市場預計將穩定成長。單相馬達則佔剩餘的21.38%,憑藉其易於安裝和與標準商用電源高度相容的優勢,在分散式製造和住宅自動化領域迅速普及。
工業機器人、精密加工和輸送機系統持續推動對三相馬達的需求,尤其是在中國、日本和韓國。同時,東南亞小規模車間、住宅暖通空調系統和邊緣運算設備的日益普及,正以兩位數的複合年成長率推動單相馬達的市場成長。供應商正根據馬達類型調整行銷策略,向三相馬達買家強調其耐用性和先進的控制技術,而向潛在的單相馬達客戶突出其價格優勢和即插即用的便利性。
至2025年,輸出範圍在0.5千瓦至7.5千瓦之間的感應馬達將佔亞太地區感應電動機市場規模的33.25%,這反映出其在輔助泵浦、壓縮機和通用機械等領域的廣泛應用。儘管功率低於0.5千瓦的機型市場規模較小,但由於小型物聯網設備和小型化暖通空調系統的普及,預計其複合年成長率將達到11.52%。
高功率馬達主要服務於大規模採礦、石油化工和發電等行業,但由於裝置容量成長緩慢以及企業優先考慮效率提升而非新建設,其成長速度受到限制。另一方面,磁性材料和冷卻技術的進步提高了功率密度,使得功率較低的馬達也能完成以往只有高功率馬達才能完成的任務。這一發展趨勢進一步強化了亞太地區感應電動機市場「雙管齊下」的成長態勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 提高能源效率的需求日益成長
- 住宅和工業領域對能源效率的需求日益成長。
- 亞太地區政府能源效率法規
- 加快工業自動化的投資
- 東南亞資料中心建設迅速擴張
- 現有設施中IE4馬達的即插即用式改造
- 市場限制因素
- 永磁同步馬達的替代方案
- 高效率(IE4)感應電動機的初始成本較高
- 新興國家電網的不穩定性限制了高功率馬達的普及應用。
- 逆變器產生的諧波會導致馬達過早損壞。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按階段
- 單相感應電動機
- 三相感應電動機
- 額定功率
- 小於0.5千瓦
- 0.5 kW~7.5 kW
- 7.5 kW~37 kW
- 37 kW~75 kW
- 75千瓦或以上
- 能源效率等級
- IE1 標準效率
- IE2 高效
- IE3 高階效率
- IE4 超高效
- 按最終用戶行業分類
- 石油和天然氣
- 化工/石油化工
- 發電
- 水和污水處理
- 金屬和採礦
- 食品/飲料
- 離散製造
- 暖氣、通風和空調(HVAC)
- 其他終端用戶產業
- 國家
- 中國
- 印度
- 日本
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB Ltd.
- Siemens AG
- Nidec Corporation
- Toshiba Mitsubishi-Electric Industrial Systems Corporation(TMEIC)
- WEG SA
- Regal Rexnord Corporation
- Fuji Electric Co., Ltd.
- Kirloskar Electric Company Limited
- SEALOCEAN Motor Co., Ltd.
- TECO Electric and Machinery Co., Ltd.
- Hyundai Electric and Energy Systems Co., Ltd.
- CG Power and Industrial Solutions Limited
- Brook Crompton Asia Pacific Pte. Ltd.
- Leroy-Somer(Nidec Leroy-Somer Holding)
- Toshiba Corporation
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Lafert Group SpA
- Bharat Bijlee Limited
- Marathon Electric India Pvt. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Asia Pacific induction motor market size was valued at USD 15.99 billion in 2025 and estimated to grow from USD 17.79 billion in 2026 to reach USD 30.56 billion by 2031, at a CAGR of 11.23% during the forecast period (2026-2031).
This report is Segmented by Phase (Single Phase Induction Motor, and Three Phase Induction Motor), Power Rating (Below 0. 5 KW, 0. 5 KW - 7. 5 KW, 7. 5 KW - 37 KW, 37 KW - 75 KW, and Above 75 KW), Efficiency Class (IE1, IE2, IE3, IE4), End-User Industry (Oil and Gas, Power Generation, Chemical and Petrochemical, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Induction Motor Market Trends and Insights
Increasing Need for Higher Energy Efficiency
Utility demand-response programs, carbon pricing mechanisms, and corporate net-zero pledges elevate energy efficiency to the top of procurement criteria across the Asia Pacific induction motor market. Motor-driven systems consume nearly 45% of the world's power, making efficiency gains pivotal for grid stability and reducing emissions. Advances such as amorphous-metal cores and optimized magnetic circuits push efficiencies beyond IE4 levels. Hitachi's radial-gap prototype achieves 95% efficiency at 20,000 rpm, while occupying one-fifth the volume of conventional motors. Coupled with variable-frequency drives and smart control algorithms, these innovations yield rapid paybacks in energy-intensive sectors including mining, petrochemicals, and data processing. The convergence of economic and environmental incentives secures steady demand for premium-class motors over the medium term.
Government Energy-Efficiency Mandates Across the Asia Pacific
Regulatory standards are pivotal in steering the Asia Pacific induction motor market toward higher efficiency classes. China enforces IE3 as the minimum standard for most industrial applications, Japan's Top Runner program continually raises benchmarks, and Australia mandates specific efficiency thresholds for motors exceeding 0.73 kW. These policies trigger compliance-driven replacement cycles, compelling OEMs to integrate IE3 and IE4 motors into equipment destined for regulated markets. Harmonization discussions within ASEAN are pointing to the broader adoption of similar rules, which is expected to amplify demand for premium motors across Southeast Asia. Manufacturers that align product lines early capture share and reduce retrofit complexity for end users facing binding deadlines.
Availability of Permanent-Magnet Synchronous Motor Alternatives
Permanent-magnet synchronous motors (PMSMs) boast higher power density and superior part-load efficiency, thereby eroding the induction motor's share in precision-speed applications. Chinese automaker GAC's 98.5% efficient e-drive demonstrates PMSM performance advantages and cost convergence as rare-earth prices stabilize. In robotics and servo duties, PMSMs offer microsecond response times, along with smaller footprints, tilting buyer preference away from induction technology. Induction suppliers counter with hybrid designs and control-software enhancements, yet the competitive threat persists, particularly in premium power segments.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Industrial Automation Investments
- Rapid Growth in Data Center Construction Across Southeast Asia
- High Initial Cost of Premium-Efficiency (IE4) Induction Motors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Three-phase motors secured a 78.62% market share in the Asia Pacific induction motor market in 2025, underscoring their centrality to industrial operations that value balanced power delivery and robust torque. The Asia Pacific induction motor market size for three-phase units is expected to expand steadily as automation intensifies in manufacturing hubs. Single-phase motors, which hold the remaining 21.38%, are rapidly scaling across distributed manufacturing and residential automation, benefiting from their straightforward installation and compatibility with standard utility feeds.
Industrial robotics, precision machining, and conveyor systems continue to anchor three-phase demand, particularly in China, Japan, and South Korea. Conversely, the growth of small workshops, residential HVAC, and edge-computing installations in Southeast Asia propels single-phase uptake at a double-digit CAGR. Suppliers tailor marketing strategies by phase, promoting durability and control sophistication for three-phase buyers while emphasizing price and plug-and-play convenience for single-phase prospects.
The 0.5 kW - 7.5 kW bracket commanded 33.25% of the Asia Pacific induction motor market size in 2025, reflecting its deployment across auxiliary pumps, compressors, and general-purpose machinery. Sub-0.5 kW units, though smaller in value, are projected to register an 11.52% CAGR as compact IoT devices and miniaturized HVAC systems proliferate.
High-power segments above 75 kW cater to large-scale mining, petrochemical, and power generation duties, yet modest capacity additions and a preference for efficiency upgrades over new builds cap their growth pace. In parallel, advances in magnetic materials and cooling techniques elevate power density, enabling lower-rating motors to perform tasks once reserved for larger frames. This evolution reinforces the twin-track growth narrative of the Asia Pacific induction motor market.
Complete Report Scope:
- By Phase
- Single Phase Induction Motor
- Three Phase Induction Motor
- By Power Rating
- Below 0.5 kW
- 0.5 kW - 7.5 kW
- 7.5 kW - 37 kW
- 37 kW - 75 kW
- Above 75 kW
- By Efficiency Class
- IE1 Standard Efficiency
- IE2 High Efficiency
- IE3 Premium Efficiency
- IE4 Super Premium Efficiency
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Power Generation
- Water and Wastewater
- Metal and Mining
- Food and Beverage
- Discrete Manufacturing
- Heating, Ventilation and Air-Conditioning (HVAC)
- Other End-User Industries
- By Country
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Siemens AG
- Nidec Corporation
- Toshiba Mitsubishi-Electric Industrial Systems Corporation (TMEIC)
- WEG S.A.
- Regal Rexnord Corporation
- Fuji Electric Co., Ltd.
- Kirloskar Electric Company Limited
- SEALOCEAN Motor Co., Ltd.
- TECO Electric and Machinery Co., Ltd.
- Hyundai Electric and Energy Systems Co., Ltd.
- CG Power and Industrial Solutions Limited
- Brook Crompton Asia Pacific Pte. Ltd.
- Leroy-Somer (Nidec Leroy-Somer Holding)
- Toshiba Corporation
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Lafert Group S.p.A.
- Bharat Bijlee Limited
- Marathon Electric India Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Need for Higher Energy Efficiency
- 4.2.2 Rising Demand for Power Savings in Residential and Industrial Sectors
- 4.2.3 Government Energy-Efficiency Mandates Across Asia Pacific
- 4.2.4 Accelerating Industrial Automation Investments
- 4.2.5 Rapid Growth in Data Center Construction Across Southeast Asia
- 4.2.6 Plug-and-Play IE4 Motor Retrofits in Brownfield Facilities
- 4.3 Market Restraints
- 4.3.1 Availability of Permanent-Magnet Synchronous Motor Alternatives
- 4.3.2 High Initial Cost of Premium-Efficiency (IE4) Induction Motors
- 4.3.3 Grid Instability in Emerging Economies Limiting Large-Motor Deployment
- 4.3.4 Inverter-Driven Harmonics Causing Early Motor Failures
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers/Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Phase
- 5.1.1 Single Phase Induction Motor
- 5.1.2 Three Phase Induction Motor
- 5.2 By Power Rating
- 5.2.1 Below 0.5 kW
- 5.2.2 0.5 kW - 7.5 kW
- 5.2.3 7.5 kW - 37 kW
- 5.2.4 37 kW - 75 kW
- 5.2.5 Above 75 kW
- 5.3 By Efficiency Class
- 5.3.1 IE1 Standard Efficiency
- 5.3.2 IE2 High Efficiency
- 5.3.3 IE3 Premium Efficiency
- 5.3.4 IE4 Super Premium Efficiency
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Power Generation
- 5.4.4 Water and Wastewater
- 5.4.5 Metal and Mining
- 5.4.6 Food and Beverage
- 5.4.7 Discrete Manufacturing
- 5.4.8 Heating, Ventilation and Air-Conditioning (HVAC)
- 5.4.9 Other End-User Industries
- 5.5 By Country
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 South Korea
- 5.5.5 Australia and New Zealand
- 5.5.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 Nidec Corporation
- 6.4.4 Toshiba Mitsubishi-Electric Industrial Systems Corporation (TMEIC)
- 6.4.5 WEG S.A.
- 6.4.6 Regal Rexnord Corporation
- 6.4.7 Fuji Electric Co., Ltd.
- 6.4.8 Kirloskar Electric Company Limited
- 6.4.9 SEALOCEAN Motor Co., Ltd.
- 6.4.10 TECO Electric and Machinery Co., Ltd.
- 6.4.11 Hyundai Electric and Energy Systems Co., Ltd.
- 6.4.12 CG Power and Industrial Solutions Limited
- 6.4.13 Brook Crompton Asia Pacific Pte. Ltd.
- 6.4.14 Leroy-Somer (Nidec Leroy-Somer Holding)
- 6.4.15 Toshiba Corporation
- 6.4.16 Mitsubishi Electric Corporation
- 6.4.17 Schneider Electric SE
- 6.4.18 Lafert Group S.p.A.
- 6.4.19 Bharat Bijlee Limited
- 6.4.20 Marathon Electric India Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 北美感應電動機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)感應電動機:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)北美低壓感應電動機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 全球感應電動機市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 感應馬達市場:2026-2032年全球市場預測(按類型、安裝方式、能源效率等級、功率輸出、應用、終端用戶產業和銷售管道)
 2026-2034年感應電動機市場規模、佔有率、趨勢及預測(依產品類型、最終用途產業及地區分類)以相數、機殼、電壓、額定功率、轉速、安裝方式和應用分類的鼠籠式感應電動機市場-2026-2032年全球預測
 感應電動機市場機會、成長要素、產業趨勢分析及預測(2026年至2035年)
 感應馬達市場-全球產業規模、佔有率、趨勢、機會及預測(細分、按類型、按應用、按地區、按競爭,2020-2030 年預測)歐洲感應電動機:市場佔有率分析、產業趨勢與統計、成長預測(2025-2030)