


 |
市場調查報告書
商品編碼
2124953
亞太地區可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Asia-Pacific Programmable Logic Controller - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
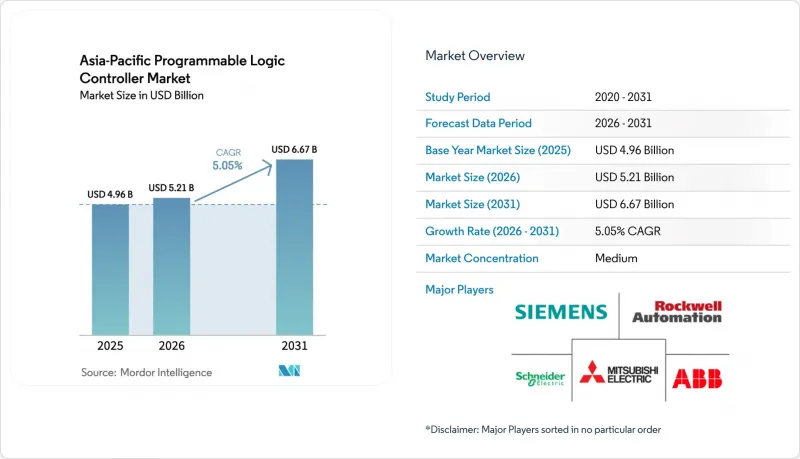
根據 Mordor Intelligence 預測,亞太地區可程式邏輯控制器 (PLC) 市場規模將從 2025 年的 49.6 億美元成長到 2026 年的 52.1 億美元,然後在 2031 年達到 66.7 億美元,2026 年至 2031 年的複合年成長率為 5.05%。
本報告按類型(硬體、軟體、服務)、架構(緊湊型PLC、模組化PLC、其他)、最終用戶(汽車、食品、菸草和飲料、化學和石化、其他)、輸入/輸出類型(數位I/O、類比I/O、混合I/O)和國家細分。市場預測以美元(USD)為單位。
亞太地區可程式邏輯控制器(PLC)市場趨勢與洞察
汽車電動車生產線快速成長
電動車組裝需要對電池組進行精確的溫度控制,協調多軸馬達繞組,並採用經過認證的功能安全控制。中國整車製造商已建立起標準化的自動化模板,這些模板目前正被周邊市場採用,迫使PLC供應商整合更快的處理能力和更強大的通訊協定堆疊。隨著電動車在中國以外的普及,ISO 26262標準的實施進一步提高了技術進入門檻。印度和東南亞的本地生產線製造商正在採用模組化PLC來縮短部署時間。因此,供應商之間的差異化因素正從高密度硬體轉向整合的運動庫和電動車專用診斷功能。為適應不斷變化的電池化學成分,持續的產品更新也維持了對控制器的長期需求。
政府主導的智慧製造補貼
中國的「中國製造2025」、日本的「社會5.0」和韓國的「K-Digital新政」等戰略項目都在投資加速自動化普及。與補貼掛鉤的截止日期壓縮了專案工期,使具備承包服務能力的供應商受益。稅額扣抵和低利率貸款降低了投資回報門檻,鼓勵中小型製造商進入亞太可程式邏輯控制器(PLC)市場。然而,需求的加速成長也帶來了獎勵結束後需求放緩的風險。印度的「生產連結獎勵計畫(PLI)」計畫可以鼓勵國內組裝,並改變進口格局。此外,受津貼工廠的集中化可以促進生態系統內的知識轉移,進一步增強區域成長動能。
初期整合和培訓成本高。
系統設計、佈線、試運行和操作人員培訓可能使專案成本高達硬體價格的三倍。印度和東南亞的中小型企業面臨資金籌措困難,儘管自動化投資回報誘人,但仍難以採用。合格整合商的短缺推高了人事費用,延長了專案週期。與傳統設備的整合通常需要客製化閘道器,增加了實施風險。製造商擔心停機時間過長,因此選擇部分或全部自動化,這抑制了亞太市場對可程式邏輯控制器 (PLC) 的短期需求。為了應對這種情況,供應商正在提供預先設計的模板和遠端培訓模組,以縮短學習曲線。
細分市場分析
隨著製造商將重點從獨立硬體轉向整合專業知識、預測性維護和生命週期最佳化,服務業以 6.05% 的複合年成長率 (CAGR) 成長,創造了最大的增量收入。硬體和軟體元件繼續主導亞太地區可程式邏輯控制器 (PLC) 的市場佔有率,預計到 2025 年將達到 75.05%。這反映了中國和印度產能的持續擴張。業務收益受益於多年期契約,與更容易受經濟波動影響的硬體銷售相比,能夠提供更穩定的現金流。遠端監控和基於雲端的分析支持了這一轉變,減少了意外停機時間,並為收取加值服務費提供了合理依據。
系統整合商正利用其領域專業知識,將傳統設備與最先進的控制器整合,從而縮短部署時間。無線韌體更新和靈活的許可方案正在提高可擴展性並降低資本投資門檻。雖然石化工廠的大規模部署仍然依賴高階硬體,但分散式物聯網節點擴大採用具有SaaS軟體包的奈米控制器和微控制器。因此,供應商正在將其產品組合調整為基於結果的模式,亞太地區可程式邏輯控制器(PLC)市場的經常性收入比例正在擴大。
模組化PLC因其在複雜生產線中的可擴展性而備受青睞,預計到2025年將保持55.10%的市場佔有率。然而,透過虛擬化技術在工業用電腦上實現確定性性能的軟PLC平台,正以6.68%的複合年成長率成長,並蠶食現有供應商的市場佔有率。汽車電池生產線的早期採用者正在部署容器化控制應用,以實現配方的快速變更和集中式版本控制。機架式配置滿足製程工業的高密度I/O需求,而緊湊型單元則適用於撬裝設備和OEM機械。
邊緣閘道器將可程式邏輯、資料聚合和人工智慧推理整合到單塊電路板上,模糊了不同功能之間的界限。供應商透過即時虛擬機器管理程式、安全啟動序列以及與IT編配工具的相容性來凸顯自身優勢。因此,買家擴大評估整個系統架構,而不是單一控制器型號,這正在重塑亞太地區可程式邏輯控制器(PLC)市場的採購標準。隨著軟體平台的成熟,硬體更新周期預計將會縮短,訂閱式升級也將變得更加普遍。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素的影響
- 市場促進因素
- 汽車電動車生產線快速成長
- 政府主導的智慧製造補貼
- 低成本模組化PLC的快速普及
- 遷移到符合工業4.0標準的PLC平台,並採取相應的網路安全措施。
- 對節能型公用事業自動化的需求
- 利用5G技術的時敏網路(TSN)的興起
- 市場限制因素
- 初期整合和培訓成本高。
- 半導體供應長期短缺
- 低程式碼軟體PLC的替代方案的可用性
- 網路安全合規支出增加
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 硬體和軟體
- 大型PLC
- NanoPLC
- 小型PLC
- 中型PLC
- 軟體
- 其他
- 服務
- 硬體和軟體
- 以建築學為例
- 小型PLC
- 模組化PLC
- 機架式PLC
- 軟PLC(基於PC)
- 最終用戶
- 車
- 食品、菸草和飲料
- 化工/石油化工
- 能源與公共產業
- 石油和天然氣
- 供水和廢水處理
- 製藥
- 紙漿和造紙
- 其他
- 按輸入/輸出類型
- 數位 I/O
- 類比輸入/輸出
- 混合 I/O
- 國家
- 中國
- 日本
- 印度
- 韓國
- 東南亞
- 亞太其他地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB Ltd.
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Rockwell Automation Inc.
- Siemens AG
- Honeywell International Inc.
- Omron Corporation
- Panasonic Holdings Corporation
- Robert Bosch GmbH
- Emerson Electric Co.
- Hitachi Ltd.
- Toshiba International Corporation
- Delta Electronics Inc.
- Beckhoff Automation GmbH and Co. KG
- LS Electric Co., Ltd.
- Fuji Electric Co., Ltd.
- B and R Industrial Automation GmbH
- IDEC Corporation
- Yokogawa Electric Corporation
- WAGO Kontakttechnik GmbH and Co. KG
第7章 市場機會與未來展望
According to Mordor Intelligence, the Asia-Pacific programmable logic controller market size is expected to grow from USD 4.96 billion in 2025 to USD 5.21 billion in 2026 and is forecast to reach USD 6.67 billion by 2031 at 5.05% CAGR over 2026-2031.
This report is Segmented by Type (Hardware and Software and Services), Architecture (Compact PLC, Modular PLC, and More), End-User (Automotive, Food, Tobacco and Beverage, Chemical and Petrochemical, and More), Input/Output Type (Digital I/O, Analog I/O, and Mixed I/O), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Programmable Logic Controller Market Trends and Insights
Surge in Automotive E-mobility Production Lines
Electric-vehicle assembly requires precise temperature management of the battery pack, coordination of multi-axis motor windings, and certified functional safety controls. China's OEMs have established reference automation templates that neighboring markets are now replicating, compelling PLC vendors to incorporate higher-speed processing and expanded communication stacks. ISO 26262 mandates further raising technical entry barriers as e-mobility expands beyond China. Localized line-builders in India and Southeast Asia source modular PLCs to shorten deployment times. Vendor differentiation is therefore shifting from hardware density to integrated motion libraries and EV-specific diagnostics. Continuous product updates, aligning with evolving battery chemistries, sustain long-term demand for controllers.
Government-led Smart Manufacturing Subsidies
Strategic programs such as China's "Made in China 2025," Japan's Society 5.0, and South Korea's K-Digital New Deal inject funding that accelerates automation procurement. Subsidy-linked deadlines compress project timelines, benefiting suppliers with turnkey service capabilities. Tax credits and low-interest loans lower payback thresholds, drawing small and medium manufacturers into the Asia-Pacific programmable logic controller market. However, pull-forward demand risks post-incentive slowdowns. India's Production Linked Incentive scheme fosters domestic assembly, potentially altering import patterns. Clustering of subsidized plants also enhances ecosystem knowledge transfer, reinforcing regional growth momentum.
High Upfront Integration and Training Costs
Total project outlays can triple the hardware price due to system design, wiring, commissioning, and operator upskilling. SMEs in India and Southeast Asia struggle to secure financing, which delays automation despite its attractive paybacks. Shortages of qualified integrators inflate labor costs and extend timelines. Legacy equipment interfacing often requires custom gateways, which raises implementation risk. Manufacturers wary of prolonged shutdowns opt for partial or no automation, tempering near-term demand for programmable logic controllers in the Asia-Pacific market. Vendors respond with pre-engineered templates and remote training modules to compress learning curves.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of Low-cost Modular PLCs
- Migration to Industry 4.0 Cyber-secure PLC Platforms
- Prolonged Semiconductor Supply Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated the highest incremental revenue, expanding at a 6.05% CAGR, as manufacturers prioritize integration expertise, predictive maintenance, and lifecycle optimization over standalone hardware. Hardware and software components continued to dominate the Asia-Pacific programmable logic controller market share, accounting for 75.05% in 2025, reflecting ongoing capacity expansions in China and India. Services revenue benefits from multi-year contracts, delivering steadier cash flows than cyclical hardware sales. Remote monitoring and cloud-based analytics underpin this shift, reducing unplanned downtime and justifying premium service fees.
System integrators leverage domain know-how to bridge legacy equipment with modern controllers, compressing deployment timelines. Over-the-air firmware updates and flexible licensing enhance scalability, mitigating capital-expenditure hurdles. Large installations in petrochemical plants still rely on high-end hardware, but nano- and microcontrollers with SaaS packages are gaining traction in dispersed IoT nodes. Consequently, vendors reorient portfolios toward outcome-based models, expanding the Asia-Pacific programmable logic controller market's recurring-revenue proportion.
Modular PLCs retained 55.10% revenue leadership in 2025, favored for their expandability in complex lines. Nonetheless, soft PLC platforms posted a 6.68% CAGR, eroding incumbents' share as virtualization delivers deterministic performance on industrial PCs. Early adopters in automotive battery lines deploy containerized control applications to enable rapid recipe changes and centralized version management. Rack-mount configurations address dense I/O needs in process industries, whereas compact units cater to skid-mounted equipment and OEM machinery.
Edge gateways integrate programmable logic, data aggregation, and AI inference on a single board, thereby blurring the boundaries between different functions. Vendors differentiate through real-time hypervisors, secure boot sequences, and compatibility with IT orchestration tools. As a result, buyers evaluate total system architecture rather than discrete controller models, reshaping procurement criteria within the Asia-Pacific programmable logic controller market. Continued maturation of the soft platform will likely compress hardware refresh cycles, encouraging subscription-based upgrades.
Complete Report Scope:
- By Type
- Hardware and Software
- Large PLC
- Nano PLC
- Small PLC
- Medium PLC
- Software
- Other Types
- Services
- Hardware and Software
- By Architecture
- Compact PLC
- Modular PLC
- Rack-mount PLC
- Soft PLC (PC-based)
- By End-User
- Automotive
- Food, Tobacco and Beverage
- Chemical and Petrochemical
- Energy and Utilities
- Oil and Gas
- Water and Wastewater Treatment
- Pharmaceutical
- Pulp and Paper
- Other End-Users
- By Input / Output Type
- Digital I/O
- Analog I/O
- Mixed I/O
- By Country
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Rockwell Automation Inc.
- Siemens AG
- Honeywell International Inc.
- Omron Corporation
- Panasonic Holdings Corporation
- Robert Bosch GmbH
- Emerson Electric Co.
- Hitachi Ltd.
- Toshiba International Corporation
- Delta Electronics Inc.
- Beckhoff Automation GmbH and Co. KG
- LS Electric Co., Ltd.
- Fuji Electric Co., Ltd.
- B and R Industrial Automation GmbH
- IDEC Corporation
- Yokogawa Electric Corporation
- WAGO Kontakttechnik GmbH and Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Market Drivers
- 4.3.1 Surge in automotive e-mobility production lines
- 4.3.2 Government-led smart-manufacturing subsidies
- 4.3.3 Rapid expansion of low-cost modular PLCs
- 4.3.4 Migration to Industry 4.0 cyber-secure PLC platforms
- 4.3.5 Demand for energy-efficient utility automation
- 4.3.6 Emerging 5G-enabled time-sensitive networking (TSN)
- 4.4 Market Restraints
- 4.4.1 High upfront integration and training costs
- 4.4.2 Prolonged semiconductor supply constraints
- 4.4.3 Availability of low-code soft-PLC substitutes
- 4.4.4 Rising cyber-security compliance expenditures
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Hardware and Software
- 5.1.1.1 Large PLC
- 5.1.1.2 Nano PLC
- 5.1.1.3 Small PLC
- 5.1.1.4 Medium PLC
- 5.1.1.5 Software
- 5.1.1.6 Other Types
- 5.1.2 Services
- 5.1.1 Hardware and Software
- 5.2 By Architecture
- 5.2.1 Compact PLC
- 5.2.2 Modular PLC
- 5.2.3 Rack-mount PLC
- 5.2.4 Soft PLC (PC-based)
- 5.3 By End-User
- 5.3.1 Automotive
- 5.3.2 Food, Tobacco and Beverage
- 5.3.3 Chemical and Petrochemical
- 5.3.4 Energy and Utilities
- 5.3.5 Oil and Gas
- 5.3.6 Water and Wastewater Treatment
- 5.3.7 Pharmaceutical
- 5.3.8 Pulp and Paper
- 5.3.9 Other End-Users
- 5.4 By Input / Output Type
- 5.4.1 Digital I/O
- 5.4.2 Analog I/O
- 5.4.3 Mixed I/O
- 5.5 By Country
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 India
- 5.5.4 South Korea
- 5.5.5 South-East Asia
- 5.5.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core segments, Financials as available, Strategic information, Market rank/share for key companies, Products and services, and Recent developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Mitsubishi Electric Corporation
- 6.4.3 Schneider Electric SE
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Siemens AG
- 6.4.6 Honeywell International Inc.
- 6.4.7 Omron Corporation
- 6.4.8 Panasonic Holdings Corporation
- 6.4.9 Robert Bosch GmbH
- 6.4.10 Emerson Electric Co.
- 6.4.11 Hitachi Ltd.
- 6.4.12 Toshiba International Corporation
- 6.4.13 Delta Electronics Inc.
- 6.4.14 Beckhoff Automation GmbH and Co. KG
- 6.4.15 LS Electric Co., Ltd.
- 6.4.16 Fuji Electric Co., Ltd.
- 6.4.17 B and R Industrial Automation GmbH
- 6.4.18 IDEC Corporation
- 6.4.19 Yokogawa Electric Corporation
- 6.4.20 WAGO Kontakttechnik GmbH and Co. KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 中東可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 嵌入式運動控制器市場規模、佔有率和成長分析:按控制器類型、應用、通訊介面、最終用戶、安裝方式和地區分類-2026-2033年產業預測
 虛擬PLC與軟PLC市場分析及預測(至2035年):類型、產品、服務、技術、組件、應用、部署、最終用戶、功能、解決方案歐洲可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 嵌入式控制器市場報告:趨勢、預測與競爭分析(至2035年)可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 可程式邏輯控制器(PLC)市場-2026-2032年全球市場預測
 2026-2030年全球可程式邏輯控制器(PLC)市場
 可程式材料市場預測至2034年-按材料類型、刺激類型、功能、應用、形態和地區分類的全球分析可程式邏輯控制器 (PLC) 市場預測至 2034 年——按類型、組件、行業、應用、最終用戶和地區分類的全球分析