


 |
市場調查報告書
商品編碼
2124501
中東可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Middle East Programmable Logic Controller - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
預計到 2026 年,中東可程式邏輯控制器市場規模將達到 8.0393 億美元,高於 2025 年的 7.6 億美元,預計到 2031 年將達到 10.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.78%。
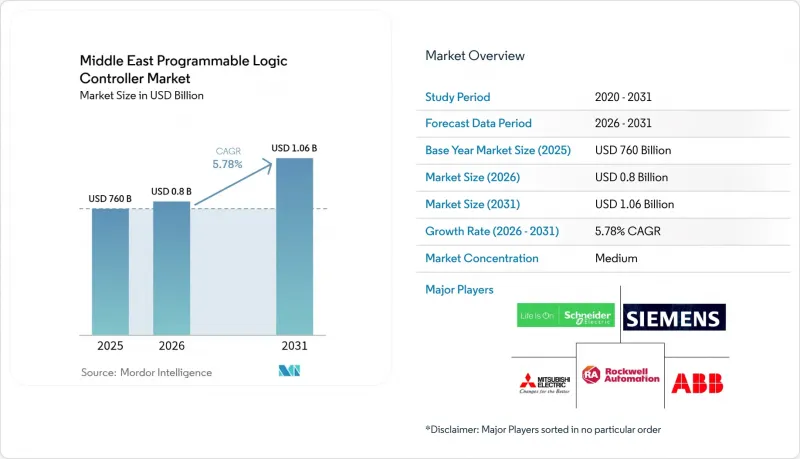
本報告按組件(硬體、軟體、服務)、PLC類型(奈米PLC、微型PLC等)、架構(固定式/緊湊型PLC、模組化/機架式PLC)、最終用戶產業(石油天然氣、化學和石化等)以及國家/地區(阿拉伯聯合大公國、沙烏地阿拉伯等)進行細分。市場預測以美元(USD)計價。
中東可程式邏輯控制器市場趨勢與洞察
擴大石油和天然氣產業的數位化項目
全球各地的國有石油公司都在採用以PLC為核心的數位孿生技術,以縮短鑽井週期並推遲新井的資本投資。阿布達比國家石油公司(ADNOC)的Neuron 5平台將海上和陸上資產的意外停機時間減少了50%,維護間隔延長了20%。沙烏地阿美公司的RoboWell系統透過將地下遙測技術與地面PLC整合,並最佳化鑽頭重量和轉速,將非生產時間減少了30%。卡達北部液化天然氣田擴建工程強制要求使用符合IEC 61511 SIL-3標準的PLC,預計將推動未來幾年硬體和軟體的需求。這些應用案例清楚地表明,儘管硬體基礎設施規模龐大,但軟體收入為何仍高於硬體收入。隨著分析處理向邊緣運算轉移,中東可程式邏輯控制器市場正受益於安裝在現有機架上的定期軟體更新。
自動化棕地維修激增
上世紀八、九十年代投入運作的老舊煉油廠和石化廠正面臨日益嚴格的排放標準,因此紛紛升級為模組化PLC,以降低能耗並增加遠距離診斷功能。阿布達比國家石油公司(ADNOC)天然氣部門在哈布山5號煉油廠用機架式PLC取代了氣壓執行器,能耗降低了15%。沙烏地阿美公司在延布的現代化改造專案中採用了符合IEC 62443網路安全標準的西門子S7-1500 PLC。現有設施的營運商更傾向於使用模組化機架,因為熱插拔I/O卡可以將停機時間限制在週末切換。隨著沙烏地阿拉伯和阿拉伯聯合大公國煉油廠的總加工能力超過每日1000萬桶,軟體利潤率不斷擴大,而維修的持續勢頭也支撐著強勁的硬體需求。
對海灣合作理事會以外地區工業自動化硬體徵收進口關稅
在海灣合作理事會(GCC)成員國之外,PLC、電源和I/O卡的進口關稅為10%至25%,但根據《統一關稅法》,GCC成員國之間的貿易免關稅。埃及2024年頒布的第465號法令將可程式控制器的關稅提高至20%,立即增加了開羅和亞歷山大污水處理廠維修專案的預算。黎巴嫩和約旦維持著類似的關稅,以保護其仍在發展中的本地組裝產業,但由於這兩個國家都不生產半導體或高精度PCB,系統整合商仍然必須進口。不斷上漲的到貨成本迫使終端用戶推遲非必要的維修,導致訂單量減少,並使潛在的短期複合年成長率下降了0.4%。供應商正在免費捆綁編程軟體以抵消硬體價格飆升的影響,但利潤率仍在持續下降。
細分市場分析
2025年,硬體收入佔總收入的70.62%,而軟體的複合年成長率為6.71%,這表明營運商正在為現有資產添加分析和網路安全模組。 TAQA公司斥資2600萬美元部署的AI SCADA系統,將機器學習模型直接整合到西門子S7-1500 PLC中,從而減少了18%的化學品用量,並推遲了對新型逆滲透膜系統的資本投資。隨著資本支出(Capex)透過長期合約轉化為營運支出(OpEx),服務收入成長了5.5%。預計到2031年,中東可程式邏輯控制器(PLC)市場軟體元件的市場規模將達到3.2億美元,反映出訂閱式服務的日益普及。
邊緣分析解釋了軟體發展的強勁勢頭。根據羅克韋爾自動化的一份報告,在沙烏地阿拉伯和阿拉伯聯合大公國接受調查的製造商中,87% 的人在 PLC 層運行至少一個 AI 模型,以支援品質檢測和異常檢測。供應商正透過年度許可而非一次性硬體利潤來實現這一轉變,並在新設備出貨量趨於平穩的情況下,不斷提高合約總價值 (TCV)。
2025年,中型PLC在中東可程式邏輯控制器(PLC)市場佔據34.15%的佔有率,這主要得益於其在食品、飲料和水泥行業的傳統主導地位。同時,安全型PLC的複合年成長率(CAGR)達到7.26%,這主要得益於海灣合作理事會(GCC)監管機構強制要求新建和維修系統必須通過IEC 61511認證。卡達石化公司部署的SIL-3安全型PLC系統實現了99.9%的運轉率,並經第三方機構TUV檢驗。預計到2031年,中東安全型PLC市場規模將加倍,達到1.3億美元,主要得益於液化天然氣(LNG)、氫氣和高壓天然氣計畫的發展。
安全PLC價格昂貴,目前出貨量佔比仍不足10%,這意味著產品組合要發生根本性變化還有很長的路要走。供應商正在縮短前置作業時間,並透過捆綁韌體級OT安全功能來滿足整合網路安全認證的要求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 石油和天然氣行業數位化項目的擴展
- 現有設施自動化維修激增
- 海灣合作理事會願景主導製造中心的成長
- 能源領域的強制性功能安全
- 投資於該地區的氫能經濟試點計畫。
- 在海水淡化廠引進人工智慧預測性維護
- 市場限制因素
- 先進積體電路供應鏈的波動
- 本地系統整合商的技能儲備有限。
- 網路安全認證的高昂成本
- 大規模待開發區石化聯合裝置中分散式控制系統(DCS)應用趨勢
- 產業價值鏈分析
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按組件
- 硬體
- 軟體
- 服務
- 按PLC類型分類
- NanoPLC
- 微型PLC
- 中型PLC
- 大型PLC
- 安全PLC
- 以建築學為例
- 固定式/緊湊型PLC
- 模組化/機架式PLC
- 按最終用戶行業分類
- 石油和天然氣
- 化工/石油化工
- 能源公用事業
- 食品、菸草和飲料
- 車
- 製藥
- 其他終端用戶產業
- 國家
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 以色列
- 阿曼
- 卡達
- 科威特
- 巴林
- 其他中東國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Siemens AG
- ABB Ltd
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corporation
- Honeywell International Inc.
- Omron Corporation
- Emerson Electric Co.
- Hitachi Ltd.
- HIMA Paul Hildebrandt GmbH
- Yokogawa Electric Corporation
- Vista Automation LLC
- Control Tech Automation LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, Middle East programmable logic controller market size in 2026 is estimated at USD 803.93 million, growing from 2025 value of USD 760 million with 2031 projections showing USD 1.06 billion, growing at 5.78% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, and Services), PLC Type (Nano PLC, Micro PLC, and More), Architecture (Fixed/Compact PLC, and Modular/Rack-Mounted PLC), End-User Industry (Oil and Gas, Chemical and Petrochemical, and More), and Country (United Arab Emirates, Saudi Arabia, and More). The Market Forecasts are Provided in Terms of Value (USD).
Middle East Programmable Logic Controller Market Trends and Insights
Expanding Oil and Gas Digitalisation Projects
National oil firms are embedding PLC-centric digital twins to compress drilling cycles and defer new-well capital outlays. ADNOC's Neuron 5 platform lowered unplanned shutdowns by 50% and extended maintenance intervals by 20% across offshore and onshore assets. Saudi Aramco's RoboWell system fuses downhole telemetry with surface PLCs to optimize bit weight and rotary speed, trimming non-productive time by 30%. Qatar's North Field LNG expansion mandates IEC 61511 SIL-3-certified safety PLCs, creating a multi-year hardware and software pipeline. These deployments underscore why software revenue is outpacing hardware despite hardware's large base. As analytics shift to the edge, the Middle East programmable logic controller market benefits from recurring software updates layered onto existing racks.
Surge in Brownfield Automation Retrofits
Aging refineries and petrochemical plants commissioned in the 1980s and 1990s face tighter emissions standards, prompting modular PLC upgrades that cut energy use and add remote diagnostics. ADNOC Gas replaced pneumatic actuators with rack PLCs at Habshan-5, reducing energy consumption by 15%. Saudi Aramco's Yanbu modernization integrated Siemens S7-1500 PLCs compliant with IEC 62443 cyber-security guidelines. Brownfield operators prefer modular racks because hot-swappable I/O cards limit downtime to weekend cutovers. With installed capacity above 10 million barrels per day across Saudi and UAE refineries, retrofit momentum sustains steady hardware demand even as software margins grow.
Import Tariffs on Industrial Automation Hardware Outside GCC
Non-GCC states apply import duties ranging from 10% to 25% on PLCs, power supplies, and I/O cards, whereas intra-GCC trade remains tariff-free under the Unified Customs Law. Egyptian decree 465/2024 raised the duty on programmable controllers to 20%, immediately inflating project budgets for wastewater-treatment upgrades in Cairo and Alexandria. Lebanon and Jordan maintain similar levies to protect nascent local assembly, yet neither hosts semiconductor fabrication or high-precision PCB production, forcing integrators to import anyway. The higher landed cost compels end users to defer non-essential retrofits and reduces order sizes, trimming 0.4% from near-term CAGR potential. Vendors resort to bundling programming software at no charge to offset hardware sticker shock, but margin erosion persists.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Gulf Data-Center Construction
- Wastewater Reuse Mandates in Water-Stressed Economies
- Freight Congestion Through Red Sea and Strait of Hormuz
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware controlled 70.62% of 2025 revenue, yet software's 6.71% CAGR shows operators layering analytics and cyber-security modules onto installed assets. TAQA's USD 26 million AI SCADA rollout placed machine-learning models directly on Siemens S7-1500 PLCs, cutting chemical use 18% and deferring capital on new reverse-osmosis trains. Services revenue gained 5.5% as long-term agreements converted capex into opex. The Middle East programmable logic controller market size for software components is expected to reach USD 0.32 billion by 2031, reflecting rising subscription adoption.
Edge analytics explains software's momentum. Rockwell Automation reported that 87% of surveyed manufacturers in Saudi and the UAE run at least one AI model at the PLC layer, supporting quality inspection and anomaly detection. Vendors monetize this shift through annual licenses rather than one-time hardware margins, broadening total contract value even when new unit shipments plateau.
Medium PLCs held 34.15% of Middle East programmable logic controller market share in 2025 thanks to legacy dominance in food, beverage, and cement. Safety PLCs, however, post a 7.26% CAGR as GCC regulators enforce IEC 61511 certification for new and retrofitted systems. Qatar Petrochemical Company's SIL-3 deployment achieved 99.9% availability and third-party TUV validation. The Middle East programmable logic controller market size for safety units is forecast to double to USD 0.13 billion by 2031, fueled by LNG, hydrogen, and high-pressure gas projects.
Safety PLCs carry higher per-unit prices yet remain under 10% of shipments, indicating long runway for mix shift. Vendors bundle firmware-level OT security, shortening lead times and aligning with integrated cyber certification mandates.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By PLC Type
- Nano PLC
- Micro PLC
- Medium PLC
- Large PLC
- Safety PLC
- By Architecture
- Fixed/Compact PLC
- Modular/Rack-Mounted PLC
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Energy and Utilities
- Food, Tobacco, and Beverage
- Automotive
- Pharmaceutical
- Other End-User Industries
- By Country
- United Arab Emirates
- Saudi Arabia
- Israel
- Oman
- Qatar
- Kuwait
- Bahrain
- Rest of Middle East
List of Companies Covered in this Report:
- Siemens AG
- ABB Ltd
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corporation
- Honeywell International Inc.
- Omron Corporation
- Emerson Electric Co.
- Hitachi Ltd.
- HIMA Paul Hildebrandt GmbH
- Yokogawa Electric Corporation
- Vista Automation LLC
- Control Tech Automation LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding Oil and Gas Digitalisation Projects
- 4.2.2 Surge in Brownfield Automation Retrofits
- 4.2.3 Growing GCC Vision-Driven Manufacturing Hubs
- 4.2.4 Mandatory Functional-Safety Compliance in Energy Sector
- 4.2.5 Hydrogen Economy Pilot Investments in the Region
- 4.2.6 AI-Enabled Predictive Maintenance Adoption in Desalination Plants
- 4.3 Market Restraints
- 4.3.1 Supply Chain Volatility for Advanced ICs
- 4.3.2 Limited Local System-Integrator Skill Pool
- 4.3.3 High Cyber-Security Certification Costs
- 4.3.4 Preference for DCS in Large Greenfield Petrochemical Complexes
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Intensity of Competitive Rivalry
- 4.5.5 Threat of Substitutes
- 4.6 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By PLC Type
- 5.2.1 Nano PLC
- 5.2.2 Micro PLC
- 5.2.3 Medium PLC
- 5.2.4 Large PLC
- 5.2.5 Safety PLC
- 5.3 By Architecture
- 5.3.1 Fixed/Compact PLC
- 5.3.2 Modular/Rack-Mounted PLC
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Energy and Utilities
- 5.4.4 Food, Tobacco, and Beverage
- 5.4.5 Automotive
- 5.4.6 Pharmaceutical
- 5.4.7 Other End-User Industries
- 5.5 By Country
- 5.5.1 United Arab Emirates
- 5.5.2 Saudi Arabia
- 5.5.3 Israel
- 5.5.4 Oman
- 5.5.5 Qatar
- 5.5.6 Kuwait
- 5.5.7 Bahrain
- 5.5.8 Rest of Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Siemens AG
- 6.4.2 ABB Ltd
- 6.4.3 Schneider Electric SE
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Mitsubishi Electric Corporation
- 6.4.6 Honeywell International Inc.
- 6.4.7 Omron Corporation
- 6.4.8 Emerson Electric Co.
- 6.4.9 Hitachi Ltd.
- 6.4.10 HIMA Paul Hildebrandt GmbH
- 6.4.11 Yokogawa Electric Corporation
- 6.4.12 Vista Automation LLC
- 6.4.13 Control Tech Automation LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 亞太地區可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 嵌入式運動控制器市場規模、佔有率和成長分析:按控制器類型、應用、通訊介面、最終用戶、安裝方式和地區分類-2026-2033年產業預測
 虛擬PLC與軟PLC市場分析及預測(至2035年):類型、產品、服務、技術、組件、應用、部署、最終用戶、功能、解決方案歐洲可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 嵌入式控制器市場報告:趨勢、預測與競爭分析(至2035年)可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 可程式邏輯控制器(PLC)市場-2026-2032年全球市場預測
 2026-2030年全球可程式邏輯控制器(PLC)市場
 可程式材料市場預測至2034年-按材料類型、刺激類型、功能、應用、形態和地區分類的全球分析可程式邏輯控制器 (PLC) 市場預測至 2034 年——按類型、組件、行業、應用、最終用戶和地區分類的全球分析