


 |
市場調查報告書
商品編碼
2120391
可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Programmable Logic Controller (PLC) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
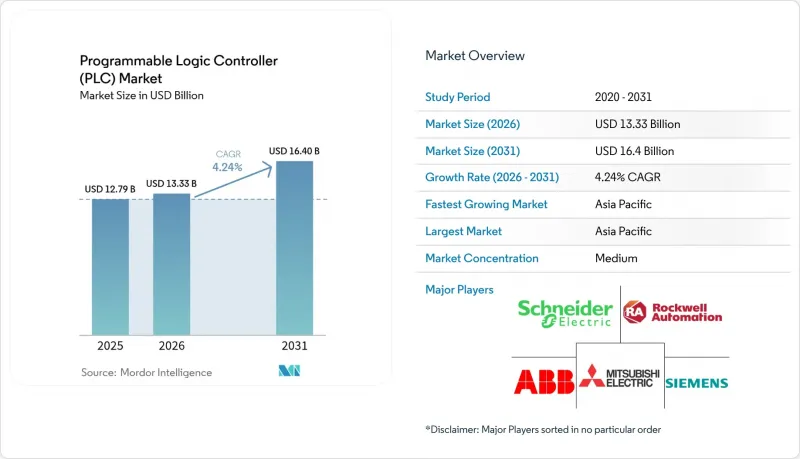
根據 Mordor Intelligence 預測,可程式邏輯控制器 (PLC) 的市場規模預計將從 2025 年的 127.9 億美元成長到 2026 年的 133.3 億美元,到 2031 年將達到 164 億美元,2026 年至 2031 年的複合年成長率為 4.24%。
本報告按產品類型(緊湊型PLC、模組化PLC、分散式PLC、軟體PLC及其他產品)、組件(硬體和軟體、服務)、產品尺寸(奈米PLC、微型PLC、小型PLC、中型PLC和大型PLC)、終端用戶產業(汽車、食品飲料、化學和石化及其他產業)以及地區進行細分。市場預測以美元計價。
全球可程式邏輯控制器 (PLC) 市場趨勢與洞察
加速製造業採用工業4.0
為了提高生產效率,工廠正日益數位轉型,PLC(可程式邏輯控制器)作為本地資料中心,連接機器和企業軟體。德國聯邦經濟事務部報告稱,工業4.0的採用率將從2023年的65%激增至2024年的78%,這為持續的控制器升級提供了支持。中國和印度的補貼進一步降低了小規模生產商的自動化成本。同時,奧迪的虛擬PLC實施方案展示了向軟體中心控制的轉變,試運行時間縮短了23%,並提高了即時最佳化能力。隨著ISO 9001可追溯性要求的加強,製造商被要求用支援精細資料登錄和無縫ERP整合的現代化控制器取代傳統硬體。在離散製造和流程製造業,對具有內建邊緣分析功能的PLC的需求日益成長,這些PLC能夠在不損害網路安全協議的前提下縮短回饋迴路。
透過工業物聯網和雲端運算的整合實現預測性維護。
邊緣運算PLC可在本地分析振動、溫度和功率測量數據,並將精選資訊傳送至雲端控制面板,用於整體設備健康監控。Schneider Electric的EcoStruxure平台是混合模式的典範,它將本地邏輯與雲端演算法融合,實現持續最佳化。 5G連接和數位孿生軟體支援分散式PLC節點的即時協調,從而實現自主過程調整,減少意外停機時間。已實施預測性維護的公共產業和金屬加工廠報告稱,其整體設備效率(OEE)顯著提升,備件庫存減少,證明了這項投資的合理性,儘管網路安全問題依然存在。
小規模製造商的初始投資成本較高
平均專案成本在 1.5 萬美元到 5 萬美元之間,這仍然是許多微企業面臨的一大障礙,尤其是在考慮到整合、培訓和停機成本時。有限的現金儲備往往導致經驗不足的買家過度配置,選擇「一刀切」的解決方案來降低風險。雖然資金籌措方案和供應商租賃可以減輕負擔,但它們無法徹底消除保守的投資文化。基於訂閱的虛擬 PLC 承諾降低部署成本,但由於該服務仍處於早期階段,其普及程度並不均衡,尤其是在網路連線不穩定的地區。
細分市場分析
預計到2025年,模組化配置將佔據可程式邏輯控制器(PLC)市場41.56%的佔有率,其優勢在於能夠根據工廠升級需求擴展I/O和運算能力。這種架構允許工程師在不更換整個系統(例如堆高機)的情況下添加運動控制、安全或人工智慧模組,從而支援汽車和家用電子電器的多品種生產線。雖然軟PLC目前仍處於小眾市場,但隨著虛擬機器管理程式提供確定性效能以及供應商整合增強型內核,其正以7.22%的複合年成長率快速發展。
在離散製造業和流程製造業,核心需求在於能夠進行邊緣分析以在機器層面偵測異常的控制器。雖然緊湊型PLC在獨立機器中仍然具有吸引力,但分散式PLC正被大規模煉油廠和發電廠所採用,這些工廠更傾向於容錯性強且地理位置分散的節點。隨著基於TSN的OPC-UA技術的成熟,使用者期望實現無縫互通性,這將進一步降低硬體的同質化程度,並將差異化重點轉移到軟體工具鍊和支援生態系統上。
預計到2025年,可程式邏輯控制器(PLC)的硬體和軟體市場總佔有率將達到84.67%,但隨著用戶從資本支出(CapEx)模式轉向營運支出(OpEx)模式,業務收益正以7.76%的複合年成長率成長。工業物聯網(IIoT)連接各層整合複雜性的不斷增加,推動了對供應商主導的諮詢和應用工程服務的需求。
預測性維護方案融合了遠端監控、韌體管理和人工智慧診斷功能,從而促成了長期合約的簽訂。供應商也在新興經濟體拓展培訓機構,以彌補技能差距並提升品牌知名度。基於雲端的支援入口網站降低了差旅成本,而擴增實境(AR) 指導則縮短了現場維修週期,進一步提升了以硬體為中心的更換專案的服務需求。
區域分析
亞太地區製造業的復甦正在推動規模和速度的雙重成長,預計到2025年將佔全球銷售額的35.10%,到2031年將維持6.12%的複合年成長率。在中國,疫情後的獎勵策略津貼了汽車和電子產業控制器升級。同時,印度工業走廊的建設正在加速PLC的初期部署。日本的「品質4.0」舉措使得電子元件貼片機所需的奈秒級確定性回應控制器需求旺盛。在韓國,造船廠和半導體工廠正在指定使用冗餘PLC叢集,以確保關鍵任務的運作,從而支援高利潤訂單。
歐洲對永續性的承諾正促使控制器採購更加重視能源管理和符合循環經濟原則。歐盟2024年《網路安全韌性法案》強制要求原始設備製造商(OEM)獲得「安全設計」認證,從而增加了對內建加密通訊和異常檢測功能的產品的需求。德國汽車製造商正在進行基於軟體定義PLC沙箱的試點項目,而法國和義大利則正在利用故障安全邏輯實現航太複合材料生產線的自動化。
北美用戶優先考慮安全的供應鏈和國產半導體的應用。 《基礎設施投資與就業法案》正在資助變電站維修,其中包括採用最先進的控制器來實現負載平衡和故障隔離。墨西哥近岸生產的快速擴張推動了汽車線束產量的成長,因此需要快速部署小型PLC。加拿大採礦和木材行業青睞能夠應對寬溫範圍的堅固耐用的設備。整體而言,各地區的採購負責人在競標過程中都非常重視網路安全可靠性和國內維修支援。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速製造業採用工業4.0
- 中小企業對緊湊型自動化設備的需求日益成長
- 透過工業物聯網和雲端運算的整合實現預測性維護。
- 向軟體定義PLC工作站遷移
- 採用開放式工業協定(TSN 上的 OPC-UA)
- 網路安全引發的國內採購義務
- 市場限制因素
- 對於小規模製造商而言,初始投資成本相對較高。
- 網路連線型PLC面臨的網路安全威脅日益加劇
- 工業用電腦和軟體PLC取代傳統PLC的風險。
- 由於半導體供應波動,前置作業時間越來越長。
- 產業價值鏈分析
- 宏觀經濟因素的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 小型PLC
- 模組化PLC
- 分散式PLC
- 軟PLC
- 其他產品
- 按組件
- 硬體和軟體
- 服務
- 安裝與整合
- 培訓和支持
- 維護
- 產品尺寸
- NanoPLC
- 微型PLC
- 小型PLC
- 中型PLC
- 大型PLC
- 按最終用戶行業分類
- 車
- 食品/飲料
- 化工/石油化工
- 石油和天然氣
- 能源公用事業
- 供水和廢水處理
- 製藥
- 紙漿和造紙
- 金屬和採礦
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 東南亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Siemens AG
- Rockwell Automation Inc.
- Schneider Electric SE
- Mitsubishi Electric Corporation
- ABB Ltd.
- Omron Corporation
- Emerson Electric Co.
- Honeywell International Inc.
- Beckhoff Automation GmbH & Co. KG
- Delta Electronics Inc.
- Bosch Rexroth AG
- Panasonic Holdings Corporation
- Fuji Electric Co. Ltd.
- Hitachi Ltd.
- IDEC Corporation
- Keyence Corporation
- Toshiba Corporation
- General Electric Company
- Parker Hannifin Corporation
- Eaton Corporation plc
- Yokogawa Electric Corporation
- Inovance Technology Co. Ltd.
- Hollysys Automation Technologies Ltd.
- WAGO Kontakttechnik GmbH & Co. KG
- B&R Industrial Automation GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the programmable logic controller market size is expected to grow from USD 12.79 billion in 2025 to USD 13.33 billion in 2026 and is forecast to reach USD 16.4 billion by 2031 at 4.24% CAGR over 2026-2031.
This report is Segmented by Product Type (Compact PLC, Modular PLC, Distributed PLC, Soft PLC, Other Products), Component (Hardware and Software, Services), Product Size (Nano PLC, Micro PLC, Small PLC, Medium PLC, Large PLC), End-User Industry (Automotive, Food and Beverage, Chemical and Petrochemical, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Programmable Logic Controller (PLC) Market Trends and Insights
Accelerated Industry 4.0 Adoption in Manufacturing
Factories digitalize to boost productivity, and PLCs act as the local data hubs that connect machines with enterprise software. The German Federal Ministry for Economic Affairs reported a jump to 78% Industry 4.0 adoption in 2024, up from 65% in 2023, underscoring the momentum behind controller upgrades. Subsidies in China and India further lower the cost of automation for small producers, while Audi's virtual PLC rollout cut commissioning time by 23% and improved real-time optimization, validating the transition toward software-centric control. Rising ISO 9001 traceability requirements obligate manufacturers to replace legacy hardware with modern controllers that support granular data logging and seamless ERP integration. Across discrete and process industries, demand concentrates on PLCs with built-in edge analytics that shorten feedback loops without compromising cybersecurity protocols.
IIoT and Cloud Integration Enabling Predictive Maintenance
Edge-ready PLCs analyze vibration, temperature, and power metrics locally, sending only refined insights to cloud dashboards for fleetwide health monitoring. Schneider Electric's EcoStruxure platform exemplifies the hybrid model, fusing on-premise logic with cloud algorithms for continuous optimization. 5G connectivity and digital-twin software now coordinate distributed PLC nodes in real time, supporting autonomous process adjustments that curb unplanned downtime. Utilities and metals plants that deploy predictive maintenance report sharper OEE gains and lower spare-parts inventories, validating the investment case despite residual cybersecurity concerns.
High Up-Front Capital Cost for Small Manufacturers
Average project outlays of USD 15,000-50,000 still deter many micro-scale firms, especially when integration, training, and downtime are counted. Limited cash reserves often lead to over-specification because novice buyers adopt a one-size-fits-all mindset to mitigate perceived risk. Financing schemes and vendor leasing ease pressure, but cannot fully offset conservative investment cultures. Subscription-based virtual PLCs promise lower entry points, yet nascent offerings leave adoption uneven, particularly in regions where internet reliability lags.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Compact Automation Among SMEs
- Shift to Software-Defined PLC Workstations
- Escalating Cybersecurity Threats to Connected PLCs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Modular configurations dominated with 41.56% programmable logic controller market share in 2025, reflecting their ability to expand I/O and compute power alongside plant upgrades. The architecture lets engineers add motion, safety, or AI cards without forklift replacements, supporting mixed-model lines in automotive and consumer electronics. Soft PLCs, though still niche, are advancing at a 7.22% CAGR as hypervisors deliver deterministic performance and vendors embed hardened kernels.
Across both discrete and process industries, demand centers on controllers that host edge analytics for anomaly detection at the machine level. Compact PLCs retain appeal for stand-alone machines, while distributed PLCs serve large refineries and power stations that favor fault-tolerant, geographically separated nodes. As OPC-UA over TSN matures, users expect seamless interoperability, further commoditizing hardware and shifting differentiation to software toolchains and support ecosystems.
Hardware and software together held 84.67% of the programmable logic controller market size in 2025, yet service revenue is expanding at 7.76% CAGR as users pivot from CapEx to OpEx models. Integration complexity climbs with each layer of IIoT connectivity, elevating demand for vendor-led consulting and application engineering.
Predictive maintenance packages bundle remote monitoring, firmware management, and AI-driven diagnostics, creating sticky multi-year contracts. Vendors also ramp training academies in emerging economies to close the skills gap and lock in brand familiarity. Cloud-hosted support portals lower travel costs, while augmented-reality guides shorten onsite repair cycles, reinforcing service pull even in hardware-centric replacement projects.
Complete Report Scope:
- By Product Type
- Compact PLC
- Modular PLC
- Distributed PLC
- Soft PLC
- Other Products
- By Component
- Hardware and Software
- Services
- Installation and Integration
- Training and Support
- Maintenance
- By Product Size
- Nano PLC
- Micro PLC
- Small PLC
- Medium PLC
- Large PLC
- By End-user Industry
- Automotive
- Food and Beverage
- Chemical and Petrochemical
- Oil and Gas
- Energy and Utilities
- Water and Wastewater Treatment
- Pharmaceutical
- Pulp and Paper
- Metals and Mining
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific's manufacturing resurgence underpins both scale and speed, with 35.10% revenue in 2025 and 6.12% CAGR to 2031. China's post-pandemic stimulus subsidized controller upgrades in automotive and electronics, while India's industrial corridor builds encourage first-time PLC rollouts. Japan's Quality-4.0 initiatives keep demand high for deterministic, nano-second-level controllers used in electronics placement machines. South Korean shipyards and fabs specify redundant PLC clusters for mission-critical uptime, anchoring high-margin orders.
Europe's sustainability push frames controller purchases around energy management and circular-economy compliance. The EU Cyber Resilience Act of 2024 obliges OEMs to certify security-by-design, boosting demand for products with encrypted communications and built-in anomaly detection. German automakers pilot software-defined PLC sandboxes, while France and Italy automate aerospace composites lines with fail-safe logic.
North American users prioritize secure supply chains and domestic semiconductor content. The Infrastructure Investment and Jobs Act funds substation refurbishments that incorporate modern controllers for load-balancing and fault isolation. Mexico's nearshore boom ramps automotive harness production, requiring swift deployment of compact PLCs. Canada's mining and lumber sectors favor rugged gear with extended temperature ratings. Overall, regional buyers weigh cybersecurity credentials and on-shore repair support heavily in tender scoring.
- Siemens AG
- Rockwell Automation Inc.
- Schneider Electric SE
- Mitsubishi Electric Corporation
- ABB Ltd.
- Omron Corporation
- Emerson Electric Co.
- Honeywell International Inc.
- Beckhoff Automation GmbH & Co. KG
- Delta Electronics Inc.
- Bosch Rexroth AG
- Panasonic Holdings Corporation
- Fuji Electric Co. Ltd.
- Hitachi Ltd.
- IDEC Corporation
- Keyence Corporation
- Toshiba Corporation
- General Electric Company
- Parker Hannifin Corporation
- Eaton Corporation plc
- Yokogawa Electric Corporation
- Inovance Technology Co. Ltd.
- Hollysys Automation Technologies Ltd.
- WAGO Kontakttechnik GmbH & Co. KG
- B&R Industrial Automation GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated Industry-4.0 adoption in manufacturing
- 4.2.2 Growing demand for compact automation among SMEs
- 4.2.3 IIoT and cloud integration enabling predictive maintenance
- 4.2.4 Shift to software-defined PLC workstations
- 4.2.5 Adoption of open industrial protocols (OPC-UA over TSN)
- 4.2.6 Cybersecurity-driven domestic sourcing mandates
- 4.3 Market Restraints
- 4.3.1 High up-front capital cost for small manufacturers
- 4.3.2 Escalating cybersecurity threats to connected PLCs
- 4.3.3 Substitution risk from industrial PCs and soft-PLCs
- 4.3.4 Semiconductor supply volatility inflating lead times
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Compact PLC
- 5.1.2 Modular PLC
- 5.1.3 Distributed PLC
- 5.1.4 Soft PLC
- 5.1.5 Other Products
- 5.2 By Component
- 5.2.1 Hardware and Software
- 5.2.2 Services
- 5.2.2.1 Installation and Integration
- 5.2.2.2 Training and Support
- 5.2.2.3 Maintenance
- 5.3 By Product Size
- 5.3.1 Nano PLC
- 5.3.2 Micro PLC
- 5.3.3 Small PLC
- 5.3.4 Medium PLC
- 5.3.5 Large PLC
- 5.4 By End-user Industry
- 5.4.1 Automotive
- 5.4.2 Food and Beverage
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Oil and Gas
- 5.4.5 Energy and Utilities
- 5.4.6 Water and Wastewater Treatment
- 5.4.7 Pharmaceutical
- 5.4.8 Pulp and Paper
- 5.4.9 Metals and Mining
- 5.4.10 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 South-East Asia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core segments, Financials as available, Strategic information, Market rank/share for key companies, Products and Services, and Recent developments)
- 6.4.1 Siemens AG
- 6.4.2 Rockwell Automation Inc.
- 6.4.3 Schneider Electric SE
- 6.4.4 Mitsubishi Electric Corporation
- 6.4.5 ABB Ltd.
- 6.4.6 Omron Corporation
- 6.4.7 Emerson Electric Co.
- 6.4.8 Honeywell International Inc.
- 6.4.9 Beckhoff Automation GmbH & Co. KG
- 6.4.10 Delta Electronics Inc.
- 6.4.11 Bosch Rexroth AG
- 6.4.12 Panasonic Holdings Corporation
- 6.4.13 Fuji Electric Co. Ltd.
- 6.4.14 Hitachi Ltd.
- 6.4.15 IDEC Corporation
- 6.4.16 Keyence Corporation
- 6.4.17 Toshiba Corporation
- 6.4.18 General Electric Company
- 6.4.19 Parker Hannifin Corporation
- 6.4.20 Eaton Corporation plc
- 6.4.21 Yokogawa Electric Corporation
- 6.4.22 Inovance Technology Co. Ltd.
- 6.4.23 Hollysys Automation Technologies Ltd.
- 6.4.24 WAGO Kontakttechnik GmbH & Co. KG
- 6.4.25 B&R Industrial Automation GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 亞太地區可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)中東可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 嵌入式運動控制器市場規模、佔有率和成長分析:按控制器類型、應用、通訊介面、最終用戶、安裝方式和地區分類-2026-2033年產業預測
 虛擬PLC與軟PLC市場分析及預測(至2035年):類型、產品、服務、技術、組件、應用、部署、最終用戶、功能、解決方案歐洲可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 嵌入式控制器市場報告:趨勢、預測與競爭分析(至2035年)
 可程式邏輯控制器(PLC)市場-2026-2032年全球市場預測
 2026-2030年全球可程式邏輯控制器(PLC)市場
 可程式材料市場預測至2034年-按材料類型、刺激類型、功能、應用、形態和地區分類的全球分析可程式邏輯控制器 (PLC) 市場預測至 2034 年——按類型、組件、行業、應用、最終用戶和地區分類的全球分析