


 |
市場調查報告書
商品編碼
2123030
歐洲可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Europe Programmable Logic Controller (PLC) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,歐洲可程式邏輯控制器 (PLC) 市場規模預計將在 2026 年達到 37.5 億美元,到 2031 年將擴大到 43.6 億美元,預測期內複合年成長率為 3.06%。
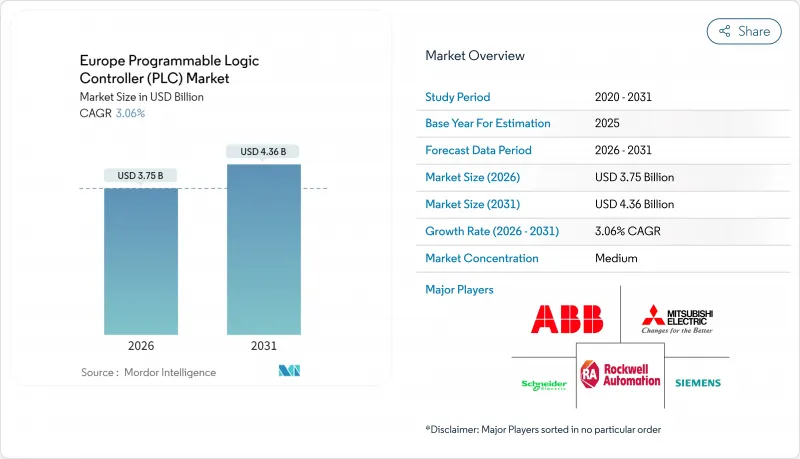
本報告按類型(硬體、軟體(大型PLC、中型PLC、其他)、服務)、架構(模組化PLC、機架式PLC、緊湊型PLC、軟PLC、安全PLC)、應用(運動控制、製程控制、其他)、終端用戶產業(汽車、食品、菸草飲料、其他)和地區進行細分。市場預測以美元(USD)為單位。
歐洲可程式邏輯控制器 (PLC) 市場的趨勢與洞察
加快工業4.0和智慧工廠計劃的實施
德國、法國和義大利的領先製造商正從先導計畫轉向2025年的全面部署。在德國,擁有250名以上員工的工廠中,有68%的工廠報告稱至少進行了一項維修,將傳統PLC連接到基於雲端的MES平台。法國的「未來工業」(Industrie du Futur)和義大利的「工業轉型4.0」(Transizione 4.0)等國家獎勵計畫為連網機械提供稅額扣抵和加速折舊,但前提是PLC必須提供OPC UA伺服器以實現互通性。歐盟「地平線歐洲」(Horizon Europe)計畫已撥款9,500萬歐元(1.112億美元)用於一項由人工智慧驅動的預測性維護試點項目,該計畫將於2024年至2025年期間實施,旨在加速控制器背板上邊緣分析模組的普及。西班牙面向汽車產業的PERTE計畫正在為需要SIL 3安全等級PLC的電動車電池生產線提供自動化補貼。這些努力加在一起,進一步推進了數位化進程,鞏固了 PLC 在工廠環境中作為主資料節點的地位。
製造業自動化系統應用範圍的擴大
預計到2025年,歐盟汽車產量將達到1,280萬輛,其中電動車和插電式混合動力車將佔總產量的28%。與內燃機汽車生產線相比,每款電動車型所需的PLC控制站數量將增加15%至20%。隨著包括諾和諾德在內的製藥公司擴大生物製藥生產,製藥業的產能將成長11%,同時,符合FDA 21 CFR Part 11和歐盟GMP Annex 11標準的控制器級電子記錄功能也已投入使用。食品加工企業透過將繼電器邏輯升級為PLC並每秒記錄HACCP參數,滿足將於2025年1月生效的EFSA衛生要求。萊茵-魯爾地區的化工企業計劃在2025年投資8.9億歐元,以符合NAMUR NE 148標準的模組化PLC取代其DCS系統,加速工程技術的再利用。荷蘭和比利時的供水事業已安裝了 2300 個控制器,用於即時監測合流制污水溢流 (CSO),以遵守新的污水指令。
來自工業用電腦和邊緣控制器的競爭日益激烈。
2025年,歐洲工廠用工業用電腦的出貨量成長了18%。這主要歸功於提案華科技、倍福和康創等公司推出的x86硬體,這些硬體將PLC邏輯、人機介面(HMI)和分析功能整合到單一機殼中。採用IEEE 802.1Qbv技術的時序敏感網路能夠在商用交換器上實現亞毫秒的確定性,從而削弱了傳統機架式系統在週期時間上的優勢。倍福的TwinCAT軟體PLC在離散式自動化領域佔據了9%的市場佔有率,吸引了那些更傾向於使用C++而非梯形圖邏輯的工程師。然而,Windows和Linux的季度修補更新使得受Annex 11法規約束的製藥廠的檢驗變得更加複雜,這也凸顯了硬體PLC「以簡易性保障安全」的優勢。
細分市場分析
到2025年,中型控制器將佔據歐洲可程式邏輯控制器(PLC)市場佔有率的34.83%,成為處理50至500個I/O點的生產線的基礎。在歐洲可程式邏輯控制器(PLC)市場中,奈米級產品細分市場正以4.46%的複合年成長率快速成長,這主要得益於機器製造商將郵票大小的控制器整合到「即插即用」單元中。製造商重視奈米裝置,因為它們在能源效率標籤審核中功耗僅為3-8瓦,且DIN導軌寬度小於25毫米,從而減小了機櫃深度。雖然大型PLC在煉油和紙漿行業仍然是標準配置,但它們正逐漸被將邏輯分類為更小節點的分散式架構所取代。
西門子S7-1200 Nano將於2025年發布,無需單獨電源即可直接安裝在DIN導軌上,這對於面臨貨櫃關稅壓力的出口OEM廠商來說極具吸引力。羅克韋爾自動化Micro800系列將2.4吋人機介面(HMI)整合到機殼中,降低了洗車和洗衣設備的組件成本。 ABB AC500-S將SIL 3級安全功能整合到90毫米寬的機殼中,控制面板內部佈線減少了35%。隨著PackML相容模組在製藥和消費品製造工廠的日益普及,預計到2028年後,奈米PLC的成長速度將持續超過歐洲可程式邏輯控制器(PLC)市場的整體成長速度。
預計到2025年,模組化配置將在歐洲可程式邏輯控制器(PLC)市場佔據41.27%的佔有率。這主要是由於化學和製藥業的使用者需要根據Annex 11審核標準來實現I/O的熱插拔。緊湊型一體化機殼在泵站和暖通空調(HVAC)空氣處理機組中仍然很受歡迎,但在預期未來會進行擴展的應用領域,其市場佔有率正在下降。機架式配置在現有煉油廠(棕地)中繼續得到應用,因為可以重複利用19吋機櫃,從而將機械設計重新設計的時間縮短40%。
同時,軟PLC的採用率正以4.51%的複合年成長率成長,企業在工業用電腦上運行控制邏輯,並將SCADA和確定性任務整合到單一底盤中。 CODESYS運行時許可證的價格在350歐元至650歐元(410美元至760歐元)之間,而同類硬體產品的價格在2800歐元至4200歐元(3280美元至4914歐元)之間。如果能夠透過TSN保持週期時間,這種價格差異將極具吸引力。施耐德電機的Modicon M580 ePAC整合了標準邏輯和安全邏輯,預計到2025年將佔據歐洲安全PLC市場18%的佔有率。最新的IEC 61508修訂版強制要求安全啟動和加密韌體,這將使每個控制器增加800歐元至1400歐元的成本,但可確保長期的網路安全韌性。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
- 市場促進因素
- 加快工業4.0和智慧工廠計劃的實施
- 製造業自動化系統應用範圍的擴大
- 節能生產線的需求日益成長
- 汽車業加大對電動車生產線的投資
- 歐盟資助的數位創新中心促進中小企業的PLC整合。
- 從 2024 年起,《歐洲晶片法》提供的獎勵將促進 PLC 晶片製造回歸日本。
- 市場限制因素
- 來自工業用電腦和邊緣控制器的競爭日益激烈。
- 舊有系統升級需要大量的初始資金投入。
- 歐盟NIS2指令下的網路安全合規負擔
- 東歐地區缺乏具備IEC 61131-3程式設計技術純熟勞工
第5章 市場規模與成長預測
- 按類型
- 硬體和軟體
- 大型PLC
- 中型PLC
- 小型PLC
- NanoPLC
- 其他硬體類型
- 服務
- 硬體和軟體
- 以建築學為例
- 模組化PLC
- 機架式PLC
- 小型PLC
- 軟PLC
- 安全PLC
- 透過使用
- 運動控制
- 過程控制
- 連續式控制
- 安全
- 數據處理和通訊
- 按最終用戶行業分類
- 車
- 食品、菸草和飲料
- 化工/石油化工
- 能源與公共產業
- 製藥
- 石油和天然氣
- 金屬和採礦
- 水和污水處理
- 其他
- 按地區
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Siemens AG
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corporation
- ABB Ltd.
- Honeywell International Inc.
- Omron Corporation
- Emerson Electric Co.
- Panasonic Corporation
- Robert Bosch GmbH(Bosch Rexroth)
- Hitachi Ltd
- General Electric Co.
- Beckhoff Automation GmbH
- B and R Industrial Automation GmbH
- Phoenix Contact GmbH
- Festo SE and Co. KG
- WAGO Kontakttechnik GmbH
- Eaton Corporation plc
- IDEC Corporation
- Advantech Co. Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe programmable logic controller (PLC) market size reached USD 3.75 billion in 2026 and is projected to climb to USD 4.36 billion by 2031, translating to a 3.06% CAGR over the forecast period.
This report is Segmented by Type (Hardware and Software (Large PLC, Medium PLC, and More), and Service), Architecture (Modular PLC, Rack PLC, Compact PLC, Soft PLC, and Safety PLC), Application (Motion Control, Process Control, and More), End-User Industry (Automotive, Food Tobacco and Beverage, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe Programmable Logic Controller (PLC) Market Trends and Insights
Accelerating Industry 4.0 Adoption and Smart Factory Initiatives
Large manufacturers across Germany, France and Italy moved from pilot projects to scaled rollouts in 2025, with 68% of German plants above 250 employees reporting at least one retrofit that connects legacy PLCs to cloud MES platforms. National incentive schemes such as France's Industrie du Futur and Italy's Transizione 4.0 provide tax credits or hyper-depreciation on connected machinery, but only if PLCs expose OPC UA servers for interoperability. Funding from Horizon Europe directs EUR 95 million (USD 111.2 million) to AI-driven predictive maintenance pilots in 2024-2025, accelerating edge-analytics modules on controller backplanes. Spain's automotive PERTE program earmarks automation subsidies for EV battery lines that need SIL 3 safety PLCs. Collectively, these actions deepen digitalization and cement PLCs as master data nodes on the plant floor.
Increased Adoption of Automation Systems in Manufacturing
EU vehicle output hit 12.8 million units in 2025 with EV and PHEV models accounting for 28%; each electrified variant needs 15-20% more PLC-controlled stations than an internal-combustion build-out. Pharmaceutical capacity expanded 11% as Novo Nordisk and peers ramped biologics production, installing controller-level electronic-record functionality that satisfies FDA 21 CFR Part 11 and EU GMP Annex 11. Food processors upgraded relay logic to PLCs that log HACCP parameters every second, meeting EFSA hygiene mandates effective January 2025. Chemical firms in the Rhine-Ruhr invested EUR 890 million in 2025 to replace DCS islands with modular PLCs aligned to NAMUR NE 148 for faster engineering reuse. Water utilities in the Netherlands and Belgium installed 2,300 controllers for real-time CSO monitoring, addressing new wastewater directives.
Intensifying Competition from Industrial PCs and Edge Controllers
Shipments of industrial PCs into European factories grew 18% in 2025 as Advantech, Beckhoff and Kontron pitched x86 hardware that collapses PLC logic, HMI and analytics onto one box. Time-sensitive networking under IEEE 802.1Qbv now delivers sub-millisecond determinism on commercial switches, eroding the cycle-time advantage of traditional racks. Beckhoff's TwinCAT software PLC reached 9% share in discrete automation, buoyed by engineers who prefer C++ over ladder logic. Yet Windows or Linux patches every quarter complicate validation in pharma sites governed by Annex 11, giving hardware PLCs security-through-simplicity leverage.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Energy-Efficient Production Lines
- Rising Investments in Automotive Electric-Vehicle Production Lines
- High Initial Capital Expenditure for Upgrading Legacy Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Medium controllers dominated Europe Programmable Logic Controller (PLC) Market share with 34.83% in 2025, anchoring production lines that handle 50-500 I/O points. The Europe Programmable Logic Controller (PLC) Market size for nano variants is expanding fastest at a 4.46% CAGR, driven by machine builders embedding postage-stamp controllers inside plug-and-produce cells. Manufacturers appreciate nano devices for their 3-8 watt draw during energy-label audits and for DIN-rail widths under 25 millimetres that cut cabinet depth. Large PLCs remain staples in refining and pulp but slowly cede ground to distributed architectures that split logic across smaller nodes.
Siemens' S7-1200 Nano, launched in 2025, bolts directly to DIN rail without a separate power supply, appealing to export OEMs squeezed by container tariffs. Rockwell's Micro800 line merges a 2.4-inch HMI into the housing, shaving bill-of-materials costs on carwash and laundry equipment. ABB's AC500-S integrates SIL 3 safety in 90 mm width and slashes control-cabinet wiring 35%. Expect nano growth to keep outpacing the overall Europe Programmable Logic Controller (PLC) Market beyond 2028 as PackML-aligned modules proliferate in pharma and consumer-goods plants.
Modular configurations accounted for 41.27% of the Europe Programmable Logic Controller (PLC) Market in 2025 because chemical and pharmaceutical users must hot-swap I/O under Annex 11 audit scrutiny. Compact all-in-one boxes stay popular for lift stations and HVAC air handlers but lose share where future expansion is likely. Rack-mount variants persist in brownfield refineries where 19-inch cabinets can be reused, saving 40% mechanical redesign time.
Soft PLC deployments, meanwhile, are rising at a 4.51% CAGR as firms run control logic on industrial PCs to unify SCADA and deterministic tasks in one chassis. CODESYS runtime licenses cost EUR 350-650 (USD 410-760) versus EUR 2,800-4,200 (USD 3,280-4,914) for hardware equivalents, a compelling difference when cycle times can be maintained through TSN. Schneider's Modicon M580 ePAC, combining standard and safety logic, secured 18% of the European safety PLC segment in 2025. The newest IEC 61508 revision now mandates secure boot and encrypted firmware, adding EUR 800-1,400 per controller but offering long-term cyber resilience.
Complete Report Scope:
- By Type
- Hardware and Software
- Large PLC
- Medium PLC
- Small PLC
- Nano PLC
- Other Hardware Types
- Service
- Hardware and Software
- By Architecture
- Modular PLC
- Rack PLC
- Compact PLC
- Soft PLC
- Safety PLC
- By Application
- Motion Control
- Process Control
- Sequential Control
- Safety
- Data Handling and Communications
- By End-User Industry
- Automotive
- Food, Tobacco and Beverage
- Chemical and Petrochemical
- Energy and Utilities
- Pharmaceutical
- Oil and Gas
- Metals and Mining
- Water and Wastewater
- Other End-User Industries
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Siemens AG
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corporation
- ABB Ltd.
- Honeywell International Inc.
- Omron Corporation
- Emerson Electric Co.
- Panasonic Corporation
- Robert Bosch GmbH (Bosch Rexroth)
- Hitachi Ltd
- General Electric Co.
- Beckhoff Automation GmbH
- B and R Industrial Automation GmbH
- Phoenix Contact GmbH
- Festo SE and Co. KG
- WAGO Kontakttechnik GmbH
- Eaton Corporation plc
- IDEC Corporation
- Advantech Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value-Chain Analysis
- 4.3 Impact of Macroeconomic Factors on the Market
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Consumers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Market Drivers
- 4.7.1 Accelerating Industry 4.0 Adoption and Smart Factory Initiatives
- 4.7.2 Increased Adoption of Automation Systems in Manufacturing
- 4.7.3 Growing Demand for Energy-Efficient Production Lines
- 4.7.4 Rising Investments in Automotive Electric Vehicle Production Lines
- 4.7.5 EU-Funded Digital Innovation Hubs Driving PLC Integration in SMEs
- 4.7.6 Post-2024 European Chips Act Incentives Catalysing On-Shoring of PLC Chip Manufacturing
- 4.8 Market Restraints
- 4.8.1 Intensifying Competition from Industrial PCs and Edge Controllers
- 4.8.2 High Initial Capital Expenditure for Upgrading Legacy Systems
- 4.8.3 Cybersecurity Compliance Burden under EU NIS2 Directive
- 4.8.4 Skilled Labour Shortage in IEC 61131-3 Programming in Eastern Europe
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Hardware and Software
- 5.1.1.1 Large PLC
- 5.1.1.2 Medium PLC
- 5.1.1.3 Small PLC
- 5.1.1.4 Nano PLC
- 5.1.1.5 Other Hardware Types
- 5.1.2 Service
- 5.1.1 Hardware and Software
- 5.2 By Architecture
- 5.2.1 Modular PLC
- 5.2.2 Rack PLC
- 5.2.3 Compact PLC
- 5.2.4 Soft PLC
- 5.2.5 Safety PLC
- 5.3 By Application
- 5.3.1 Motion Control
- 5.3.2 Process Control
- 5.3.3 Sequential Control
- 5.3.4 Safety
- 5.3.5 Data Handling and Communications
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Food, Tobacco and Beverage
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Energy and Utilities
- 5.4.5 Pharmaceutical
- 5.4.6 Oil and Gas
- 5.4.7 Metals and Mining
- 5.4.8 Water and Wastewater
- 5.4.9 Other End-User Industries
- 5.5 By Geography
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Siemens AG
- 6.4.2 Schneider Electric SE
- 6.4.3 Rockwell Automation Inc.
- 6.4.4 Mitsubishi Electric Corporation
- 6.4.5 ABB Ltd.
- 6.4.6 Honeywell International Inc.
- 6.4.7 Omron Corporation
- 6.4.8 Emerson Electric Co.
- 6.4.9 Panasonic Corporation
- 6.4.10 Robert Bosch GmbH (Bosch Rexroth)
- 6.4.11 Hitachi Ltd
- 6.4.12 General Electric Co.
- 6.4.13 Beckhoff Automation GmbH
- 6.4.14 B and R Industrial Automation GmbH
- 6.4.15 Phoenix Contact GmbH
- 6.4.16 Festo SE and Co. KG
- 6.4.17 WAGO Kontakttechnik GmbH
- 6.4.18 Eaton Corporation plc
- 6.4.19 IDEC Corporation
- 6.4.20 Advantech Co. Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 亞太地區可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)中東可程式邏輯控制器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 嵌入式運動控制器市場規模、佔有率和成長分析:按控制器類型、應用、通訊介面、最終用戶、安裝方式和地區分類-2026-2033年產業預測
 虛擬PLC與軟PLC市場分析及預測(至2035年):類型、產品、服務、技術、組件、應用、部署、最終用戶、功能、解決方案
 嵌入式控制器市場報告:趨勢、預測與競爭分析(至2035年)可程式邏輯控制器(PLC):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 可程式邏輯控制器(PLC)市場-2026-2032年全球市場預測
 2026-2030年全球可程式邏輯控制器(PLC)市場
 可程式材料市場預測至2034年-按材料類型、刺激類型、功能、應用、形態和地區分類的全球分析可程式邏輯控制器 (PLC) 市場預測至 2034 年——按類型、組件、行業、應用、最終用戶和地區分類的全球分析