


 |
市場調查報告書
商品編碼
2124471
英國瓦楞紙包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)United Kingdom Corrugated Board Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,英國瓦楞紙板包裝市場預計到 2026 年價值 126 億美元,高於 2025 年的 121.3 億美元,預計到 2031 年將達到 152.1 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 3.85%。
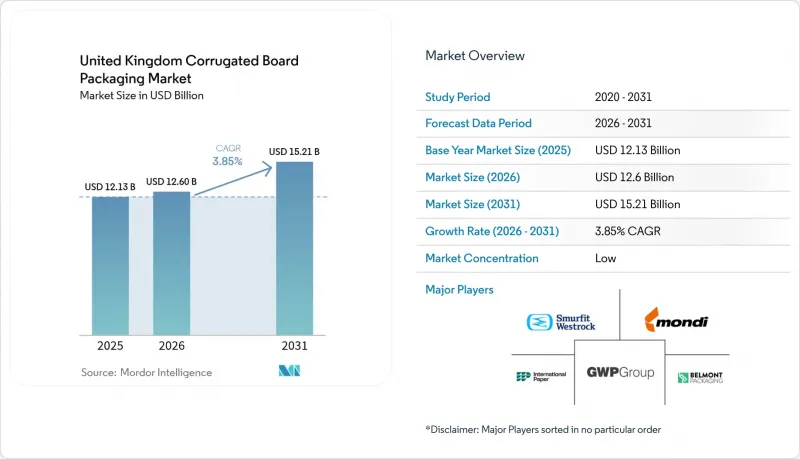
本報告按終端用戶行業(食品、飲料、電子商務、電氣和電子設備等)、瓦楞類型(A型、B型、C型、E型等)、紙板類型(單面、單層瓦楞紙板等)和印刷技術(柔版印刷、數位印刷、膠印覆膜等)進行分類。市場預測以美元計價。
英國瓦楞紙板包裝市場趨勢與洞察
電子商務履約量的激增
與傳統銷售管道相比,線上零售每個小包裹所需的保護性包裝材料大約多出30%,隨著小包裹數量的成長,對瓦楞紙板的需求也隨之增加。 2024年,英國電子商務銷售額激增15.8%,鞏固了從服飾到小型電子設備等眾多品類消費者行為的轉變。加工商正在採用人工智慧驅動的“按需瓦楞紙箱製造設備”,在不影響強度的前提下,可減少高達25%的材料用量,從而實現尺寸合適的運輸解決方案,降低體積重量費用。從電商平台到製造執行系統的直接資料整合,降低了庫存水平,縮短了響應時間,為追求卓越開箱體驗的品牌提供了決定性優勢。順應這一趨勢的專業加工商正日益重視數位印刷,以極低的設定成本實現可變圖形和事件關聯宣傳活動。
零售業向「現貨包裝」的轉變
像 Tesco 和 ASDA 這樣的大型連鎖超市正在其常溫區推廣「即買即用」包裝,從而將店內人事費用降低高達 50%,並顯著減少補貨過程中的商品損壞。帶有穿孔和易撕條的紙板包裝設計,既滿足了運輸過程中的抗衝擊性需求,又能實現快速展示。為了協調展示形狀、包裝箱數量和堆疊穩定性,品牌商、零售商和包裝加工商之間的合作日益緊密。小規模、專注於本地市場的包裝加工商透過快速原型製作和在地化服務來建立客戶信任,而全國性公司則利用模切和高產能柔版印刷機的規模經濟效益來創造價值。對於成功的參與者而言,由於優質的結構特性和對門市邊緣展示標準的嚴格遵守,銷售量得以提升。
再生紙供應再次趨緊。
2024年,紙張回收券(PRN)價格達到每噸180-200英鎊,創下20年來的新高,凸顯了紙張回收量與造紙廠接收量之間存在的巨大不平衡。由於混合一般廢棄物中的雜質會降低纖維質量,加工商被迫要么採購價格更高的分類紙,要么從歐洲大陸的供應商進口再生紙。大型綜合製造商正透過購買回收車輛和分類設施來確保原料供應,並減少對現貨市場的依賴。而缺乏這些能力的小型獨立公司則被迫忍受間歇性停產,或提高成品紙箱的價格,從而面臨市場佔有率流失的風險。外匯波動進一步推高了成本,歐元計價的進口價格兌英鎊上漲,使得採購避險變得更加複雜。
細分市場分析
到2025年,食品應用將佔英國瓦楞紙包裝市場的34.92%,反映出整個供應鏈對生鮮食品、保存食品食品和飲料等產品對纖維基運輸包裝的強烈依賴。該領域的成長持續與對難以回收的塑膠替代品的需求不斷成長有關,尤其是用於新鮮水果的防潮塗層托盤。隨著超級市場向消費者強調可回收性,零售業對瓦楞紙包裝的採用正在加速,這為具備阻隔加工能力的加工商帶來了穩定的訂單。電子商務市場雖然規模較小,但預計將以5.16%的複合年成長率成長。這主要得益於「直接面對消費者(DTC)」的配送模式,這種模式需要精美的圖案設計,既要優先考慮終端用戶的開箱體驗,又要保持與運輸紙箱相同的抗破損強度。隨著小包裹數量的增加,英國電子商務運輸用瓦楞紙包裝市場預計將快速成長,從而為配備數位印刷機的工廠創造對盈利的小批量生產的需求。
飲料包裝製造商憑藉多包裝托架和快速柔版印刷技術,在體育賽事和節日促銷活動中保持強勁的成長勢頭。電子產品和個人護理用品這一細分市場雖然噸位相對小規模,但由於防靜電襯紙和優質印刷技術的應用,每平方公尺的收益卻很高。因此,終端用途的多元化能夠有效抵禦個別消費品類週期性波動所帶來的影響,這也是大型綜合性企業採取的策略性風險避險策略。
C型瓦楞紙板在英國瓦楞紙板市場佔有31.74%的佔有率,因其均衡的緩衝性能和優異的印刷性能而備受青睞。然而,F/N超薄瓦楞紙板正以其預期4.80%的複合年成長率吸引著人們的目光。其超薄結構不僅能夠呈現更精細的圖案,還能有效降低體積重量,這在以體積計費的小包裹遞送網路中尤其重要。隨著服裝和化妝品托運人追求「適合拍照」的包裝展示效果,同時又希望盡可能減少空間佔用,預計超薄瓦楞紙板在英國瓦楞紙板市場的佔有率將進一步擴大。
A型和B型瓦楞紙對於較重或易碎的SKU仍然至關重要,因為在這些產品中,跌落測試性能比銷售最佳化更為重要。 E型瓦楞紙兼具美觀與結構強度,廣泛應用於「貨架即用」包裝,其外表面同時也是產品展示面板。隨著瓦楞紙種類的增加,庫存計劃變得更加複雜,加工商擴大採用數位孿生軟體來模擬不同紙張重量。成功的企業正在努力平衡各種瓦楞紙選項與快速換型之間的關係,從而最大限度地減少停機時間和廢棄物。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務履約量的激增
- 零售商向「即買即用」包裝的過渡
- 一次性塑膠的替代品
- 成本最佳化的輕量化槽紋加工技術
- 人工智慧驅動的按需盒系統
- 強制性碳足跡標籤
- 市場限制因素
- 再生紙供應再次趨緊。
- 能源價格波動對工廠利潤率帶來壓力。
- 英國物流業人手不足
- 來自東歐的進口競爭
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
- 投資分析
- 全球瓦楞紙板包裝市場概覽
第5章 市場規模與成長預測
- 按最終用戶行業分類
- 食物
- 加工食品
- 生鮮食品和農產品
- 飲料
- 電子商務
- 電氣和電子設備
- 個人護理化妝品
- 其他終端用戶產業
- 食物
- 長笛類型
- 長笛
- 低音長笛
- C調長笛
- E 長笛
- F/N 微型笛
- 其他類型的長笛
- 依電路板類型
- 單面瓦楞紙板
- 單層瓦楞紙板
- 雙層瓦楞紙板
- 三層紙板
- 透過印刷技術
- 柔版印刷
- 數位印刷
- 乳化
- 網版印刷
- 其他印刷技術
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Smurfit WestRock
- International Paper Company
- Mondi plc
- GWP Group Ltd.
- The Box Factory Ltd.
- Belmont Packaging Ltd.
- The Corrugated Case Company Ltd.
- Nuttall Packaging
- Cardboard Box Company Ltd.
- Saica Group
- Rigid Containers Ltd.
- Board24 Ltd.
- Cepac Holdings Ltd.
- Boxes and Packaging(UK)Ltd.
- LC Packaging UK Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom corrugated board packaging market size in 2026 is estimated at USD 12.6 billion, growing from 2025 value of USD 12.13 billion with 2031 projections showing USD 15.21 billion, growing at 3.85% CAGR over 2026-2031.
This report is Segmented by End-User Industry (Food, Beverages, E-Commerce, Electrical and Electronics, and More), Flute Type (A-Flute, B-Flute, C-Flute, E-Flute, and More), Board Type (Single Face, Single Wall Board, and More), Printing Technology (Flexography, Digital Printing, Litho-Lamination, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Corrugated Board Packaging Market Trends and Insights
E-commerce Fulfillment Volume Surge
Online retail requires about 30% more protective packaging per parcel than traditional channels, elevating corrugated demand as parcel counts climb. United Kingdom e-commerce sales leapt 15.8% in 2024, locking in behavioral shifts that spread across categories ranging from apparel to small electronics. Converters integrate AI-driven box-on-demand equipment that trims material use by up to 25% without sacrificing strength, enabling right-sized shipping solutions that control dimensional-weight charges. Direct data feeds from e-commerce storefronts into manufacturing execution systems cut inventory holdings and sharpen response times, a decisive advantage for brands targeting premium unboxing experiences. Specialized converters riding this wave often stress digital printing, enabling variable graphics and event-driven campaigns at minimal setup cost.
Retailer Shift to Shelf-Ready Packaging
Major grocery chains such as Tesco and ASDA broadened shelf-ready mandates across ambient aisles, reducing in-store labor by up to 50% and slashing damage rates during restocking. Corrugated designs featuring perforations and easy-open tear strips satisfy the mixed need for shipping resistance and rapid presentation. Collaboration among brands, retailers, and converters intensifies because display geometry, case counts, and stacking integrity must harmonize. Smaller regional converters build loyalty through fast prototyping and local service, whereas national players extract value from die-cutting scale and high-capacity flexo presses. The payoff for successful participants is higher unit revenue from premium structural features and higher end-of-aisle compliance.
Re-tightening Recycled Paper Availability
Paper Recovery Note (PRN) values broke two-decade highs at GBP 180-200 per tonne in 2024, exposing the imbalance between collection output and mill intake. Contamination in mixed municipal streams erodes fiber quality, forcing converters either to hunt costlier sorted grades or import recovered paper from continental suppliers. Integrated producers respond by acquiring collection fleets and sorting facilities, securing feedstock, and reducing spot-market exposure. Smaller independents, lacking such scope, endure episodic downtime or raise finished-box prices, risking share loss. Currency volatility adds another cost layer when euro-denominated imports rise against sterling, complicating procurement hedges.
Other drivers and restraints analyzed in the detailed report include:
- Substitution Away from Single-Use Plastics
- Cost-Optimized Lightweight Fluting Technology
- Energy-Price Volatility Pressuring Mill Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Food applications represented 34.92% of the United Kingdom corrugated board packaging market in 2025, reflecting entrenched dependence on fiber-based transit packaging across produce, ambient grocery, and beverage supply chains. The segment's growth remains linked to substitution away from hard-to-recycle plastics, especially for fresh fruit trays incorporating moisture-resistant coatings. Retail take-up accelerates as supermarkets showcase the recyclability narrative to shoppers, locking in volume for converters with barrier-treatment capacity. E-commerce, though smaller, is forecast to advance at a 5.16% CAGR, buoyed by direct-to-consumer shipping formats that often demand burst strength equal to transit boxes but refined graphics aimed at end-user unboxing. The United Kingdom corrugated board packaging market size for e-commerce shipments is projected to balloon alongside parcel counts, supplying profitable short-run work to plants outfitted with digital presses.
Packagers serving beverages maintain steady momentum through multi-pack carriers, exploiting flexo's high-speed capability for promotional branding aligned with sporting and holiday calendars. Electronics and personal-care niches, while comparatively modest in tonnage, deliver higher revenue per square meter due to anti-static liners and premium printing. End-use diversification thus cushions overall demand against cyclical swings in any single consumption category, a strategic hedge embraced by larger integrated players.
C-Flute holds a 31.74% slice of the United Kingdom corrugated board packaging market share, beloved for its balanced cushioning and print surface. Yet F/N Microflute is stealing the spotlight with a projected 4.80% CAGR; its ultra-thin profile allows finer graphics while shaving dimensional weight, an attribute highly prized in parcel networks where carriers bill by volume. The United Kingdom corrugated board packaging market size allocated to microflute designs is set to rise as apparel and cosmetic shippers demand Instagram-ready presentation without superfluous airspace.
A- and B-Flute grades remain essential for heavy or fragile SKUs where drop-test performance eclipses cube-optimization needs. E-Flute, positioned between display aesthetics and structural integrity, thrives in shelf-ready formats whose outer facing must double as a merchandising panel. Ongoing flute diversification complicates inventory planning, prompting converters to deploy digital twin software that simulates performance at varying grammages before committing paper. The winners balance wide flute arsenals with agile changeovers, minimizing downtime and scrap.
Complete Report Scope:
- By End-User Industry
- Food
- Processed Foods
- Fresh Food and Produce
- Beverages
- E-commerce
- Electrical and Electronics
- Personal Care and Cosmetics
- Other End-User Industries
- Food
- By Flute Type
- A-Flute
- B-Flute
- C-Flute
- E-Flute
- F/N Microflute
- Other Flute Types
- By Board Type
- Single Face
- Single Wall
- Double Wall
- Triple Wall
- By Printing Technology
- Flexography
- Digital Printing
- Litho-lamination
- Screen Printing
- Other Printing Technologies
List of Companies Covered in this Report:
- Smurfit WestRock
- International Paper Company
- Mondi plc
- GWP Group Ltd.
- The Box Factory Ltd.
- Belmont Packaging Ltd.
- The Corrugated Case Company Ltd.
- Nuttall Packaging
- Cardboard Box Company Ltd.
- Saica Group
- Rigid Containers Ltd.
- Board24 Ltd.
- Cepac Holdings Ltd.
- Boxes and Packaging (UK) Ltd.
- LC Packaging UK Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce fulfilment volume surge
- 4.2.2 Retailer shift to shelf-ready packaging
- 4.2.3 Substitution away from single-use plastics
- 4.2.4 Cost-optimised lightweight fluting technology
- 4.2.5 AI-enabled box-on-demand systems
- 4.2.6 Carbon-footprint labelling mandates
- 4.3 Market Restraints
- 4.3.1 Re-tightening recycled paper availability
- 4.3.2 Energy-price volatility pressuring mill margins
- 4.3.3 Labour shortages in UK logistics
- 4.3.4 Import competition from Eastern Europe
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
- 4.10 Overview of the Global Corrugated Board Packaging Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End-User Industry
- 5.1.1 Food
- 5.1.1.1 Processed Foods
- 5.1.1.2 Fresh Food and Produce
- 5.1.2 Beverages
- 5.1.3 E-commerce
- 5.1.4 Electrical and Electronics
- 5.1.5 Personal Care and Cosmetics
- 5.1.6 Other End-User Industries
- 5.1.1 Food
- 5.2 By Flute Type
- 5.2.1 A-Flute
- 5.2.2 B-Flute
- 5.2.3 C-Flute
- 5.2.4 E-Flute
- 5.2.5 F/N Microflute
- 5.2.6 Other Flute Types
- 5.3 By Board Type
- 5.3.1 Single Face
- 5.3.2 Single Wall
- 5.3.3 Double Wall
- 5.3.4 Triple Wall
- 5.4 By Printing Technology
- 5.4.1 Flexography
- 5.4.2 Digital Printing
- 5.4.3 Litho-lamination
- 5.4.4 Screen Printing
- 5.4.5 Other Printing Technologies
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Smurfit WestRock
- 6.4.2 International Paper Company
- 6.4.3 Mondi plc
- 6.4.4 GWP Group Ltd.
- 6.4.5 The Box Factory Ltd.
- 6.4.6 Belmont Packaging Ltd.
- 6.4.7 The Corrugated Case Company Ltd.
- 6.4.8 Nuttall Packaging
- 6.4.9 Cardboard Box Company Ltd.
- 6.4.10 Saica Group
- 6.4.11 Rigid Containers Ltd.
- 6.4.12 Board24 Ltd.
- 6.4.13 Cepac Holdings Ltd.
- 6.4.14 Boxes and Packaging (UK) Ltd.
- 6.4.15 LC Packaging UK Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 纖維板包裝市場規模、佔有率、成長和行業分析:按纖維板類型、結構、產品類型、箱體形狀、最終用途和地區分類,並預測至2034年
 歐洲、中東和非洲(EMEA)瓦楞紙包裝:市場佔有率分析、行業趨勢與統計數據以及成長預測(2026-2031 年)瓦楞紙板包裝:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 2026年全球紙本拉環郵件市場報告
 瓦楞紙板包裝市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 瓦楞紙板包裝市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年
 2032 年瓦楞包裝市場預測:按類型、材料類型、瓦楞類型、包裝類型、應用、最終用戶和地區進行的全球分析瓦楞包裝市場:依類型、最終用戶行業和地區,2026年至2032年