


 |
市場調查報告書
商品編碼
2038752
瓦楞紙板包裝市場機會、成長要素、產業趨勢分析及2026-2035年預測。Corrugated Board Packaging Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025 年全球瓦楞紙板包裝市場規模預計為 1,989 億美元,預計到 2035 年將達到 3,040 億美元,年複合成長率為 4.4%。
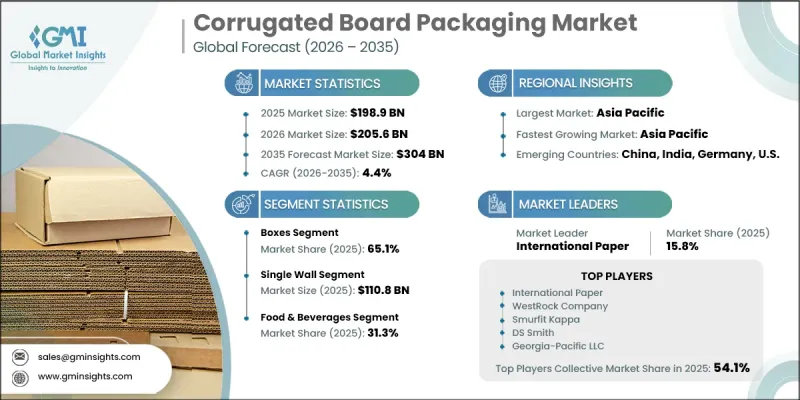
市場成長主要得益於電子商務的快速發展,這持續推高了對可靠且高效的運輸和配送包裝解決方案的需求。同時,監管機構要求替換塑膠包裝材料的壓力也加速了向永續瓦楞紙板替代品的轉型。食品和農產品分銷的擴張進一步刺激了需求,因為這些行業需要耐用且具有保護性的包裝以確保運輸安全。全球製造業產量的成長也促進了倉儲和物流領域瓦楞紙板包裝消費量的成長。輕質紙板設計和高性能結構的不斷創新提高了成本效益,減輕了運輸重量,並提升了供應鏈效率。這些進步使企業能夠在保持強度和耐用性的同時最佳化包裝解決方案。隨著各行業日益關注永續性、營運效率和產品保護,瓦楞紙板包裝在全球許多終端應用領域都展現出強勁的發展勢頭。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 1989億美元 |
| 預測金額 | 3040億美元 |
| 複合年成長率 | 4.4% |
電子商務和一體化零售模式的快速發展進一步推動了瓦楞紙板包裝市場的成長。線上訂單量的成長顯著帶動了包裝、運輸和末端配送環節對瓦楞紙箱的需求。此外,工業生產的擴張也增加了對可靠的二次包裝解決方案的需求,以確保產品在運輸過程中的安全。紙板技術的進步使得輕質高強度材料的研發成為可能,從而提高了物流效率並降低了整體運輸成本。這些因素進一步提升了瓦楞紙板包裝在零售、食品供應鏈、物流營運和工業應用領域的重要性。
預計到2035年,托盤市場將以5.5%的複合年成長率成長,這主要得益於市場對高效物料搬運和精簡供應鏈營運日益成長的需求。瓦楞紙板托盤因其輕盈、經濟、衛生等優勢而廣受歡迎,適用於眾多行業。其降低運輸成本、提高運輸效率的特性,推動了其在物流和配送網路的應用。此外,對最佳化倉儲營運和改進貨物管理的需求不斷成長,也進一步促進了該領域的擴張。
受市場對耐用、高強度包裝解決方案需求不斷成長的推動,雙層壁包裝市場預計將在2026年至2035年間以3.7%的複合年成長率成長。該市場廣泛用於運輸重型貨物以及在搬運和運輸過程中需要高度保護的產品。雙層結構提高了承載能力和抗衝擊性,使其適用於工業和散裝包裝應用。物流網路的擴張以及對安全包裝解決方案的需求正在推動該市場的穩定成長。
北美瓦楞紙包裝市場擁有高度發展的零售和物流生態系統,預計2025年將佔28.1%的市場佔有率。該地區電子商務的高滲透率和先進的物流基礎設施推動了對瓦楞紙包裝解決方案的穩定需求。小包裹量的成長和成熟的第三方物流供應商的存在進一步促進了市場擴張。此外,倉庫和履約中心自動化技術的廣泛應用提高了包裝效率,並支援了永續成長。成熟的製造地和對永續包裝實踐日益成長的關注也增強了全部區域。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 電子商務和全通路零售的快速成長
- 對永續和可回收包裝解決方案的需求日益成長
- 食品、生鮮食品和農產品分銷的成長
- 工業和製造業產出增加
- 輕量化和性能最佳化型板材的創新
- 產業潛在風險與挑戰
- 紙張原料與能源成本的波動
- 由於體積龐大且後勤負擔重,操作受到限制。
- 市場機遇
- 瓦楞紙板包裝在醫藥和醫療保健物流領域的應用拓展
- 瓦楞紙板包裝在自動化倉庫和履約中心已廣泛應用。
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特五力分析
- PESTEL 分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要公司的競爭標竿分析
- 財務績效比較
- 銷售量
- 利潤率
- 研究與開發
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 業務拓展與投資策略
- 數位轉型計劃
- 新興競爭對手和新創競爭對手的發展趨勢
第5章 市場估算與預測:依笛型分類,2022-2035年
- A型長笛
- B型長笛
- C型笛
- E型長笛
- F型長笛
第6章 市場估計與預測:依類型分類,2022-2035年
- 單層
- 雙層壁
- 三層壁
第7章 市場估算與預測:依產品類型分類,2022-2035年
- 盒子
- 托盤
- 座位
- 調色盤
第8章 市場估算與預測:依最終用途產業分類,2022-2035年
- 食品/飲料
- 製藥
- 化妝品和個人護理
- 車
- 運輸/物流
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第10章:公司簡介
- 全球主要公司
- International Paper
- WestRock Company
- Smurfit Kappa
- DS Smith
- Georgia-Pacific LLC
- 按地區分類的主要公司
- 北美洲
- Arvco Container Corporation
- Cascades Inc.
- Green Bay Packaging
- Packaging Corporation of America
- Pratt Industries, Inc.
- U-Pack
- 亞太地區
- Nine Dragons Paper Holdings Limited
- Oji Holdings Corporation
- Rengo Co., Ltd.
- Visy Industries
- 歐洲
- Alliabox
- Mondi Group
- Progroup AG
- Stora Enso
- Middle East &Africa
- SCG Packaging
- 北美洲
The Global Corrugated Board Packaging Market was valued at USD 198.9 billion in 2025 and is estimated to grow at a CAGR of 4.4% to reach USD 304 billion by 2035.
Market growth is driven by the rapid rise in e-commerce activities, which continues to increase the need for reliable and efficient packaging solutions for shipping and delivery. In parallel, regulatory pressure to replace plastic-based packaging materials is accelerating the shift toward sustainable corrugated alternatives. Growing distribution of food products and agricultural goods is further strengthening demand, as these industries require durable and protective packaging for safe transportation. Expansion in global manufacturing output is also contributing to higher consumption of corrugated packaging for storage and logistics purposes. Continuous innovation in lightweight board designs and high-performance structures is improving cost efficiency, reducing transportation weight, and enhancing supply chain performance. These advancements are enabling companies to optimize packaging solutions while maintaining strength and durability. As industries increasingly focus on sustainability, operational efficiency, and product protection, corrugated board packaging is gaining strong traction across a wide range of end-use sectors worldwide.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $198.9 Billion |
| Forecast Value | $304 Billion |
| CAGR | 4.4% |
The corrugated board packaging market is further supported by the rapid evolution of e-commerce and integrated retail models. Increasing online order volumes are significantly boosting demand for corrugated boxes used in packaging, transportation, and last-mile delivery operations. Growth in industrial production is also creating higher demand for dependable secondary packaging solutions that ensure product safety during transit. Advancements in board engineering are enabling the development of lighter yet stronger materials, improving logistics efficiency and reducing overall shipping costs. These factors are reinforcing the importance of corrugated packaging across retail, food supply chains, logistics operations, and industrial applications.
The pallets segment is expected to grow at a CAGR of 5.5% through 2035, driven by increasing requirements for efficient material handling and streamlined supply chain operations. Corrugated pallets are gaining popularity due to their lightweight nature, cost-effectiveness, and hygienic properties, making them suitable for various industries. Their ability to reduce handling costs and improve transportation efficiency is encouraging adoption in logistics and distribution networks. Growing demand for optimized warehouse operations and improved freight management is further supporting segment expansion.
The double wall segment is projected to grow at a CAGR of 3.7% during 2026-2035, supported by rising demand for durable and high-strength packaging solutions. This segment is widely used for transporting heavier goods and products that require enhanced protection during handling and shipping. The dual-layer structure offers increased load-bearing capacity and resistance to external impacts, making it suitable for industrial and bulk packaging applications. Expanding logistics networks and the need for secure packaging solutions are driving steady growth in this segment.
North America Corrugated Board Packaging Market accounted for 28.1% share in 2025, supported by a highly developed retail and logistics ecosystem. The region's strong e-commerce penetration and advanced distribution infrastructure are driving consistent demand for corrugated packaging solutions. High volumes of parcel shipments and the presence of established third-party logistics providers are further contributing to market expansion. In addition, widespread adoption of automation in warehousing and fulfillment centers is enhancing packaging efficiency and supporting sustained growth. A well-established manufacturing base and increasing focus on sustainable packaging practices are also strengthening the market outlook across the region.
Key companies operating in the Global Corrugated Board Packaging Market include International Paper, WestRock Company, SmurfitWestRock, Mondi Group, DS Smith, Stora Enso, Packaging Corporation of America, Pratt Industries, Inc., Oji Holdings Corporation, Rengo Co., Ltd., Nine Dragons Paper Holdings Limited, Cascades Inc., Green Bay Packaging, Georgia-Pacific LLC, Progroup AG, SCG Packaging, Visy Industries, Alliabox, Arvco Container Corporation, and U-Pack. Companies in the Corrugated Board Packaging Market are adopting a range of strategic initiatives to strengthen their market position and expand their competitive advantage. A primary focus is on developing sustainable and recyclable packaging solutions to meet evolving environmental regulations and consumer preferences. Firms are investing in advanced manufacturing technologies to improve production efficiency, reduce material usage, and enhance product performance. Strategic collaborations with e-commerce companies, retailers, and logistics providers are helping businesses secure long-term supply agreements and expand their customer base. Companies are also increasing their presence in emerging markets through capacity expansions and localized production facilities.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Flute type trends
- 2.2.2 Type trends
- 2.2.3 Product type trends
- 2.2.4 End-use industry trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid growth of e-commerce and omnichannel retail
- 3.2.1.2 Rising demand for sustainable and recyclable packaging solutions
- 3.2.1.3 Growth in food, fresh produce, and agricultural distribution
- 3.2.1.4 Increasing industrial and manufacturing output
- 3.2.1.5 Innovation in lightweight and performance-optimized board grades
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Volatility in paper raw material and energy costs
- 3.2.2.2 Operational constraints from bulky nature and logistics intensity
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of corrugated packaging in pharmaceuticals and healthcare logistics
- 3.2.3.2 Proliferation of corrugated packaging in automated warehousing and fulfillment centers
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Flute Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Type A flute
- 5.3 Type B flute
- 5.4 Type C flute
- 5.5 Type E flute
- 5.6 Type F flute
Chapter 6 Market Estimates and Forecast, By Type, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Single wall
- 6.3 Double wall
- 6.4 Triple wall
Chapter 7 Market Estimates and Forecast, By Product Type, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Boxes
- 7.3 Trays
- 7.4 Sheets
- 7.5 Pallets
Chapter 8 Market Estimates and Forecast, By End-use Industry, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Food & beverages
- 8.3 Pharmaceuticals
- 8.4 Cosmetics & personal care
- 8.5 Automotive
- 8.6 Transportation & logistics
- 8.7 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Russia
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 International Paper
- 10.1.2 WestRock Company
- 10.1.3 Smurfit Kappa
- 10.1.4 DS Smith
- 10.1.5 Georgia-Pacific LLC
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Arvco Container Corporation
- 10.2.1.2 Cascades Inc.
- 10.2.1.3 Green Bay Packaging
- 10.2.1.4 Packaging Corporation of America
- 10.2.1.5 Pratt Industries, Inc.
- 10.2.1.6 U-Pack
- 10.2.2 Asia Pacific
- 10.2.2.1 Nine Dragons Paper Holdings Limited
- 10.2.2.2 Oji Holdings Corporation
- 10.2.2.3 Rengo Co., Ltd.
- 10.2.2.4 Visy Industries
- 10.2.3 Europe
- 10.2.3.1 Alliabox
- 10.2.3.2 Mondi Group
- 10.2.3.3 Progroup AG
- 10.2.3.4 Stora Enso
- 10.2.4 Middle East & Africa
- 10.2.4.1 SCG Packaging
- 10.2.1 North America

 纖維板包裝市場規模、佔有率、成長和行業分析:按纖維板類型、結構、產品類型、箱體形狀、最終用途和地區分類,並預測至2034年
 歐洲、中東和非洲(EMEA)瓦楞紙包裝:市場佔有率分析、行業趨勢與統計數據以及成長預測(2026-2031 年)英國瓦楞紙包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)瓦楞紙板包裝:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 2026年全球紙本拉環郵件市場報告
 瓦楞紙板包裝市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年
 2032 年瓦楞包裝市場預測:按類型、材料類型、瓦楞類型、包裝類型、應用、最終用戶和地區進行的全球分析瓦楞包裝市場:依類型、最終用戶行業和地區,2026年至2032年