


 |
市場調查報告書
商品編碼
2122658
瓦楞紙板包裝:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Corrugated Board Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
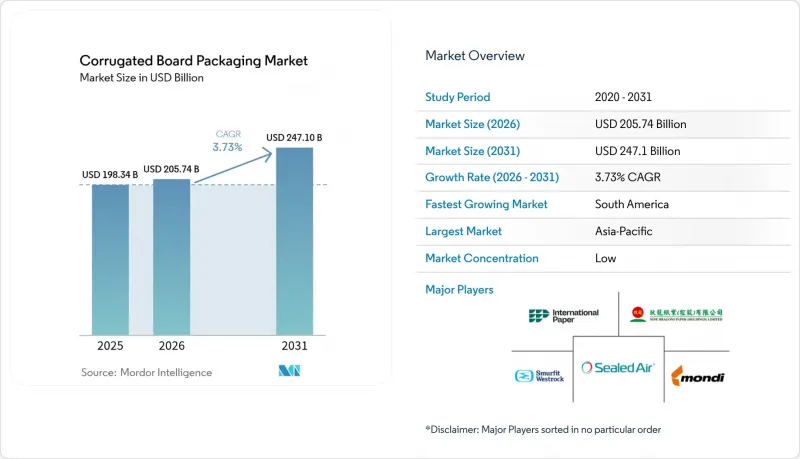
據 Mordor Intelligence 稱,瓦楞紙板包裝市場預計到 2026 年價值 2057.4 億美元,高於 2025 年的 1983.4 億美元,預計到 2031 年將達到 2,471 億美元。
預計 2026 年至 2031 年的複合年成長率為 3.73%。
本報告按材料類型(原生紙板、再生紙板)、紙箱類型(開槽紙箱、伸縮紙箱、其他)、終端用戶行業(食品、飲料、個人護理及家居用品、其他)、紙板類型(單層、雙層、其他)、印刷技術(柔版印刷、數位印刷、其他)和地區進行細分。市場預測以美元計價。
全球瓦楞紙板包裝市場趨勢及洞察
強制使用環保材料將鼓勵紡織品的替代。
關於可回收性的新法規正促使包裝材料的選擇轉向紡織品。歐盟要求所有包裝在2030年前必須可回收,並制定了塑膠的最低再生材料含量標準,這使得瓦楞紙板成為合規風險較低的選擇。在美國,鼓勵使用可回收基材的收費系統已經訂定,與塑膠包裝相比,可回收包裝的成本優勢高達15%。由於塑膠回收再利用基礎設施的建設遠超過2030年的最後期限,各大品牌正加快規範變更的步伐。瓦楞紙板71-76%的回收率簡化了審計追蹤管理,有助於企業履行ESG(環境、社會和治理)承諾,並降低處罰風險。據造紙商稱,由於加工商調整生產線以滿足零售商的評估標準,紡織品SKU的訂單前置作業時間已縮短了兩週。
電子商務小包裹的爆炸性成長迫使人們重新設計包裝規格。
預計到2029年,全球電子商務出貨量將達到3,400億件,高於2024年的2,200億件,這使得跌落測試耐久性和體積重量效率等功能性指標的重要性日益凸顯。目前,雙層瓦楞紙板和微瓦楞紙板佔主要物流公司運輸小包裹總量的四分之一以上。設備供應商正積極響應這一趨勢,採用按需紙箱生產系統,從而降低40%的人事費用,減少填充材用量,並將每筆訂單的材料成本降低15%。訂閱制電商企業開始指定可印刷的內襯來講述品牌故事,進一步加速了運輸容器內數位印刷圖形的普及。這些變化鞏固了瓦楞紙板不僅作為運輸媒介,更成為行銷媒介的地位。
可重複使用塑膠(RPC)的引入對一次性產品的需求提出了挑戰。
零售商正在擴大用於生鮮食品和肉類的可回收塑膠容器(RPC)的使用範圍,因為這可以減少門市層級的產品損耗(縮水)並降低人事費用。法國、德國和南韓已實施重複使用配額和押金制度,優先使用耐用的木箱而非一次性紙箱。在自動化清洗網路中,每個RPC在經過25次以上的循環後成本降至0.25美元以下,使其在可預測的生鮮食品供應鏈中比一次性容器更具成本優勢。紙板製造商正透過高阻隔阻隔性、防潮塗層和防篡改鎖扣來保護其市場佔有率,但在高周轉率的分銷管道中,他們的利潤率正面臨壓力。
細分市場分析
到2025年,在成熟的回收網路和有利的生產者責任再利用(EPR)收費系統的支持下,再生紙將佔瓦楞紙包裝市場佔有率的55.05%。隨著品牌商提高消費後再生材料(PCC)含量標準,預計該細分市場將以4.56%的複合年成長率成長。儘管原生牛皮紙襯紙的市場佔有率持續下降,但它在重型出口紙箱中仍然佔據重要地位。由麥秸、稻殼和番茄莖製成的紙漿正進入商業性試點階段。實驗室測試表明,與傳統再生紙漿相比,其抗張強度提高了25%。投資建設地理位置分散的紙漿生產設施對於控制原料水分含量和物流成本至關重要。成功擴大生產規模將有助於緩解再生紙(OCC)的價格波動,實現纖維來源多元化,並增強供應鏈的韌性。
農業廢棄物紙漿具有許多環境效益,例如與原生木纖維相比,碳排放強度可降低20-25%,因為它避免了森林砍伐過程。義大利和印度的領先企業已將15-20%的農業廢棄物摻入瓦楞紙板生產設備中,且無需對現有設備進行任何改造。儘管食品接觸適用性的認證架構仍處於起步階段,但製造商預計到2027年,相關法規的協調統一將會取得進展。這些創新表明,瓦楞紙板包裝市場正從「原生材料與再生材料」的二元對立模式轉向更廣泛的多纖維組合,從而增強其對當地資源限制的適應能力。
2025年,傳統標準槽式包裝盒(RSC)的市佔率為32.05%,而折疊式包裝預計到2031年將以5.48%的複合年成長率成長,這主要得益於電商品牌商對更快組裝設計的需求,以提升拆箱體驗。自動化組裝設備每分鐘可處理35個折疊包裝盒,比人工RSC生產線快40%,顯著減輕了履約中心的作業量。從瓦楞紙包裝市場的規模來看,預計這一轉變將在2026年至2031年間帶來89億美元的收入成長。
在體積效率和托盤化至關重要的領域,例如工業備件分銷,開槽紙箱仍然保持著成本優勢。伸縮式和硬式套裝紙箱則佔據高階電子產品等高階細分市場,在這些市場中,視覺美感和防損性能比材料成本更為重要。可數位印刷的折疊式包裝結構擴大採用易撕條和可重複使用的封條,以適應全通路物流流程。包裝結構的演變表明,性能標準、自動化能力和消費者參與度正在協同影響瓦楞紙包裝市場的規格趨勢。
區域分析
到2025年,亞太地區將佔全球瓦楞紙包裝市場39.85%的佔有率,並將繼續利用製造業整合和成本效益高的纖維採購優勢。九龍紙業正在將其年產能擴大至2537萬噸,以鞏固其在該地區的供應優勢。在中國的經濟獎勵策略提振國內消費的同時,越南和馬來西亞的出口型工廠也積極響應「一帶一路」貿易走廊的號召。對再生紙進口配額的投資也加速了利用當地農業廢棄物生產紙漿的試點項目,從而減少了對廢棄舊瓦楞紙板(OCC)的依賴。
南美洲是成長最快的貿易走廊,預計到2031年複合年成長率將達到7.05%。儘管面臨宏觀經濟逆風,巴西瓦楞紙板原紙的出貨量依然成長。這主要歸功於生產商為適應出口市場而對其工廠的生產系統進行調整。克拉賓公司位於巴拉那州的新工廠便是對未來產能進行前期投資的典型案例,而智利和哥倫比亞的加工商則在投資實現折疊和粘合機的自動化,以適應電子商務中使用的各種紙箱形狀。該地區擁有豐富的甘蔗渣和桉樹種植園,能夠實現纖維自給自足,並正在成為未來的農業廢棄物供應中心。
在北美和歐洲,由於監管合規和高附加價值創新,市場呈現穩定的個位數中段成長。隨著歐盟強制回收政策於2025年生效,已有6%的運輸塑膠包裝被瓦楞紙板取代。國際紙業斥資72億美元收購DS Smith,擴大了在兩大洲的永續包裝業務,預計到2027年將產生6億至7億美元的協同效應。歐洲的造紙廠在設備升級中優先考慮能源效率,例如,斯道拉恩索位於奧盧的工廠與傳統造紙機相比,溫室氣體排放強度降低了20%。在美國,數位印刷機的普及率已超過瓦楞紙板總印刷產能的18%,加速了消費品領域的大規模客製化進程。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 強制使用環保材料
- 電子商務小包裹的爆炸性成長
- 數位柔版混合印刷機的進展
- 輕型貨櫃板的經濟性
- 人工智慧驅動的包裝盒設計最佳化
- 利用農業廢棄物製成的纖維進行製漿
- 市場限制因素
- 可重複使用塑膠(RPC)的引入
- OCC能源價格波動劇烈
- 紙板製造機的電力消耗量上限
- 工廠工業用水取水量的限制
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依材料類型
- 原生貨櫃紙板
- 再生紙箱
- 盒式/結構
- 帶插槽的盒子
- 望遠鏡盒
- 硬盒
- 文件夾盒
- 按最終用戶行業分類
- 食物
- 加工食品
- 生鮮食品和農產品
- 飲料
- 個人護理和家居用品
- 電子商務履約
- 醫療和藥品
- 電氣和電子設備
- 產業
- 其他
- 食物
- 依電路板類型
- 單層壁
- 雙層壁
- 三層壁
- 微型笛
- 透過印刷技術
- 柔版印刷
- 數位的
- 光刻
- 螢幕
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 新加坡
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 南美洲
- 巴西
- 阿根廷
- 南美洲其他地區
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- International Paper Company
- Smurfit WestRock
- Mondi Group
- Nine Dragons Paper(Holdings)Limited
- Georgia-Pacific LLC
- Oji Holdings Corporation
- Stora Enso Oyj
- Sealed Air Corporation
- Pratt Industries
- Rengo Co., Ltd.
- Packaging Corporation of America
- Lee & Man Paper Manufacturing
- Klabin SA
- Cascades Inc.
- SCG Packaging
- Saica Group
- Orora Limited
- Visy Industries
- Grupo Gondi
- Astron Paper & Board Mill
- APP(Sinar Mas)
- Napco National
第7章 市場機會與未來展望
According to Mordor Intelligence, the corrugated board packaging market size in 2026 is estimated at USD 205.74 billion, growing from 2025 value of USD 198.34 billion with 2031 projections showing USD 247.1 billion, growing at 3.73% CAGR over 2026-2031.
This report is Segmented by Material Type (Virgin Containerboard, and Recycled Containerboard), Box Style (Slotted Boxes, Telescope Boxes, and More), End-User Industry (Food, Beverages, Personal and Household Care, and More), Board Type (Single Wall, Double Wall, and More), Printing Technology (Flexography, Digital, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Corrugated Board Packaging Market Trends and Insights
Eco-friendly material mandates drive fiber substitution
New recyclability rules are tilting packaging material choices toward fiber. The EU requirement that all packaging be recyclable by 2030, alongside minimum recycled-content quotas for plastics, has made corrugated the low-risk compliance option. Five U.S. states impose fee scales that reward recyclable substrates, creating cost advantages of up to 15% versus plastic formats. Brands are accelerating specification changes because plastic recycling infrastructure lag times exceed the 2030 deadline. Corrugated's 71-76% recovery rate simplifies audit trails, supports corporate ESG pledges, and limits penalty exposure. Mill operators report order lead-times for fiber-based SKUs shortening by two weeks as converters re-tool lines to meet retailer scorecard requirements.
E-commerce parcel explosion reshapes packaging specifications
Global e-commerce shipping volumes grew from 220 billion parcels in 2024 to a projected 340 billion by 2029, elevating functional priorities such as drop-test durability and dimensional-weight efficiency. Double-wall and micro-flute boards now constitute over one-quarter of parcels shipped via major integrators. Equipment suppliers respond with on-demand boxmaking systems that trim labor by 40% while reducing void-fill needs, thereby cutting per-order materials cost by 15%. Subscription-commerce operators are specifying printable interiors for brand storytelling, which further boosts the loading of digitally printed graphics inside the shipping container. These shifts cement corrugated's role as both a transport medium and a marketing surface.
Reusable plastics and RPCs adoption challenges single-use demand
Retailers expand returnable-plastic-container (RPC) pools for produce and meat because they cut shrinkage and reduce labor at the store level. France, Germany, and South Korea have introduced reuse quotas or deposit schemes that favor durable crates over single-use corrugated. Automated wash-back networks lower per-trip RPC cost below USD 0.25 when cycle counts exceed 25, undercutting single-use units for predictable fresh-food supply chains. Corrugated converts defend share using high-barrier moisture-resistant coatings and tamper-evident locking tabs, but face margin squeeze in high-turnover channels.
Other drivers and restraints analyzed in the detailed report include:
- Advances in digital and flexo hybrid presses enable mass customization
- AI-driven box-design optimisation reduces material consumption
- Volatile OCC and energy prices compress manufacturing margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Recycled grades commanded 55.05% of the corrugated board packaging market share in 2025, buoyed by mature collection networks and favorable EPR fee structures. The segment is forecast to grow at 4.56% CAGR as brand owners raise post-consumer-content thresholds. Virgin Kraft liner retains relevance for heavy-duty export cartons, but its volume share continues to erode. Wheat-straw, rice-husk, and tomato-stem pulps are entering commercial pilots; laboratory work shows tensile strength gains of up to 25% over conventional recycled pulp. Investment in regional decentralized pulping units is crucial to control raw-material moisture and logistics costs. Successful scale-up would temper OCC price cycles and diversify fiber sourcing, strengthening supply-chain resilience.
Agricultural-waste pulps also deliver environmental gains, trimming carbon intensity by 20-25% relative to virgin wood fiber because they bypass forest-harvesting steps. Early adopters in Italy and India are integrating agri-waste at 15-20% blend ratios without modifying corrugator settings. Though certification frameworks for food-contact compliance remain nascent, producers expect regulatory alignment by 2027. These innovations signal that the corrugated board packaging market will shift from a binary virgin-versus-recycled narrative to a broader multi-fiber portfolio, reinforcing its adaptability to regional resource constraints.
Traditional regular slotted containers (RSCs) held a 32.05% share in 2025, but folder-type formats are projected to increase at a 5.48% CAGR through 2031, propelled by e-commerce brand owners seeking quick-assembly designs that enhance the unboxing experience. Automated erecting equipment processes folder styles at 35 boxes min-1, 40% faster than manual RSC lines, saving fulfillment centers significant labor. In the corrugated board packaging market size context, this shift translates into incremental revenue of USD 8.9 billion between 2026 and 2031.
Slotted boxes retain cost advantages where cube efficiency and palletization are paramount, such as industrial spare parts distribution. Telescope and rigid-set boxes occupy premium niches, including luxury electronics, where visual aesthetics and crush prevention outweigh material cost. Digital print-ready folder constructions increasingly integrate tear-strips and returnable seals, aligning with omnichannel logistics flows. The evolving construction landscape illustrates how performance criteria, automation capability, and consumer engagement jointly influence specification trends within the corrugated board packaging market.
Complete Report Scope:
- By Material Type
- Virgin Containerboard
- Recycled Containerboard
- By Box Style / Construction
- Slotted Boxes
- Telescope Boxes
- Rigid Boxes
- Folder Boxes
- By End-User Industry
- Food
- Processed Foods
- Fresh Food and Produce
- Beverages
- Personal and Household Care
- E-commerce and Fulfilment
- Healthcare and Pharmaceuticals
- Electrical and Electronics
- Industrial
- Other End-user Industry
- Food
- By Board Type
- Single Wall
- Double Wall
- Triple Wall
- Micro-flute
- By Printing Technology
- Flexography
- Digital
- Lithography
- Screen
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Singapore
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific accounted for 39.85% of global corrugated board packaging market revenue in 2025 and continues to leverage manufacturing integration and cost-effective fiber sourcing. Nine Dragons Paper expanded annual capacity to 25.37 million tonnes, underpinning the region's supply dominance. China's stimulus measures stimulate domestic consumption, yet export-oriented plants in Vietnam and Malaysia now serve Belt-and-Road trade corridors. Investment in waste-paper-import quotas also encourages local agri-waste pulping pilots, mitigating OCC dependency.
South America represents the fastest-growing corridor, with a 7.05% CAGR projected to 2031. Brazil's containerboard shipments increased despite macro headwinds as producers realigned mills for export markets. Klabin's new Parana facility exemplifies forward-capacity bets, while Chilean and Colombian converters invest in folder-gluer automation to meet e-commerce box styles. Fiber self-sufficiency, anchored in abundant sugar-cane bagasse and eucalyptus plantations, positions the region as a future agri-waste supply hub.
North America and Europe exhibit steady mid-single-digit growth anchored in regulatory compliance and value-added innovation. The EU recyclability mandate that took effect in 2025 has already shifted 6% of plastic transit-packaging volume into corrugated. International Paper's USD 7.2 billion buyout of DS Smith extends its sustainable-packaging footprint across both continents and is expected to unlock USD 600-700 million in synergy by 2027. European mill upgrades prioritize energy conservation, with Stora Enso's Oulu line claiming 20% lower greenhouse-gas intensity than legacy paper machines. In the United States, digital press penetration exceeds 18% of installed corrugated print capacity, accelerating mass customization in consumer packaged goods.
- International Paper Company
- Smurfit WestRock
- Mondi Group
- Nine Dragons Paper (Holdings) Limited
- Georgia-Pacific LLC
- Oji Holdings Corporation
- Stora Enso Oyj
- Sealed Air Corporation
- Pratt Industries
- Rengo Co., Ltd.
- Packaging Corporation of America
- Lee & Man Paper Manufacturing
- Klabin S.A.
- Cascades Inc.
- SCG Packaging
- Saica Group
- Orora Limited
- Visy Industries
- Grupo Gondi
- Astron Paper & Board Mill
- APP (Sinar Mas)
- Napco National
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Eco-friendly material mandates
- 4.2.2 E-commerce parcel explosion
- 4.2.3 Advances in digital and flexo hybrid presses
- 4.2.4 Light-weight containerboard economics
- 4.2.5 AI-driven box-design optimisation
- 4.2.6 Agricultural-waste fibre pulping
- 4.3 Market Restraints
- 4.3.1 Reusable plastics and RPCs adoption
- 4.3.2 Volatile OCC and energy prices
- 4.3.3 Corrugator electricity-intensity caps
- 4.3.4 Industrial-water withdrawal limits at mills
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Material Type
- 5.1.1 Virgin Containerboard
- 5.1.2 Recycled Containerboard
- 5.2 By Box Style / Construction
- 5.2.1 Slotted Boxes
- 5.2.2 Telescope Boxes
- 5.2.3 Rigid Boxes
- 5.2.4 Folder Boxes
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.1.1 Processed Foods
- 5.3.1.2 Fresh Food and Produce
- 5.3.2 Beverages
- 5.3.3 Personal and Household Care
- 5.3.4 E-commerce and Fulfilment
- 5.3.5 Healthcare and Pharmaceuticals
- 5.3.6 Electrical and Electronics
- 5.3.7 Industrial
- 5.3.8 Other End-user Industry
- 5.3.1 Food
- 5.4 By Board Type
- 5.4.1 Single Wall
- 5.4.2 Double Wall
- 5.4.3 Triple Wall
- 5.4.4 Micro-flute
- 5.5 By Printing Technology
- 5.5.1 Flexography
- 5.5.2 Digital
- 5.5.3 Lithography
- 5.5.4 Screen
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Netherlands
- 5.6.2.7 Russia
- 5.6.2.8 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Singapore
- 5.6.3.7 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Turkey
- 5.6.4.1.4 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Nigeria
- 5.6.4.2.3 Egypt
- 5.6.4.2.4 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 International Paper Company
- 6.4.2 Smurfit WestRock
- 6.4.3 Mondi Group
- 6.4.4 Nine Dragons Paper (Holdings) Limited
- 6.4.5 Georgia-Pacific LLC
- 6.4.6 Oji Holdings Corporation
- 6.4.7 Stora Enso Oyj
- 6.4.8 Sealed Air Corporation
- 6.4.9 Pratt Industries
- 6.4.10 Rengo Co., Ltd.
- 6.4.11 Packaging Corporation of America
- 6.4.12 Lee & Man Paper Manufacturing
- 6.4.13 Klabin S.A.
- 6.4.14 Cascades Inc.
- 6.4.15 SCG Packaging
- 6.4.16 Saica Group
- 6.4.17 Orora Limited
- 6.4.18 Visy Industries
- 6.4.19 Grupo Gondi
- 6.4.20 Astron Paper & Board Mill
- 6.4.21 APP (Sinar Mas)
- 6.4.22 Napco National
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 纖維板包裝市場規模、佔有率、成長和行業分析:按纖維板類型、結構、產品類型、箱體形狀、最終用途和地區分類,並預測至2034年
 歐洲、中東和非洲(EMEA)瓦楞紙包裝:市場佔有率分析、行業趨勢與統計數據以及成長預測(2026-2031 年)英國瓦楞紙包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 2026年全球紙本拉環郵件市場報告
 瓦楞紙板包裝市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 瓦楞紙板包裝市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年
 2032 年瓦楞包裝市場預測:按類型、材料類型、瓦楞類型、包裝類型、應用、最終用戶和地區進行的全球分析瓦楞包裝市場:依類型、最終用戶行業和地區,2026年至2032年