


 |
市場調查報告書
商品編碼
2122401
豪華車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Luxury Car - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
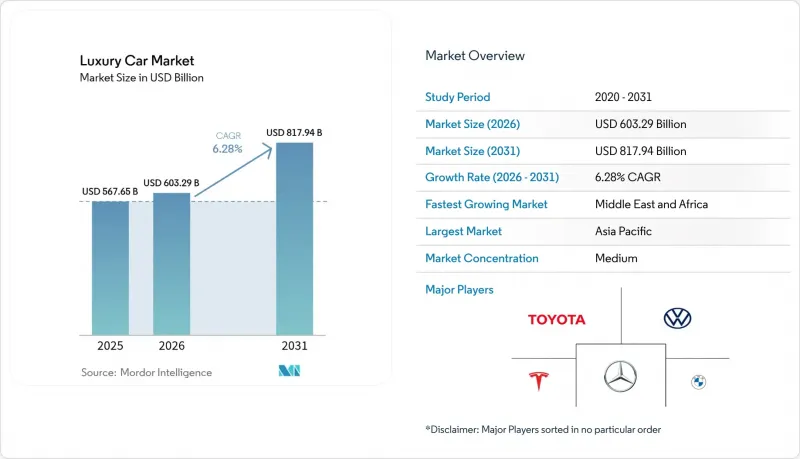
根據 Mordor Intelligence 預測,豪華車市場規模將從 2025 年的 5,676.5 億美元成長到 2026 年的 6,032.9 億美元,然後在 2031 年達到 8,179.4 億美元,2026 年至 2031 年的複合年成長率為 6.28%。
本報告按車輛類型(掀背車、轎車、運動型多用途車 (SUV)、其他)、驅動方式(內燃機 (ICE)、其他)、車輛等級(入門級豪華車、其他)、銷售管道(授權經銷商、直銷/線上)和地區進行分類。市場預測以價值(美元)和銷售(輛)為單位呈現。
全球豪華車市場的趨勢與洞察
高階車型快速電氣化
電池式電動車(BEV)是成長最快的動力系統。這主要得益於高階汽車製造商將電動車定位為“領頭羊車型”,不僅將其視為符合監管規定的手段,更強調其靜謐性、扭矩和最尖端科技。在印度,梅賽德斯-賓士電動車的銷量在截至2024年5月的一年中同比成長了94%,這主要得益於本地生產的EQS 580 SUV。同年,BMW在印度售出了1,249輛純電動車,並透過在51個城市安裝快速充電樁來提升銷量。超豪華品牌則保持謹慎。阿斯頓馬丁已將其首款電動車的發布推遲至2026年,以便進一步完善其動力傳動系統。法拉利已申請一項合成排氣聲浪的專利,旨在即使在靜謐的動力傳動系統中也能保持情感吸引力。在豪華車市場,品牌能否維持其獨特的品牌形象——例如「聲浪」、「乘坐舒適性」和「精湛工藝」——很可能成為衡量電動化成功與否的關鍵標準。
亞洲和中東地區高淨值人群的成長
亞太地區的豪華車市場正經歷快速成長,這主要得益於富裕人群基本客群的不斷擴大。隨著資產水準的提高,首次購車者和考慮更換的消費者對高階出行的需求日益成長。印度在其中扮演關鍵角色,近年來其豪華車銷量加倍。預測顯示,超級富豪階級將持續成長,這表明消費者正轉向“追求品質的消費”,並預示著市場長期前景光明。
在沿岸地區,原油價格飆升推高了居民可支配收入,刺激了對豪華車的強勁需求。 BMW等品牌銷售量顯著成長,凸顯了該地區對豪華車的熱情。經濟韌性和對豪華車的偏好相結合,鞏固了沿岸地區作為豪華車製造商主要市場的地位。
供不應求
儘管新的晶圓製造工廠已於2022年開始運作以應對半導體短缺問題,但用於汽車應用的專用微控制器供應仍然緊張。對於資訊娛樂和舒適系統等關鍵組件而言,這種情況尤其明顯。因此,豪華汽車製造商面臨艱難的選擇:交付缺少某些功能的車輛,要么延遲向客戶交付。
例如,以梅賽德斯-奔馳為例。這家豪華汽車製造商最近不得不推遲其旗艦車型S級的交付。這凸顯出,即使是精英車型也無法免受半導體短缺的影響。此類中斷對產量較小、配備更先進設備的豪華汽車打擊最大。這些依賴專用零件的車型,生產調整的空間有限。
細分市場分析
預計到2025年,SUV將佔豪華車市場的55.78%,並將以7.84%的複合年成長率持續成長至2031年。賓士的SUV產品線銷量屢創新高,其中AMG G 63在上市首日便收到超過120份領先單。轎車在專車服務市場和某些超豪華細分市場中仍然保持著一定的市場地位。然而,隨著年輕車主更加重視SUV的多功能性,轎車的相對市場佔有率正在萎縮。入門級豪華掀背車和MPV仍然是市場中的小眾車型,主要集中在特定地區;而超級跑車儘管銷售不高,仍然是支撐品牌吸引力的重要支柱。 SUV的強勁成長勢頭表明,在可預見的未來,SUV車型將繼續鞏固其作為豪華車市場最大利潤來源的地位。
目前,研發重點主要圍繞在SUV產品藍圖。奧迪正將研發資源從其旗艦車型PPE電動車轉移到Q6 e-tron,以期在與寶馬iX和賓士EQS等SUV的競爭中佔據優勢。路虎正在擴建其「SV Bespoke」客製化工作室,以滿足探測車車主對獨特材質和顏色選擇的需求,進一步推動了上述大規模客製化的趨勢。隨著排放氣體法規的日益嚴格,電動SUV車型正逐漸成為一種合規的標配,而非小眾衍生產品,預計豪華車市場將繼續保持SUV主導的成長動能。
即使到了2025年,內燃機(ICE)車型仍佔據豪華車市場68.35%的佔有率,但電池式電動車(BEV)的市場佔有率正以8.79%的複合年成長率快速成長。梅賽德斯-奔馳和寶馬已在其主要車型中全面採用400伏架構,而保時捷則已凍結2027年後對新型內燃機平台的投資。在快速充電基礎設施尚未完善的地區,混合動力汽車扮演著過渡角色。雷克薩斯在中國推出LM MPV後,混合動力汽車的需求顯著成長。超豪華品牌傾向於分階段推出。阿斯頓馬丁已將其首款電動車的發布推遲至2026年,理由是需要進一步提升乘坐舒適性和車廂聲學性能。動力傳動系統多元化在平衡監管要求、基礎設施建設和品牌傳承方面面臨嚴峻挑戰,但從長遠來看,電氣化將成為豪華車市場的主流。
專用電動平台也有助於實現軟體定義的內裝。特斯拉憑藉其自動研發的晶片組和不斷升級的全自動駕駛功能,在高階電動車市場樹立了品牌認知度的主導,這促使其競爭對手進行更深層的垂直整合。梅賽德斯-奔馳的「MB.OS」系統計劃從2025年起推廣至所有EQ車型,透過付費的空中下載(OTA)升級,該系統預計將在四年周期內為每輛車增加1200美元的收入。這種數位化獲利模式進一步強化了加速擴大電池式電動車(BEV)市場佔有率的合理性。
區域分析
預計到2025年,亞太地區將佔據豪華車市場42.75%的佔有率。這主要得益於中國市場的龐大規模以及印度高階汽車銷量的快速成長,預計印度高階汽車銷量將達到5萬輛(相當於每小時6輛)。梅賽德斯-奔馳警告稱,由於股市波動,2025年第一季的出貨量可能會放緩,這凸顯了該地區對資本市場波動的敏感性。隨著新能源汽車滲透率超過40.9%,中國本土品牌正在蠶食德國的市場佔有率,迫使現有製造商尋求技術合作並進行品牌訊息在地化。
預計到2031年,中東地區將維持最高的年複合成長率(CAGR),達到7.96%,這主要得益於與油價相關的可支配收入以及基礎設施建設的不斷擴張。 BMW在2024年海灣合作理事會(GCC)國家的銷售量成長了15.4%,這主要得益於X7和7系列車型的需求。阿拉伯聯合大公國的汽車總銷量成長了15.7%,印證了強勁的宏觀經濟環境帶來的利多。南非和土耳其的銷售量成長穩定,但外匯波動可能會影響消費者的購買決策。豪華汽車製造商正透過建立區域生產基地和提供美元結算選項來降低這些風險。
北美市場雖然已趨於成熟,但仍是豪華車市場的穩定支柱,富裕消費者的存在抵消了利率上升帶來的日益沉重的還款負擔。在加拿大,資源收入的激增正在推動豪華車的普及;而在墨西哥,中產階級資產的成長和信貸管道的改善正在推動消費者轉向高階車型。歐洲面臨最嚴格的監管限制,包括歐7排放標準和車隊二氧化碳排放的罰款,但仍保持強大的品牌忠誠度。汽車製造商正專注於高利潤的電動SUV以抵消合規成本,並透過利用自有電池工廠和可再生能源信用額度來保障盈利。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 豪華SUV需求激增
- 高階車型快速電氣化
- 亞洲和中東地區高淨值人群的成長
- 先進的ADAS系統和日益成長的安全期望
- 零售業向線上和D2C(直接面對消費者)銷售模式的轉變
- 大規模客製化和個人化選項
- 市場限制因素
- 高額的購置和擁有成本
- 供不應求
- 宏觀經濟需求波動
- SUV面臨的環境監管壓力
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按車輛類型
- 掀背車
- 轎車
- 運動型多用途車(SUV)
- 多用途汽車(MPV)
- 體育與異國情調
- 透過驅動系統
- 內燃機(ICE)
- 油電混合車
- 電池電動車
- 按車輛類別
- 入門豪華車
- 中檔豪華車
- 超豪華異國跑車
- 按銷售管道
- 授權經銷商
- 直接面對消費者 (D2C) / 在線
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Mercedes-Benz Group AG
- BMW AG
- Volkswagen Group
- Toyota Motor Corporation(Lexus)
- Jaguar Land Rover Automotive PLC
- Stellantis NV(Maserati, Alfa Romeo)
- Tesla Inc.
- Volvo Car Group
- Hyundai Motor Group(Genesis)
- Nissan Motor Co.(Infiniti)
- Geely Holding(Lotus, Zeekr)
- FAW Group(Hongqi)
- SAIC Motor(IM, Roewe)
- BYD Co.(Yangwang)
- Lucid Group
- Rivian Automotive
- Ferrari NV
- Aston Martin Lagonda
- Rolls-Royce Motor Cars
- McLaren Automotive
第7章 市場機會與未來展望
According to Mordor Intelligence, the luxury car market size is expected to grow from USD 567.65 billion in 2025 to USD 603.29 billion in 2026 and is forecast to reach USD 817.94 billion by 2031 at 6.28% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Hatchbacks, Sedans, Sports Utility Vehicles, and More), Drive Type (Internal Combustion Engine, and More), Vehicle Class (Entry-Level Luxury, and More), Sales Channel (Authorized Dealership and Direct-to-Consumer/Online), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Luxury Car Market Trends and Insights
Rapid Electrification of Premium Models
Battery-electric derivatives represent the fastest-growing drivetrain, supported by premium makers that position EVs as halo showcases for quiet torque and cutting-edge tech rather than regulatory compliance plays. In India, Mercedes-Benz's EV sales grew 94% year-on-year through May 2024, led by the locally-built EQS 580 SUV. BMW delivered 1,249 pure EVs in India the same year, supporting them with fast chargers in 51 cities. Ultra-luxury brands remain cautious: Aston Martin shifted its first EV launch to 2026 for additional powertrain refinement. Ferrari filed patents for synthetic exhaust acoustics to retain emotional appeal in silent drivetrains. The luxury car market will increasingly judge electrification success on how well brands preserve identity traits such as sound, ride, and craftsmanship.
Rising HNWI Population in Asia and Middle East
Asia-Pacific's luxury vehicle market is surging, driven by an expanding base of affluent consumers. As wealth levels rise, especially among first-time buyers and those seeking upgrades, the demand for premium mobility intensifies. India is a pivotal player, with luxury vehicle sales doubling in recent years. Projections show a continued rise in ultra-high-net-worth individuals, hinting at a shift towards aspirational consumption and a promising long-term market outlook.
In the Gulf region, buoyant oil prices have bolstered disposable incomes, fueling a robust demand for luxury vehicles. Brands such as BMW have grown significantly, underscoring the region's enthusiasm for premium automotive offerings. With a blend of economic resilience and a penchant for high-end mobility, the Gulf solidifies its status as a prime market for luxury OEMs.
Semiconductor and Component Shortages
Even with new wafer fabrication facilities launching post the 2022 chip shortage, there's still a tight supply of specialty automotive microcontrollers. This is especially true for those integral to infotainment and comfort systems. As a result, premium OEMs face tough choices: they deliver vehicles missing certain features or push back customer handovers.
Take Mercedes-Benz, for instance. The luxury automaker recently had to delay allocations of its flagship S-Class, underscoring that even elite models aren't shielded from these chip shortages. Such disruptions hit hardest in low-volume, high-content luxury vehicles. These models, dependent on specialized components, have limited leeway in production adjustments.
Other drivers and restraints analyzed in the detailed report include:
- Enhanced ADAS and Safety Expectations
- Online/Direct-to-Consumer Retail Shift
- Anti-SUV Climate Regulation Pressure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SUVs controlled 55.78% of the luxury car market size in 2025 and are predicted to post an 7.84% CAGR to 2031. Mercedes-Benz's SUV roster secured record revenue and over 120 early orders for the AMG G 63 on its first retail day. Sedans keep cultural cachet in chauffeur-driven contexts and certain ultra-luxury niches; however, their relative share diminishes as younger owners prioritize the multi-utility profile of SUVs. Entry-luxury hatchbacks and MPVs remain minor, geography-specific plays, while supercars anchor brand desirability despite negligible volume. Ferocious SUV momentum cements the body style as the luxury car market's leading profit contributor for the foreseeable horizon.
SUV-centric product roadmaps now dominate R&D prioritization. Audi moved flagship PPE EV development resources toward its Q6 e-tron to pre-empt BMW iX and Mercedes EQS SUV launches. Land Rover is extending its SV Bespoke studio to cater to Range Rover clients seeking one-off materials and colorways, reinforcing the mass-customization uptick discussed earlier. As emission targets tighten, electrified SUV variants will become the default compliance strategy rather than a niche derivative, keeping the luxury car market on an SUV-led growth trajectory.
Internal-combustion models still represented 68.35% of the luxury car market size in 2025, but battery-electric entries are sprinting ahead at a 8.79% CAGR. Mercedes-Benz and BMW have already mainstreamed 400-volt architectures into core models, and Porsche has frozen new ICE platform investment beyond 2027. Hybrids offer a transitional buffer in regions lacking fast-charging density; Lexus saw a hybrid uptake for its LM minivan launch in China. Ultra-luxury marques favor a staggered roll-in; Aston Martin rescheduled its debut EV to 2026, arguing for additional refinement of ride and cabin sound characteristics. Powertrain diversification remains a balancing act between regulatory compulsion, infrastructure readiness, and brand heritage yet the long arc points toward electrified dominance within the luxury car market.
Electric-only skateboards also facilitate software-defined interiors. Tesla commands premium-EV mindshare via in-house chipsets and full-self-driving updates, nudging rivals toward deeper vertical integration. Mercedes' MB.OS will roll out across all EQ models after 2025, enabling paid feature over-the-air upgrades that could lift revenue per vehicle by USD 1,200 over a four-year cycle. Such digital monetization strengthens the rationale for accelerated BEV share gains.
Complete Report Scope:
- By Vehicle Type
- Hatchbacks
- Sedans
- Sports Utility Vehicles (SUVs)
- Multi-purpose Vehicles (MPVs)
- Sports / Exotic
- By Drive Type
- Internal Combustion Engine (ICE)
- Hybrid Electric
- Battery Electric
- By Vehicle Class
- Entry-level Luxury
- Mid-level Luxury
- Ultra-luxury / Exotic
- By Sales Channel
- Authorized Dealership
- Direct-to-Consumer / Online
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle-East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific commanded 42.75% of the luxury car market share in 2025, underpinned by China's scale and India's meteoric rise to 50,000 premium units sold, equal to six vehicles every hour. Nevertheless, Mercedes-Benz warned of softer Q1 2025 deliveries amid equity volatility, validating the region's sensitivity to capital-market swings. China's domestic marques erode German share as NEV penetration tops 40.9%, pressuring incumbents to localize tech partnerships and brand messaging.
The Middle East shows the steepest 7.96% CAGR through 2031, buoyed by oil-linked disposable income and infrastructure expansion. BMW tallied a 15.4% volume uplift across Gulf Cooperation Council states 2024, led by X7 and 7 Series demand. UAE total automotive sales advanced 15.7%, confirming robust macro tailwinds. South Africa and Turkiye add incremental gains but are subject to currency gyrations that can delay purchase decisions; premium makers mitigate risk with regional production hubs and U.S.-dollar invoicing options.
North America remains a mature but steady pillar for the luxury car market, with affluent demographics offsetting interest-rate-driven payment inflation. Canada's resource windfall aids luxury penetration, while Mexico is graduating toward premium vehicles as rising middle-class wealth intersects with improved credit access. Europe faces the heaviest regulatory drag via Euro 7 and fleet CO2 fines, yet maintains entrenched brand loyalty. OEMs are converging on high-margin electric SUVs to absorb compliance costs, leveraging in-house battery plants and renewable-energy credits to defend profitability.
- Mercedes-Benz Group AG
- BMW AG
- Volkswagen Group
- Toyota Motor Corporation (Lexus)
- Jaguar Land Rover Automotive PLC
- Stellantis NV (Maserati, Alfa Romeo)
- Tesla Inc.
- Volvo Car Group
- Hyundai Motor Group (Genesis)
- Nissan Motor Co. (Infiniti)
- Geely Holding (Lotus, Zeekr)
- FAW Group (Hongqi)
- SAIC Motor (IM, Roewe)
- BYD Co. (Yangwang)
- Lucid Group
- Rivian Automotive
- Ferrari NV
- Aston Martin Lagonda
- Rolls-Royce Motor Cars
- McLaren Automotive
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Luxury-SUV Demand Boom
- 4.2.2 Rapid Electrification of Premium Models
- 4.2.3 Rising HNWI Population in Asia and Middle East
- 4.2.4 Enhanced ADAS and Safety Expectations
- 4.2.5 Online/Direct-To-Consumer Retail Shift
- 4.2.6 Mass-Customization and Bespoke Options
- 4.3 Market Restraints
- 4.3.1 High Purchase and Ownership Cost
- 4.3.2 Semiconductor and Component Shortages
- 4.3.3 Macroeconomic Demand Volatility
- 4.3.4 Anti-SUV Climate Regulation Pressure
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD), Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Hatchbacks
- 5.1.2 Sedans
- 5.1.3 Sports Utility Vehicles (SUVs)
- 5.1.4 Multi-purpose Vehicles (MPVs)
- 5.1.5 Sports / Exotic
- 5.2 By Drive Type
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Hybrid Electric
- 5.2.3 Battery Electric
- 5.3 By Vehicle Class
- 5.3.1 Entry-level Luxury
- 5.3.2 Mid-level Luxury
- 5.3.3 Ultra-luxury / Exotic
- 5.4 By Sales Channel
- 5.4.1 Authorized Dealership
- 5.4.2 Direct-to-Consumer / Online
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle-East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Mercedes-Benz Group AG
- 6.4.2 BMW AG
- 6.4.3 Volkswagen Group
- 6.4.4 Toyota Motor Corporation (Lexus)
- 6.4.5 Jaguar Land Rover Automotive PLC
- 6.4.6 Stellantis NV (Maserati, Alfa Romeo)
- 6.4.7 Tesla Inc.
- 6.4.8 Volvo Car Group
- 6.4.9 Hyundai Motor Group (Genesis)
- 6.4.10 Nissan Motor Co. (Infiniti)
- 6.4.11 Geely Holding (Lotus, Zeekr)
- 6.4.12 FAW Group (Hongqi)
- 6.4.13 SAIC Motor (IM, Roewe)
- 6.4.14 BYD Co. (Yangwang)
- 6.4.15 Lucid Group
- 6.4.16 Rivian Automotive
- 6.4.17 Ferrari NV
- 6.4.18 Aston Martin Lagonda
- 6.4.19 Rolls-Royce Motor Cars
- 6.4.20 McLaren Automotive
7 Market Opportunities & Future Outlook

 高階和豪華汽車市場機會、成長要素、產業趨勢分析以及 2026-2035 年預測。
 北美豪華車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 豪華車市場規模、佔有率、成長、全球產業分析、區域洞察及預測(2026-2034 年)印度豪華車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 2026年全球豪華車軟管市場報告
 2026-2030年全球豪華車市場2026年全球豪華穹頂車旅遊市場報告2026年全球豪華車市場報告
 豪華車市場規模、佔有率和趨勢分析報告:按車輛類型、驅動方式、地區和細分市場分類的預測(2026-2033 年)
 豪華車市場規模、佔有率、趨勢及報告:按車型、燃料類型、價格範圍和地區分類(2026-2034 年)