


 |
市場調查報告書
商品編碼
2121088
高階和豪華汽車市場機會、成長要素、產業趨勢分析以及 2026-2035 年預測。Premium and Luxury Vehicle Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球高階及豪華汽車市場預計到 2025 年將達到 5,295 億美元,年複合成長率為 4.3%,到 2035 年將達到 7,744 億美元。
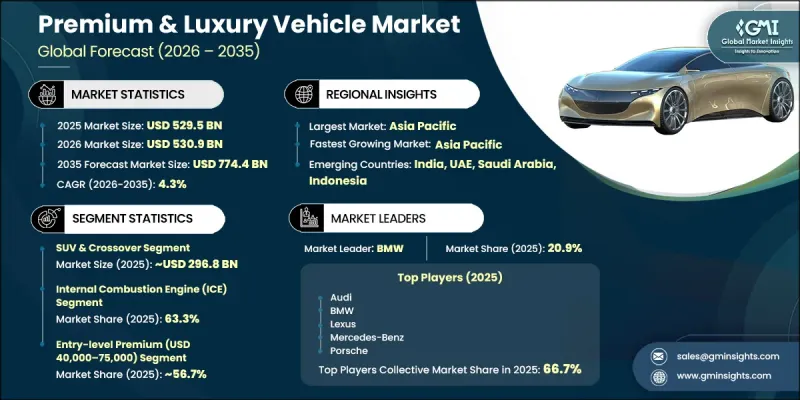
全球高階及豪華汽車市場正在超越傳統的車輛性能、工程品質和動力技術等評估標準。現代競爭越來越依賴製造商提供先進的數位體驗、智慧軟體功能、互聯出行解決方案以及貫穿車輛整個生命週期的長期價值的能力。電池創新、軟體定義車輛架構、空中下載 (OTA) 軟體更新、連網生態系統和新一代數位駕駛座技術是高階汽車開發的關鍵要素。隨著汽車技術的不斷進步,軟體整合和人工智慧在塑造未來出行解決方案和客戶體驗方面發揮著日益重要的作用。汽車製造商正擴大建立專有數位平台,以增強車輛功能、實現持續的功能升級並創造新的售後商機。這種轉型正在推動高階及豪華汽車製造商提升軟體能力,同時保持高品質、精湛工藝、創新和品牌價值,而這些正是全球高階汽車產業持續發展的基石。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 5295億美元 |
| 預測金額 | 7744億美元 |
| 複合年成長率 | 4.3% |
為了保持競爭力,高階和豪華汽車製造商不斷增加對研發、車輛電氣化、數位轉型和先進安全技術的投入。他們透過推出性能更佳、技術更先進、內裝更精緻、互聯性更強、並擁有更豐富電動動力傳動系統的升級車型,不斷強化現有產品系列。這種持續的產品革新使高階汽車品牌能夠滿足不斷變化的消費者期望,並增強其在全球市場的競爭力。
SUV和跨界車細分市場佔56.1%的市場佔有率,預計到2025年銷售額將達到2,968億美元。該細分市場之所以能夠保持領先地位,主要得益於消費者對兼具寬敞內部空間、先進技術和電動動力傳動系統潛力的優質多功能車的強勁需求。這種車身形式在整合式大容量電池系統、高級內裝配置和先進電子設備方面具有更大的柔軟性,同時還能滿足豪華車買家對實用性和舒適性的期望。這些優勢確保了該細分市場將繼續為整體市場銷售做出重大貢獻。
預計到2025年,入門級豪華車市場(40,000美元至75,000美元)將佔56.7%的市場佔有率。這個價格區間吸引了豪華車行業最大的基本客群,因為它為消費者提供了一個經濟實惠的豪華車入門途徑。然而,該細分市場的購車決策仍深受融資條件、利率、稅收和整體承受能力的影響,因此對整體經濟環境的變化尤其敏感。
美國高階及豪華車市場預計到2025年將達到1,135億美元,並在2026年至2035年間以3.1%的複合年成長率成長。美國仍然是高階及豪華車領域最大的市場之一,這得益於消費者強勁的購買力、對高階SUV和高性能汽車的持續需求,以及豪華電動車日益普及。科技的不斷進步、可支配收入的成長以及消費者對先進出行解決方案的日益偏好,將繼續推動美國市場的擴張。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 超級富豪階級(UHNWI)和富裕階層的人口成長。
- 擴大豪華電動車產品線
- 對個人化和客製化車輛的需求日益成長
- 新興豪華車市場的快速成長
- 產業潛在風險與挑戰
- 通貨膨脹、奢侈稅以及確保可負擔性方面的挑戰
- 半導體和原料供應受限
- 市場機遇
- 軟體定義汽車(SDV)的商機
- 超豪華和客製化市場的成長
- 豪華訂閱和公寓所有權模式
- 促進因素
- 技術與創新展望
- 最新科技趨勢
- 高級駕駛輔助系統(ADAS)
- 聯網汽車和遠端資訊處理系統
- 新興技術
- 軟體定義車輛(SDV)
- 人工智慧驅動的數位駕駛座和生成式人工智慧助手
- 最新科技趨勢
- 成長潛力分析
- 價格分析,2022-2035年
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國 - NHTSA(國家公路交通安全管理局)
- 加拿大 - 加拿大運輸部
- 歐洲
- 歐盟-歐洲委員會(國內貿易總司)
- 德國 - KBA(聯邦機動車輛管理局)
- 亞太地區
- 中國 - 工業及資訊化部(工信部)
- 印度 - 道路運輸部 (MoRTH) / ARAI
- LATAM
- 巴西 - SENATRAN
- 阿根廷 - ANSV(Agencia Nacional de Seguridad Vial)
- 中東和非洲
- 阿拉伯聯合大公國工業和先進技術部
- 沙烏地阿拉伯 - 沙烏地阿拉伯標準、計量和品質組織
- 北美洲
- 波特的分析
- PESTLE分析
- 2025年成本細分分析
- 專利分析
- 貿易數據分析
- 2022-2025年進出口數量及價值趨勢
- 主要貿易路線及關稅的影響
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類,2025 年
- 運轉率和擴張計劃
- 聯網汽車和軟體生態系統
- 車上用軟體架構與OTA更新功能
- V2X連線標準及應用趨勢
- 豪華汽車製造商的數位服務平台和訂閱模式
- 互聯高階汽車的網路安全現狀
- 主要汽車製造商的自動駕駛汽車產品平臺(2026-2035 年)
- 已確定發布日期的車型,按自動駕駛等級(L2-L5)分類,2026-2030 年
- OEM研發藍圖
- 區域監理核准流程
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 前十強企業的生產與銷售分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與選擇標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估價與預測:依車輛類型分類,2022-2035年
- 轎車
- 豪華轎車
- SUV 與跨界車
- 小轎車
- 敞篷車
- 跑車和超級跑車
- 豪華皮卡
- 其他
第6章 市場估計與預測:以推進方式分類,2022-2035年
- 內燃機(ICE)
- 電的
- 電池式電動車(BEV)
- 混合動力電動車(HEV)
- 插電式混合動力車(PHEV)
- 燃料電池電動車(FCEV)
第7章 市場估價與預測:依車輛類型分類,2022-2035年
- 入門保費(40,000美元至75,000美元)
- 中檔豪華(75,000美元至150,000美元)
- 高階奢侈品(15萬美元至30萬美元)
- 超豪華/訂製(超過30萬美元)
第8章 市場估算與預測:依自動駕駛等級分類,2022-2035年
- 0級和1級
- 二級
- 3級
- 4級
- 5級
第9章 市場估計與預測:依最終用途分類,2022-2035年
- 個人/面向個人
- 企業用車
- 租車及司機服務
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 瑞典
- 挪威
- 丹麥
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 新加坡
- 紐西蘭
- 印尼
- 泰國
- 越南
- 拉丁美洲
- 巴西
- 墨西哥
- 智利
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 世界公司
- Ferrari
- Mercedes-Benz
- BMW
- Porsche
- McLaren
- Bugatti Automobiles
- Jaguar Land Rover(JLR)
- Audi
- Bentley Motors
- Lamborghini
- Volvo Cars
- Lexus
- 當地公司
- Lincoln
- Acura
- Genesis
- DS Automobiles
- Alpine
- 新興企業
- Lotus Cars
- Zeekr
- Lucid
The Global Premium & Luxury Vehicle Market was valued at USD 529.5 billion in 2025 and is estimated to grow at a CAGR of 4.3% to reach USD 774.4 billion by 2035.
The global premium & luxury vehicle market is evolving beyond traditional measures such as vehicle performance, engineering quality, and propulsion technology. Modern competition increasingly depends on manufacturers' ability to deliver advanced digital experiences, intelligent software capabilities, connected mobility solutions, and long-term value throughout the vehicle ownership cycle. Battery innovation, software-defined vehicle architectures, over-the-air software updates, connected ecosystems, and next-generation digital cockpit technologies have become essential components of premium vehicle development. As automotive technology continues to advance, software integration and artificial intelligence are playing a larger role in shaping future mobility solutions and customer experiences. Vehicle manufacturers are increasingly building proprietary digital platforms that enhance vehicle functionality, enable continuous feature upgrades, and create new post-sale revenue opportunities. This transformation is encouraging premium and luxury automakers to strengthen their software capabilities while maintaining the high levels of quality, craftsmanship, innovation, and brand value that continue to define the global premium automotive industry.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $529.5 Billion |
| Forecast Value | $774.4 Billion |
| CAGR | 4.3% |
Manufacturers operating in the premium & luxury vehicle market continue to increase investments in research and development, vehicle electrification, digital transformation, and advanced safety technologies to remain competitive. Companies are consistently enhancing their existing product portfolios by introducing upgraded vehicle models equipped with improved performance, more sophisticated technologies, refined interiors, enhanced connectivity, and expanded electric powertrain offerings. This continuous product evolution allows premium automotive brands to address changing consumer expectations while strengthening their competitive position across global markets.
The SUV & crossover segment held a 56.1% share, generating USD 296.8 billion in 2025. This vehicle category maintained its leadership due to strong consumer demand for premium utility vehicles that combine spacious interiors, advanced technologies, and electrified powertrain compatibility. The body style provides greater flexibility for integrating larger battery systems, premium cabin features, and advanced electronic technologies while preserving the practicality and comfort expected by luxury vehicle buyers. These advantages continue to support the segment's dominant contribution to overall market revenue.
The entry-level premium (USD 40,000-75,000) segment held a 56.7% share in 2025. This price category attracts the largest customer base within the premium vehicle industry by offering an accessible entry point into luxury ownership. However, purchasing decisions within this segment remain highly influenced by financing conditions, interest rates, taxation policies, and overall affordability, making it particularly sensitive to changes in the broader economic environment.
U.S. Premium & Luxury Vehicle Market reached USD 113.5 billion in 2025 and is anticipated to grow at a CAGR of 3.1% between 2026 and 2035. The United States continues to represent one of the largest markets for premium and luxury vehicles, supported by strong consumer purchasing power, sustained demand for premium utility vehicles and high-performance automobiles, and increasing adoption of luxury electric vehicles. Ongoing technological advancements, higher disposable incomes, and growing consumer preference for advanced mobility solutions continue to reinforce market expansion across the country.
Major companies operating in the global premium & luxury vehicle market include BMW, Mercedes-Benz, Audi, Porsche, Lexus, Ferrari, Lamborghini, Bentley, JLR, and Volvo Cars. Companies participating in the premium & luxury vehicle market are reinforcing their competitive position through continuous investments in electrification, software development, connected vehicle technologies, and advanced safety innovations. Manufacturers are prioritizing research and development to improve vehicle performance, digital functionality, battery technologies, and intelligent mobility solutions. They are also expanding proprietary software ecosystems and introducing software-defined vehicle platforms that enable over-the-air updates and long-term feature enhancements. Product portfolio expansion through upgraded vehicle launches, greater personalization options, and premium customer experiences remains another important strategy. In addition, companies are strengthening strategic partnerships across technology, semiconductor, and battery supply chains while increasing manufacturing efficiency, optimizing production capabilities, and expanding their presence in high-growth regional markets to improve long-term competitiveness and market share.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Vehicle Body
- 2.2.3 Propulsion
- 2.2.4 Vehicle Class
- 2.2.5 Autonomy Level
- 2.2.6 End-Use
- 2.3 TAM analysis, 2027-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising UHNWI & Affluent Population
- 3.2.1.2 Luxury EV Portfolio Expansion
- 3.2.1.3 Growing Demand for Personalization & Bespoke Vehicles
- 3.2.1.4 Rapid Growth in Emerging Luxury Automotive Markets
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Inflation, Luxury Taxes & Affordability Challenges
- 3.2.2.2 Semiconductor & Raw Material Supply Constraints
- 3.2.3 Market opportunities
- 3.2.3.1 Software-Defined Vehicle (SDV) Revenue Opportunities
- 3.2.3.2 Growth of the Ultra-Luxury & Bespoke Segment
- 3.2.3.3 Luxury Subscription & Fractional Ownership Models
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 Advanced Driver Assistance Systems (ADAS)
- 3.3.1.2 Connected Vehicle & Telematics Systems
- 3.3.2 Emerging technologies
- 3.3.2.1 Software-Defined Vehicles (SDVs)
- 3.3.2.2 AI-Driven Digital Cockpit & Generative AI Assistants
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Pricing Analysis, 2022-2035 (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 US - NHTSA (National Highway Traffic Safety Administration)
- 3.6.1.2 Canada - Transport Canada
- 3.6.2 Europe
- 3.6.2.1 EU - European Commission (DG GROW)
- 3.6.2.2 Germany - KBA (Kraftfahrt-Bundesamt)
- 3.6.3 Asia Pacific
- 3.6.3.1 China - Ministry of Industry and Information Technology (MIIT)
- 3.6.3.2 India - MoRTH / ARAI
- 3.6.4 LATAM
- 3.6.4.1 Brazil - SENATRAN
- 3.6.4.2 Argentina - ANSV (Agencia Nacional de Seguridad Vial)
- 3.6.5 MEA
- 3.6.5.1 UAE - MoIAT (Ministry of Industry and Advanced Technology)
- 3.6.5.2 Saudi Arabia - Saudi Standards, Metrology and Quality Organization
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Cost breakdown analysis, 2025
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Trade Data Analysis (Driven by Paid Database)
- 3.11.1 Import/Export Volume & Value Trends, 2022-2025
- 3.11.2 Key Trade Corridors & Tariff Impact
- 3.12 Capacity & Production Landscape (Driven by Primary Research)
- 3.12.1 Installed Capacity by Region & Key Producer, 2025
- 3.12.2 Capacity Utilization Rates & Expansion Pipelines
- 3.13 Connected Vehicle & Software Ecosystem
- 3.13.1 In-Vehicle Software Architecture & OTA Update Capabilities
- 3.13.2 V2X Connectivity Standards & Adoption Trends
- 3.13.3 Luxury OEM Digital Services Platforms & Subscription Models
- 3.13.4 Cybersecurity Landscape for Connected Premium Vehicles
- 3.14 Autonomous Vehicle Product Pipeline by Key OEMs, 2026–2035
- 3.14.1 Confirmed Model Launches by Autonomy Level (L2–L5), 2026-2030
- 3.14.2 OEM R&D Roadmaps
- 3.14.3 Regulatory Approval Pathways by Geography
- 3.15 Sustainability and environmental aspects
- 3.15.1 Sustainable practices
- 3.15.2 Waste reduction strategies
- 3.15.3 Energy efficiency in production
- 3.15.4 Eco-friendly Initiatives
- 3.15.5 Carbon footprint considerations
- 3.16 Impact of AI & generative AI on the market
- 3.16.1 AI-driven disruption of existing business models
- 3.16.2 GenAI use cases & adoption roadmap by segment
- 3.16.3 Risks, limitations & regulatory considerations
- 3.17 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.17.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.17.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.17.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company Market share analysis (value and volume), 2022-2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Top 10 Company production & sales analysis, 2022-2035
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans and funding
- 4.7 Company tier benchmarking
- 4.7.1 Tier classification criteria & qualifying thresholds
- 4.7.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Vehicle Body, 2022 – 2035 ($ Mn, Units)
- 5.1 Key trends
- 5.2 Sedan
- 5.3 Limousine
- 5.4 SUV & Crossover
- 5.5 Coupe
- 5.6 Convertible
- 5.7 Sports & Supercar
- 5.8 Luxury Pickup Truck
- 5.9 Others
Chapter 6 Market Estimates and Forecast, By Propulsion, 2022 – 2035 ($ Mn, Units)
- 6.1 Key trends
- 6.2 Internal Combustion Engine (ICE)
- 6.3 Electric
- 6.3.1 Battery Electric Vehicle (BEV)
- 6.3.2 Hybrid Electric Vehicle (HEV)
- 6.3.3 Plug-in Hybrid Electric Vehicle (PHEV)
- 6.3.4 Fuel Cell Electric Vehicle (FCEV)
Chapter 7 Market Estimates and Forecast, By Vehicle Class, 2022 – 2035 ($ Mn, Units)
- 7.1 Key trends
- 7.2 Entry-Level Premium (USD 40,000–75,000)
- 7.3 Mid-Level Luxury (USD 75,000–150,000)
- 7.4 High-End Luxury (USD 150,000–300,000)
- 7.5 Ultra-Luxury / Bespoke (USD 300,000+)
Chapter 8 Market Estimates and Forecast, By Autonomy Level, 2022 – 2035 ($ Mn, Units)
- 8.1 Key trends
- 8.2 Level 0 & Level 1
- 8.3 Level 2
- 8.4 Level 3
- 8.5 Level 4
- 8.6 Level 5
Chapter 9 Market Estimates and Forecast, By End-Use, 2022 – 2035 ($ Mn, Units)
- 9.1 Key trends
- 9.2 Individual / Personal
- 9.3 Corporate Fleet
- 9.4 Rental & Chauffeur Services
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Russia
- 10.3.7 Netherlands
- 10.3.8 Sweden
- 10.3.9 Norway
- 10.3.10 Denmark
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 South Korea
- 10.4.5 Australia
- 10.4.6 Singapore
- 10.4.7 New Zealand
- 10.4.8 Indonesia
- 10.4.9 Thailand
- 10.4.10 Vietnam
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Chile
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global players
- 11.1.1 Ferrari
- 11.1.2 Mercedes-Benz
- 11.1.3 BMW
- 11.1.4 Porsche
- 11.1.5 McLaren
- 11.1.6 Bugatti Automobiles
- 11.1.7 Jaguar Land Rover (JLR)
- 11.1.8 Audi
- 11.1.9 Bentley Motors
- 11.1.10 Lamborghini
- 11.1.11 Volvo Cars
- 11.1.12 Lexus
- 11.2 Regional players
- 11.2.1 Lincoln
- 11.2.2 Acura
- 11.2.3 Genesis
- 11.2.4 DS Automobiles
- 11.2.5 Alpine
- 11.3 Emerging players
- 11.3.1 Lotus Cars
- 11.3.2 Zeekr
- 11.3.3 Lucid

 北美豪華車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 豪華車市場規模、佔有率、成長、全球產業分析、區域洞察及預測(2026-2034 年)印度豪華車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)豪華車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026年全球豪華車軟管市場報告
 2026-2030年全球豪華車市場2026年全球豪華穹頂車旅遊市場報告2026年全球豪華車市場報告
 豪華車市場規模、佔有率和趨勢分析報告:按車輛類型、驅動方式、地區和細分市場分類的預測(2026-2033 年)
 豪華車市場規模、佔有率、趨勢及報告:按車型、燃料類型、價格範圍和地區分類(2026-2034 年)