


 |
市場調查報告書
商品編碼
2122170
印度鋰離子電池:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)India Lithium-ion Battery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
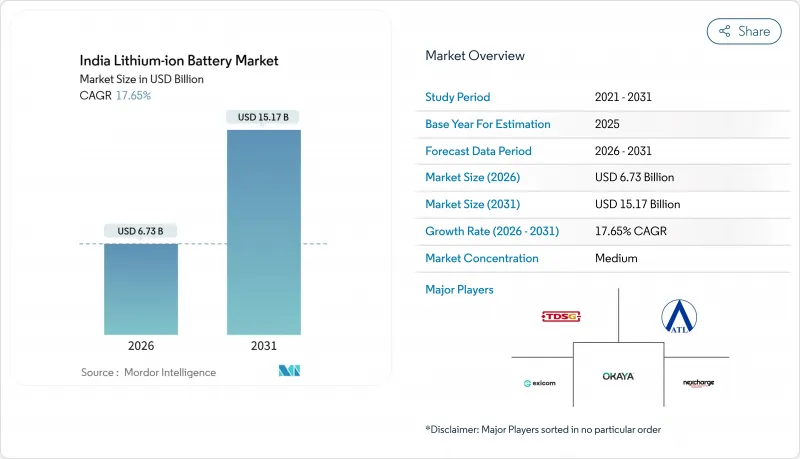
據 Mordor Intelligence 稱,印度鋰離子電池市場在 2026 年預計為 67.3 億美元,預計到 2031 年將達到 151.7 億美元,在預測期(2026-2031 年)內複合年成長率為 17.65%。
本報告按產品類型(LCO、LFP、NMC、NCA、LMO、LTO)、形狀(圓柱形、棱柱形、軟包)、容量(3000 mAh 以下、3000–10000 家用電子電器、10000–60000 mAh、60000 mAh)和航太終端產業市場規模和預測以美元計價。
印度鋰離子電池市場趨勢與洞察
鋰離子電池的成本曲線正在加速下降。
在印度,受原物料價格穩定和國內產能擴張的推動,電池組價格從2025年的每千瓦時132美元降至2025年的每千瓦時115美元。到2026年初,本地生產的NMC電池價格已降至每千瓦時95美元,即使加上運輸成本和消費稅,也幾乎與從中國進口的價格持平。價格的快速下降正在改變電動車的總擁有成本(TCO)格局,尤其是在對價格高度敏感的電動二輪車和三輪車領域。預計到2025年,磷酸鐵鋰電池(LFP)的需求量將佔22%,其能量密度比NMC電池低約15-20%,組件成本也低18-22%。此外,成本持平將使商業建築中4小時固定式系統的平準化發電成本低於柴油發電機,這將是2025年的里程碑式成就。
政府FAME-II補貼和PLI計劃
印度政府已撥款75億印度盧比(約9億美元)用於FAME-II獎勵,以支持電動摩托車和電動巴士的生產,目標是在2025年3月前實現120萬輛電動摩托車和1.8萬輛電動巴士的減價,減價幅度為25%至30%。該計劃的延期至2027年3月,將有助於最終確定需求預測,並幫助原始設備製造商(OEM)適應分階段的生產義務。為配合需求刺激計劃,ACC-PLI計劃已撥款1.81億印度盧比(約21.7億美元),旨在促進國內到2030年實現50吉瓦時的發電能力。 Reliance New Energy位於賈姆訥格爾的10吉瓦時電廠和Ola Electric位於泰米爾納德邦的20吉瓦時超級工廠是主要受益者,兩家公司分別獲得超過29億印度盧比(約3.5億美元)的獎勵。前五年適用的 20% 增值補貼,已將國產產品與進口產品的到岸成本差距縮小到 5% 以下,鼓勵主要汽車製造商決定實現在地化生產。
對重要礦產的進口依賴
印度計劃在2025年進口18,200噸鋰化合物(價值12億美元),其中68%來自中國,24%來自智利。其4800噸鈷進口幾乎全部來自剛果民主共和國,經由中國提煉轉運,凸顯了非金屬鈷(NMC)供應的單一來源風險。卡納塔克邦曼迪亞地區的探勘已確認鋰氧化物當量蘊藏量為14,100噸,但商業開採預計要到2028年才能開始。 「關鍵礦產任務」已撥款25億印度盧比(約3億美元)用於收購海外礦產權益,但在投產之前,電池製造商需要維持三個月的庫存以對沖風險,預計這將延長營運資金周轉週期。
細分市場分析
在印度鋰離子電池市場,NMC電池預計到2025年將達到18.7億美元,市佔率為33.3%。 LFP電池憑藉其卓越的循環壽命和無鈷設計,預計將以27.1%的複合年成長率成長。預計到2031年,LFP電池的市場佔有率將幾乎與NMC電池持平,尤其是在固定式儲能系統和商用電動車領域。 Exide Industries和Ola Electric都計劃在2027年將其購買量的60%替換為LFP電池。雖然NMC電池在續航里程超過400公里的豪華車市場仍佔據主導地位,但由於基於AIS-156標準的更嚴格的熱傳導測試,大眾市場車型正在逐步轉向LFP電池。 LTO和LMO等其他化學成分預計仍將保留在公車和電動工具等領域,在這些領域,快速充電和耐熱性比能量密度更為重要。
在印度鋰離子電池市場,由於印度太陽能公司(SECI)和印度國家電力公司(NTPC)出於安全性和壽命方面的考慮,強制競標使用鐵基化學成分的電池,預計磷酸鐵鋰(LFP)電池的佔有率將會縮小。消費性電子產品製造商仍然偏好高密度NMC和LCO電池,但隨著智慧型手機電池容量的增加,LCO電池的出貨量正在逐漸下降。Panasonic能源的NCA電池市場規模小規模,主要供應高階電動車,但由於成本和供應風險問題,其出貨量仍然很低。
預計到2025年,圓柱形電池將佔印度鋰離子電池市場31.3億美元的佔有率,達到55.8%。這得歸功於其成熟的供應鏈和自動化組裝。廣泛應用於Ather和Ola車輛的21700型電池,其能量密度比18650型電池高出35%,每千瓦時電池組成本降低了8-10%。目前,軟包電池的市佔率僅為16.2%,但隨著滑板式電動車平台對輕薄高容量模組的需求,預計其年複合成長率將達到24.3%。 LG能源解決方案公司位於浦那的工廠(產能5吉瓦時)計劃於2026年運作,預計將透過供應250瓦時/公斤的NMC軟包電池來推動這一成長趨勢。
為了避免印度夏季氣溫高達 45 度C導致的熱膨脹風險,提高冷卻性能至關重要。這會使軟包電池組的成本增加 20-30 美元/千瓦時,但 12-18% 的重量減輕對目標重量低於 100 公斤的摩托車製造商來說極具吸引力。棱柱形電池雖然成本高出 8-12%,但由於其易於機架安裝和與電池管理系統 (BMS) 整合,因此在固定式儲能市場佔據主導地位。比亞迪的刀片式電池技術因其結構整合優勢,正受到印度公車製造商的評估。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 鋰離子電池成本曲線的下降速度正在加快。
- 政府FAME-II補貼和PLI計劃
- 電動摩托車在都市區交通領域的蓬勃發展。
- 印度太陽能公司 (SECI) 和印度國家電力公司 (NTPC) 就電網級儲能競標。
- 基於「自力更生印度」政策的電池製造本地化
- 工商業領域公司購買可再生能源和儲能的購電協議(PPA)。
- 市場限制因素
- 對重要礦產的進口依賴
- 電池回收生態系統不發達
- 電池和包裝的消費稅差異很大。
- 安全和火災事故正在損害消費者的信任。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- PESTLE分析
第5章 市場規模與成長預測
- 依產品類型
- 鈷酸鋰(LCO)
- 磷酸鋰鐵(LFP)
- 鋰鎳錳鈷(NMC)
- 鋰鎳鈷鋁(NCA)
- 鋰錳氧化物(LMO)
- 鈦酸鋰(LTO)
- 按形狀
- 圓柱形
- 矩形的
- 小袋
- 按產能
- 3000毫安時或以下
- 3,000~10,000 mAh
- 10,000~60,000 mAh
- 60,000毫安培小時或以上
- 按最終用途行業分類
- 汽車(電動車、油電混合車、插電式油電混合車)
- 家用電子產品
- 工業和電動工具
- 固定式儲能
- 航太/國防
- 海上
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- TDS Lithium-Ion Battery Gujarat Pvt. Ltd.(TDSG)
- Nexcharge(Exide & Leclanche)
- Amperex Technology Ltd.(ATL)
- Exicom Tele-Systems Ltd.
- Okaya Power Group
- Amara Raja Energy & Mobility Ltd.
- Reliance New Energy Battery Storage Ltd.
- Tata AutoComp Systems Ltd.
- Panasonic Energy India
- LG Energy Solution(India)
- Future Hi-Tech Batteries
- Trontek Group
- Telemax India Industries
- Inverted Energy Pvt. Ltd.
- Vision Mechatronics Pvt. Ltd.
- iPower Batteries Pvt. Ltd.
- Bharat Electronics Ltd.(BEL)
- Ola Electric Mobility Pvt. Ltd.
- Sunlit Power(SUN Mobility)
- HBL Power Systems Ltd.
- Coslight India
- EON Electric Ltd.
- Toshiba Corporation
- Samsung SDI India
第7章 市場機會與未來展望
According to Mordor Intelligence, the India lithium-ion battery market size is estimated at USD 6.73 billion in 2026, and is expected to reach USD 15.17 billion by 2031, at a CAGR of 17.65% during the forecast period (2026-2031).
This report is Segmented by Product Type (LCO, LFP, NMC, NCA, LMO, LTO), Form Factor (Cylindrical, Prismatic, Pouch), Power Capacity (Up To 3, 000 MAh, 3, 000 To 10, 000 MAh, 10, 000 To 60, 000 MAh, Above 60, 000 MAh), and End-Use Industry (Automotive, Consumer Electronics, Industrial, Stationary Storage, Aerospace, Marine). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
India Lithium-ion Battery Market Trends and Insights
Declining Lithium-ion Battery Cost Curve Acceleration
Battery-pack prices in India fell to USD 115 per kWh in 2025 from USD 132 per kWh a year earlier as raw-material prices cooled and domestic scale improved. By early 2026, locally produced NMC cells cost USD 95 per kWh, almost matching imported Chinese equivalents once freight and GST are added. This rapid deflation is tipping total-cost-of-ownership equations in favor of electric two- and three-wheelers, where price sensitivity is high. LFP, representing 22% of 2025 demand, offers an 18-22% bill-of-materials discount over NMC, though its energy density is roughly 15-20% lower. Cost parity is also enabling 4-hour stationary systems to undercut diesel gensets on levelized cost in commercial buildings, a milestone crossed in 2025.
Government FAME-II Subsidies and PLI Schemes
The government disbursed INR 7,500 crore (USD 900 million) in FAME-II incentives by March 2025, underwriting 1.2 million electric two-wheelers and 18,000 e-buses and slicing sticker prices by 25-30%. Extension through March 2027 locks in demand visibility, helping OEMs align with phased manufacturing mandates. Complementing demand pull, the ACC-PLI program earmarked INR 18,100 crore (USD 2.17 billion) to catalyze 50 GWh of domestic capacity by 2030. Reliance New Energy's 10 GWh Jamnagar plant and Ola Electric's 20 GWh Tamil Nadu gigafactory headline the beneficiaries, each capturing more than INR 2,900 crore (USD 350 million) in incentives. The 20% value-addition subsidy during the first five years compresses the landed-cost gap with imports to below 5%, galvanizing localization decisions by major OEMs.
Critical-Mineral Import Dependence
India imported 18,200 t of lithium compounds worth USD 1.2 billion in 2025, with 68% dependent on China and 24% on Chile. Cobalt shipments of 4,800 t arrived almost exclusively via Chinese refineries sourcing from the Democratic Republic of Congo, exposing a single-node risk for NMC supply. Although exploratory finds in Karnataka's Mandya district indicate 14,100 t lithium oxide equivalent, commercial extraction is unlikely before 2028. The Critical Mineral Mission has earmarked INR 2,500 crore (USD 300 million) for overseas mine stakes, yet until operational, cell manufacturers will continue to hedge by stockpiling three-month inventories, inflating working-capital cycles.
Other drivers and restraints analyzed in the detailed report include:
- Electric Two-Wheeler Boom in Urban Mobility
- Grid-Scale Energy-Storage Tenders by SECI & NTPC
- Under-Developed Battery-Recycling Ecosystem
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
India's lithium-ion battery market size for NMC chemistry was USD 1.87 billion in 2025, equal to a 33.3% share. LFP's superior cycle life and cobalt-free design underpin its forecast 27.1% CAGR, propelling it to near-parity with NMC by 2031, especially in stationary storage and commercial EVs. Exide Industries and Ola Electric both aim to shift 60% of sourcing to LFP by 2027. Although NMC retains an edge in premium passenger cars demanding 400 km+ range, stricter thermal-propagation tests under AIS-156 tilt mass-market models toward LFP. Minor chemistries like LTO and LMO will remain niche, serving public buses and power tools where rapid charging and temperature resilience override energy density.
India's lithium-ion battery market share for LFP is projected to close the gap as SECI and NTPC tenders mandate iron-phosphate chemistry for safety and lifecycle reasons. Consumer-electronics OEMs still prefer high-density NMC and LCO cells, but rising smartphone battery capacities are gradually cannibalizing LCO volumes. Panasonic Energy's small NCA niche supplies luxury EVs, yet volumes stay marginal due to cost and supply-risk issues.
Cylindrical formats generated USD 3.13 billion of the India lithium-ion battery market size in 2025, equal to 55.8% share, reflecting deep legacy supply chains and automated assembly lines. The 21700 cell, widely used by Ather and Ola, delivers 35% more energy than 18650, lowering per-kWh pack cost by 8-10%. Pouch cells, while only 16.2% share now, are forecast to grow 24.3% CAGR as skateboard EV platforms demand thin, high-utilization modules. LG Energy Solution's 5 GWh Pune plant, due in 2026, will feed this trend with 250 Wh/kg NMC pouches.
Thermal-expansion risks in India's 45 °C summers necessitate enhanced cooling, adding USD 20-30 per kWh to pouch-pack costs, but weight savings of 12-18% are compelling for two-wheeler OEMs chasing sub-100 kg designs. Prismatic cells dominate stationary storage as they simplify racking and BMS integration, despite an 8-12% cost premium. BYD's blade battery technology is under evaluation by Indian bus OEMs for structural integration benefits.
Complete Report Scope:
- By Product Type
- Lithium Cobalt Oxide (LCO)
- Lithium Iron Phosphate (LFP)
- Lithium Nickel Manganese Cobalt (NMC)
- Lithium Nickel Cobalt Aluminium (NCA)
- Lithium Manganese Oxide (LMO)
- Lithium Titanate (LTO)
- By Form Factor
- Cylindrical
- Prismatic
- Pouch
- By Power Capacity
- Up to 3,000 mAh
- 3,000 to 10,000 mAh
- 10,000 to 60,000 mAh
- Above 60,000 mAh
- By End-use Industry
- Automotive (EV, HEV, PHEV)
- Consumer Electronics
- Industrial and Power Tools
- Stationary Energy Storage
- Aerospace and Defense
- Marine
List of Companies Covered in this Report:
- TDS Lithium-Ion Battery Gujarat Pvt. Ltd. (TDSG)
- Nexcharge (Exide & Leclanche)
- Amperex Technology Ltd. (ATL)
- Exicom Tele-Systems Ltd.
- Okaya Power Group
- Amara Raja Energy & Mobility Ltd.
- Reliance New Energy Battery Storage Ltd.
- Tata AutoComp Systems Ltd.
- Panasonic Energy India
- LG Energy Solution (India)
- Future Hi-Tech Batteries
- Trontek Group
- Telemax India Industries
- Inverted Energy Pvt. Ltd.
- Vision Mechatronics Pvt. Ltd.
- iPower Batteries Pvt. Ltd.
- Bharat Electronics Ltd. (BEL)
- Ola Electric Mobility Pvt. Ltd.
- Sunlit Power (SUN Mobility)
- HBL Power Systems Ltd.
- Coslight India
- EON Electric Ltd.
- Toshiba Corporation
- Samsung SDI India
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining lithium-ion battery cost curve acceleration
- 4.2.2 Government FAME-II subsidies and PLI schemes
- 4.2.3 Electric two-wheeler boom in urban mobility
- 4.2.4 Grid-scale energy-storage tenders by SECI & NTPC
- 4.2.5 Localization of cell manufacturing under "Atmanirbhar Bharat"
- 4.2.6 Corporate renewable + storage PPAs in C&I segment
- 4.3 Market Restraints
- 4.3.1 Critical-mineral import dependence
- 4.3.2 Under-developed battery-recycling ecosystem
- 4.3.3 High GST differential on cells vs. packs
- 4.3.4 Safety & fire incidents eroding consumer confidence
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Lithium Cobalt Oxide (LCO)
- 5.1.2 Lithium Iron Phosphate (LFP)
- 5.1.3 Lithium Nickel Manganese Cobalt (NMC)
- 5.1.4 Lithium Nickel Cobalt Aluminium (NCA)
- 5.1.5 Lithium Manganese Oxide (LMO)
- 5.1.6 Lithium Titanate (LTO)
- 5.2 By Form Factor
- 5.2.1 Cylindrical
- 5.2.2 Prismatic
- 5.2.3 Pouch
- 5.3 By Power Capacity
- 5.3.1 Up to 3,000 mAh
- 5.3.2 3,000 to 10,000 mAh
- 5.3.3 10,000 to 60,000 mAh
- 5.3.4 Above 60,000 mAh
- 5.4 By End-use Industry
- 5.4.1 Automotive (EV, HEV, PHEV)
- 5.4.2 Consumer Electronics
- 5.4.3 Industrial and Power Tools
- 5.4.4 Stationary Energy Storage
- 5.4.5 Aerospace and Defense
- 5.4.6 Marine
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 TDS Lithium-Ion Battery Gujarat Pvt. Ltd. (TDSG)
- 6.4.2 Nexcharge (Exide & Leclanche)
- 6.4.3 Amperex Technology Ltd. (ATL)
- 6.4.4 Exicom Tele-Systems Ltd.
- 6.4.5 Okaya Power Group
- 6.4.6 Amara Raja Energy & Mobility Ltd.
- 6.4.7 Reliance New Energy Battery Storage Ltd.
- 6.4.8 Tata AutoComp Systems Ltd.
- 6.4.9 Panasonic Energy India
- 6.4.10 LG Energy Solution (India)
- 6.4.11 Future Hi-Tech Batteries
- 6.4.12 Trontek Group
- 6.4.13 Telemax India Industries
- 6.4.14 Inverted Energy Pvt. Ltd.
- 6.4.15 Vision Mechatronics Pvt. Ltd.
- 6.4.16 iPower Batteries Pvt. Ltd.
- 6.4.17 Bharat Electronics Ltd. (BEL)
- 6.4.18 Ola Electric Mobility Pvt. Ltd.
- 6.4.19 Sunlit Power (SUN Mobility)
- 6.4.20 HBL Power Systems Ltd.
- 6.4.21 Coslight India
- 6.4.22 EON Electric Ltd.
- 6.4.23 Toshiba Corporation
- 6.4.24 Samsung SDI India
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment
- 7.2 Battery-recycling infrastructure scaling
- 7.3 Solid-state battery commercialization potential
- 7.4 Second-life battery leasing models
- 7.5 Local mineral processing & refining opportunities
- 7.6 Advanced BMS & thermal-management solutions

 2026-2034年全球液態鋰離子電池市場規模、佔有率、趨勢和成長分析報告2026-2034年全球鋰箔市場規模、佔有率、趨勢和成長分析報告
 東南亞鋰離子電池:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 鋰離子電池市場分析及預測至 2035 年:按類型、產品、技術、組件、應用、形式、材料類型、最終用戶、功能和安裝類型分類。
 鋰離子電池市場預測至 2034 年——按電池化學成分、組件、容量、電壓、外形尺寸、應用、最終用戶、銷售管道和地區進行全球分析。鋰離子電池:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)全球無鈷正極材料市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 鋰離子電池市場:2026-2032 年全球市場預測,依電池化學成分、電壓範圍、外形尺寸和應用細分。
 無鈷陰極材料市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 住宅鋰離子電池市場-全球產業規模、佔有率、趨勢、機會、預測:按類型和最終用途產業、地區和競爭格局分類,2021-2031年