


 |
市場調查報告書
商品編碼
2121979
平板玻璃:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Flat Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,平板玻璃市場規模預計將從 2025 年的 8,317 萬噸成長到 2026 年的 8,648 萬噸,並將從 2026 年到 2031 年以 3.98% 的複合年成長率成長,到 2031 年達到 1.0514 億噸。
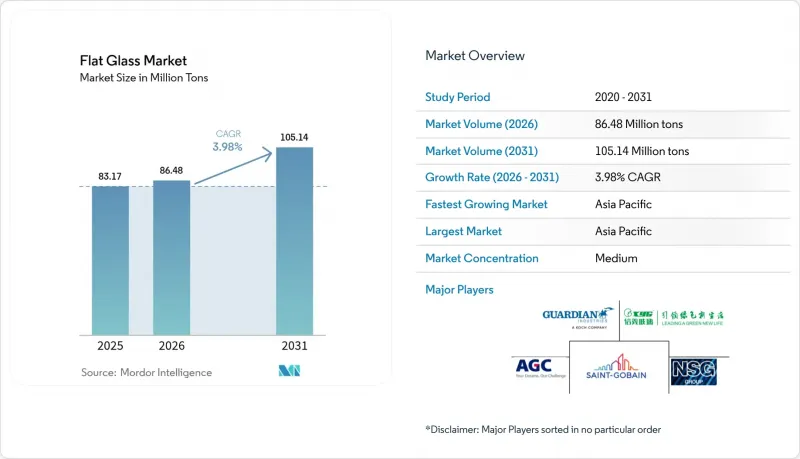
本報告按產品類型(退火玻璃、鍍膜玻璃、加工玻璃、鏡面玻璃、壓花玻璃)、終端用戶產業(建築、汽車、太陽能玻璃及其他終端用戶產業)和地區(亞太、北美、歐洲、南美以及中東和非洲)進行細分。市場預測以噸為單位。
全球平板玻璃市場趨勢及洞察
加大對商業和住宅建築的投資
受借貸成本下降和開發人員景氣增強的推動,全球建築支出預計將會增加。不斷上漲的居住成本,尤其是獨棟住宅的成本,正在加速多用戶住宅的建設,從而持續推動對採用低輻射鍍膜(Low-E)和三層玻璃的幕牆和窗戶系統的需求。開發商為了獲得LEED認證積分,正在指定使用高性能玻璃,這帶動了濺鍍膜和充氬氣隔熱產品的銷售成長。因此,平板玻璃市場正直接受益於建築規範中鼓勵採用先進玻璃解決方案的「窗牆比」要求。
為了提高電動車的安全性並減輕重量,對汽車玻璃的需求日益成長。
輕質玻璃對於電動車平台至關重要,能夠有效抵消電池重量,而結構玻璃的需求也不斷成長。福耀玻璃計劃於2024年投資91億元人民幣(約12.6億美元)新建兩座工廠,以滿足新能源車的需求。超薄夾層玻璃擋風玻璃、全景天窗以及相容抬頭顯示器的擋風玻璃等產品,正在擴大加工玻璃的市場滲透率。嵌入式感測器組件的加入,提升了單車附加價值,並在廣闊的平板玻璃市場中開闢了盈利成長點。透過減薄提升空氣動力性能,並進一步最佳化續航里程,鞏固了玻璃在預測期內作為關鍵減重材料的地位。
聚合物、丙烯酸和聚碳酸酯替代品的出現。
汽車製造商正在測試聚碳酸酯側窗和全景天窗,其重量比同類玻璃面板輕50%。雖然光學清晰度和抗紫外線性能有所提升,但其耐刮擦性和耐熱性仍不如玻璃。擋風玻璃的嚴格法規限制了聚碳酸酯的應用範圍,使其僅限於特定領域,替代風險主要集中在非承重玻璃。玻璃回收的優勢以及日益嚴格的報廢產品循環經濟目標,進一步支撐了平板玻璃的供應。
細分市場分析
從2026年到2031年,加工玻璃的複合年成長率(CAGR)最高,達到4.65%,超過了平板玻璃整體市場的成長。夾層玻璃和強化玻璃廣泛應用於汽車擋風玻璃、帷幕牆和安全外牆等領域,這些應用對抗衝擊性要求極高。截至2025年,退火玻璃仍佔市場總產量的79.62%,作為下游加工的基礎材料,在市場中佔據主導地位。儘管退火玻璃憑藉其成本優勢在建築業仍佔據核心地位,但隨著建築和安全標準日益嚴格,對增值加工的需求不斷成長,預計其市場佔有率將逐步下降。
強制性隔熱標準推動了鍍膜玻璃、反射玻璃和Low-E低輻射鍍膜玻璃的並行發展。 AGC Glass Europe 的低碳玻璃二氧化碳當量為 5.5 kg/m²,是產品差異化並因此獲得高價的典型案例。在電動車中使用有色玻璃有助於改善車廂冷卻效果和電池效率。雖然鏡面玻璃和圖案玻璃目前仍屬於小眾市場,但它們正逐漸成為室內裝潢和隱私保護應用的理想選擇。總體而言,專業化預計將推高平均售價,加工玻璃在預測期內預計將擴大其在平板玻璃市場的佔有率。
區域分析
預計到2025年,亞太地區將佔全球出貨量的63.88%,年複合成長率達4.63%,為所有地區中最高。在印度,根據旭硝子印度公司與INOX空氣產品公司簽署的為期20年的供應協議,綠色氫氣反應器的試運行正在進行中,同時新的浮法生產線建設也在穩步推進。
歐洲正致力於引領脫碳進程。在歐盟創新基金的支持下,聖戈班和AGC已開始測試混合反應器,該反應器將透過50%的電氣化和富氧燃燒,減少75%的二氧化碳排放。將於2026年生效的碳邊境調節機制(CBAM)附加稅可望鼓勵在地採購,並促進區域內銷售。北美製造商正在升級其生產線,以應對天然氣價格波動和環境、社會及公司治理(ESG)方面的審查,其中以Vitro公司1.8億美元的現代化改造和OI公司在英國的投資為代表。
儘管南美、中東和非洲的都市化正在推進,但這些地區面臨基礎設施短缺和亞洲進口產品的競爭。待開發區浮法玻璃專案仍然受到嚴格篩選,但當地建築商傾向於使用本地玻璃以避免運費,這推動了產量的逐步成長。總體而言,區域格局的變化意味著亞洲在生產佔有率方面仍然保持著不可撼動的地位,而其他地區則在平板玻璃市場尋求高附加價值的特殊產品。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大對商業和住宅建築的投資
- 為了提高電動車的安全性並減輕重量,對汽車玻璃的需求不斷成長。
- 太陽能模組用玻璃產能快速擴張
- 節能建築標準推動了對低輻射(Low-E)玻璃和三層玻璃的需求增加。
- 抗菌玻璃在醫療和酒店業的廣泛應用。
- 市場限制因素
- 聚合物、丙烯酸酯和聚碳酸酯的替代品的可用性
- 堿灰和天然氣投入成本的波動
- 遵守歐盟碳邊境調節機制(CBAM)的成本
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 退火玻璃
- 透明玻璃
- 彩色玻璃
- 鍍膜玻璃
- 反射玻璃
- Low-E低輻射鍍膜玻璃
- 加工玻璃
- 夾層玻璃
- 強化玻璃
- 鏡面玻璃
- 花紋玻璃
- 退火玻璃
- 按最終用戶行業分類
- 建築/施工
- 車
- 太陽能玻璃
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 馬來西亞
- 泰國
- 印尼
- 越南
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 義大利
- 法國
- 西班牙
- 北歐國家
- 土耳其
- 俄羅斯
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 卡達
- 阿拉伯聯合大公國
- 奈及利亞
- 埃及
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Adamant Holding Company
- AGC Inc.
- Cardinal Glass Industries Inc.
- Central Glass Co., Ltd.
- China Glass Holdings Limited
- Euroglas
- Fuyao Group
- Guardian Industries
- Nippon Sheet Glass Co. Ltd
- Phoenicia
- Saint-Gobain
- SCHOTT
- Sisecam
- Taiwan Glass Industry Corporation
- Vitro
- Xinyi Glass Holdings Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the flat glass market size is expected to grow from 83.17 Million tons in 2025 to 86.48 Million tons in 2026 and is forecast to reach 105.14 Million tons by 2031 at 3.98% CAGR over 2026-2031.
This report is Segmented by Product Type (Annealed Glass, Coated Glass, Processed Glass, Mirror Glass, and Patterned Glass), End-User Industry (Building and Construction, Automotive, Solar Glass, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Flat Glass Market Trends and Insights
Growing Investments in Commercial and Residential Construction
Global construction outlays are forecast to climb, aided by lower borrowing costs and an uptick in developer sentiment. Multifamily starts accelerate in response to single-family affordability gaps, channeling sustained demand for curtain wall and window systems that integrate Low-E and triple-glazed units. Developers specify higher-performance glass to secure LEED credits, driving volume growth for sputter-coated and argon-filled insulating products. The flat glass market, therefore, benefits directly from code-driven window-to-wall ratios that favor advanced glazing solutions.
Rising Automotive Glazing Requirements for EV Safety and Lightweighting
Electric vehicle platforms intensify structural glazing needs while mandating lighter glass to offset battery mass. Fuyao committed CNY 9.1 billion (USD 1.26 billion) in 2024 for two new plants aimed at new-energy vehicle demand. Thin laminated windshields, panoramic roofs, and heads-up display-ready windscreens expand processed glass penetration. Embedded sensor packages elevate value per car, creating a lucrative growth pocket inside the broader flat glass market. Aerodynamic gains from slimmer profiles further align with range optimization, cementing glass as a critical lightweight substrate over the forecast horizon.
Availability of Polymer, Acrylic and Polycarbonate Substitutes
Automakers trial polycarbonate side windows and panoramic roofs that weigh up to 50% less than comparable glass panels. Optical clarity and UV stability have improved, yet scratch resistance and thermal tolerance still lag glass. Stringent windshield regulations keep polycarbonate use niche, confining substitution risk mostly to non-load-bearing glazing. Glass recycling advantages and tighter end-of-life circularity goals further insulate flat glass market volumes.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Capacity Additions for Solar PV Module Glass
- Energy-Efficient Building Codes Boosting Low-E and Triple Glazing Demand
- Volatile Soda-Ash and Natural-Gas Input Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Processed glass generated the fastest 4.65% CAGR between 2026 and 2031, outpacing the broader flat glass market. Laminated and tempered variants supply automotive windscreens, curtain walls, and security facades where impact resistance is critical. Annealed output still dominated in 2025 with 79.62% of volume because it serves as the base substrate for downstream upgrades. The segment's cost edge keeps it central to commodity construction, yet its share is set to moderate as codes and safety norms elevate demand for value-added treatments.
Coated, reflective, and Low-E sheets advance in parallel due to mandatory thermal standards. AGC Glass Europe's 5.5 kg CO2 eq/m2 Low-Carbon Glass exemplifies product differentiation that commands premium bids. Tinted glass usage in EVs supports cabin cooling and battery efficiency. Mirror and patterned glass remain niche but attractive for interior and privacy applications. Altogether, specialization raises average selling prices, widening the processed share in the flat glass market size over the forecast horizon.
Complete Report Scope:
- By Product Type
- Annealed Glass
- Clear Glass
- Tinted Glass
- Coated Glass
- Reflective Glass
- Low-E Glass
- Processed Glass
- Laminated Glass
- Tempered Glass
- Mirror Glass
- Patterned Glass
- Annealed Glass
- By End-user Industry
- Building and Construction
- Automotive
- Solar Glass
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Nordic Countries
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Qatar
- United Arab Emirates
- Nigeria
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific region secured 63.88% of 2025 shipments and is expanding at a 4.63% CAGR, the highest among regions. India is scaling new float lines while testing green hydrogen furnaces under a 20-year offtake pact between Asahi India Glass and INOX Air Products.
Europe focuses on decarbonization leadership. Saint-Gobain and AGC started trials of a hybrid furnace that cuts CO2 by 75% through 50% electrification and oxy-fuel combustion, supported by the EU Innovation Fund. Carbon Border Adjustment Mechanism fees, effective 2026 incentivize local sourcing, potentially boosting intra-regional sales. North American producers, led by Vitro's USD 180 million modernization and O-I's UK investment, upgrade lines to withstand gas-price volatility and ESG scrutiny.
South America, the Middle East, and Africa post rising urbanization but face infrastructure deficits and competition from Asian imports. Green-field float projects remain selective, though regional builders prefer local panes to avoid freight surcharges, supporting gradual volume growth. Altogether, geographic shifts keep Asia unchallenged in volume share while other regions chase value-added specialties within the flat glass market.
- Adamant Holding Company
- AGC Inc.
- Cardinal Glass Industries Inc.
- Central Glass Co., Ltd.
- China Glass Holdings Limited
- Euroglas
- Fuyao Group
- Guardian Industries
- Nippon Sheet Glass Co. Ltd
- Phoenicia
- Saint-Gobain
- SCHOTT
- Sisecam
- Taiwan Glass Industry Corporation
- Vitro
- Xinyi Glass Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Investments in Commercial and Residential Construction
- 4.2.2 Rising Automotive Glazing Requirements for EV Safety and Lightweighting
- 4.2.3 Rapid Capacity Additions for Solar PV Module Glass
- 4.2.4 Energy-Efficient Building Codes Boosting Low-E And Triple Glazing Demand
- 4.2.5 Uptake Of Antimicrobial Glass in Healthcare and Hospitality
- 4.3 Market Restraints
- 4.3.1 Availability of Polymer, Acrylic and Polycarbonate Substitutes
- 4.3.2 Volatile Soda-Ash and Natural-Gas Input Costs
- 4.3.3 EU Carbon Border Adjustment Mechanism Compliance Costs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Annealed Glass
- 5.1.1.1 Clear Glass
- 5.1.1.2 Tinted Glass
- 5.1.2 Coated Glass
- 5.1.2.1 Reflective Glass
- 5.1.2.2 Low-E Glass
- 5.1.3 Processed Glass
- 5.1.3.1 Laminated Glass
- 5.1.3.2 Tempered Glass
- 5.1.4 Mirror Glass
- 5.1.5 Patterned Glass
- 5.1.1 Annealed Glass
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Automotive
- 5.2.3 Solar Glass
- 5.2.4 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Malaysia
- 5.3.1.6 Thailand
- 5.3.1.7 Indonesia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Spain
- 5.3.3.6 Nordic Countries
- 5.3.3.7 Turkey
- 5.3.3.8 Russia
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Qatar
- 5.3.5.3 United Arab Emirates
- 5.3.5.4 Nigeria
- 5.3.5.5 Egypt
- 5.3.5.6 South Africa
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Adamant Holding Company
- 6.4.2 AGC Inc.
- 6.4.3 Cardinal Glass Industries Inc.
- 6.4.4 Central Glass Co., Ltd.
- 6.4.5 China Glass Holdings Limited
- 6.4.6 Euroglas
- 6.4.7 Fuyao Group
- 6.4.8 Guardian Industries
- 6.4.9 Nippon Sheet Glass Co. Ltd
- 6.4.10 Phoenicia
- 6.4.11 Saint-Gobain
- 6.4.12 SCHOTT
- 6.4.13 Sisecam
- 6.4.14 Taiwan Glass Industry Corporation
- 6.4.15 Vitro
- 6.4.16 Xinyi Glass Holdings Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 印度平板玻璃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)中東和非洲平板玻璃市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 平板玻璃市場:2026-2032年全球市場預測(依產品類型、鍍膜類型、應用、最終用途及通路分類)
 平板玻璃加工機械市場 - 全球產業規模、佔有率、趨勢、機會、預測:機器類型、終端用戶產業、玻璃類型、自動化程度、地區及競爭格局,2021-2031年
 平板玻璃市場規模、佔有率和趨勢分析報告:按產品、應用、地區和細分市場預測(2026-2033 年)南美洲平板玻璃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)平板玻璃市場-全球產業規模、佔有率、趨勢、機會和預測:按產品類型、技術、終端用戶產業、地區和競爭格局分類,2021-2031年
 平板玻璃市場:按產品、應用和地區分類
 2026年全球平板玻璃市場報告美國平板玻璃:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)