


 |
市場調查報告書
商品編碼
2121701
歐洲熱可塑性橡膠:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Europe Thermoplastic Elastomers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,2025 年歐洲熱可塑性橡膠市值為 61.9 億美元,2026 年成長至 64.1 億美元,到 2031 年達到 75.9 億美元。
預測期(2026-2031 年)的複合年成長率預計為 3.44%。
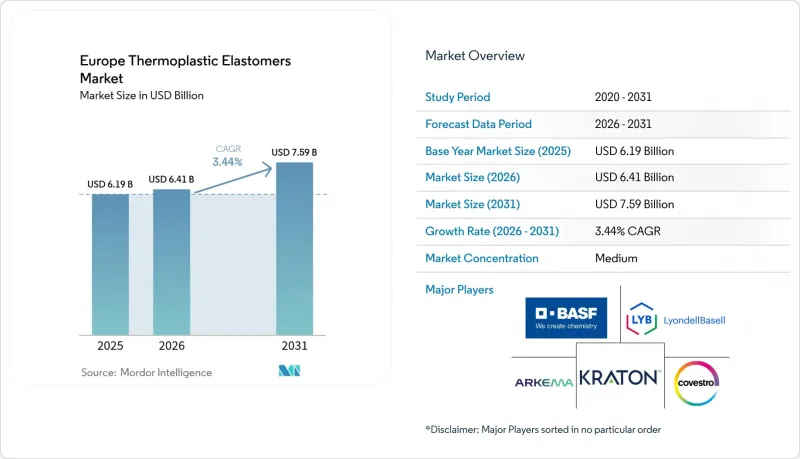
本報告按產品類型(苯乙烯嵌段共聚物、熱塑性烯烴、熱塑性聚氨酯等)、應用領域(汽車和交通運輸、建築和施工、鞋類和體育用品、電氣和電子、醫療等)以及地區(德國、英國、法國等)進行細分。市場預測以美元計價。
歐洲熱可塑性橡膠市場趨勢與洞察
受電動車的推動,歐洲汽車零件產業正在經歷一場輕量化熱潮。
在電動車架構中,為了抵銷電池的重量,需要將整車重量減輕15%至20%。因此,汽車製造商正在重新審視其材料清單,並優先選擇可回收的熱可塑性橡膠,而不是壓鑄金屬和硫化橡膠。大眾汽車指定使用山都平TPV(Santoprene TPV)製造引擎罩,這種材料比EPDM(三元乙丙橡膠)輕30%,並且能夠承受120 度C的油污環境。大陸集團與合作夥伴共同開發了發泡射出成型的TPE(熱塑性彈性體)車門密封條,每輛車可減重200克。雖然這看起來似乎微不足道,但考慮到沃爾夫斯堡的生產規模,每年可減重高達400噸。在法國和西班牙,Stellantis 和雷諾正在使用在地採購的TPE 墊片,以達到歐盟電池法規規定的碳足跡閾值,即到 2027 年「低於 50 kg CO2e/kWh」。隨著基於 ISO 14040 的生命週期審核開始影響採購決策,中小型複合材料生產商現在正在考慮合併,以確保獲得實施可追溯性系統的資金。
建築密封膠中PVC和EPDM的快速替代
德國和北歐國家的門窗製造商正逐步轉向使用TPE型材,以滿足「DGNB Gold」和「BREEAM Excellent」認證的要求。這些認證認為使用鹵化聚合物有劣勢。 TPE-S和TPE-V型材即使在經過基於ISO 4892-2標準的5000小時氙弧燈測試後,仍能維持200%以上的延伸率,其耐候性與PVC相當,且不會發生塑化劑滲出。英國將於2025年開始實施的「未來住宅標準」要求在50帕壓力下,氣密性低於5立方公尺/小時/平方公尺。共擠TPE角鍵在符合此要求的同時,也能將每組門窗的安裝時間縮短15分鐘。 Rehau和Deceuninck公司在產品中加入了40-50%的工業廢棄物回收材料,從而促進了循環經濟的發展,並緩解了EPDM價格的波動。即將生效的歐盟建築產品法規附件 ZA 將強制要求提交環境產品聲明 (EPD),這將加速法蘭克福和阿姆斯特丹的幕牆建造商採用 TPE。
苯乙烯和異氰酸酯的價格波動與原油價格相關
當布蘭特原油價格在一個季度內波動超過20美元/桶時,苯乙烯和丁二烯的價格幾乎與石腦油價差同步波動,推高了原料成本,而原料成本佔TPE-S生產成本的60%之多。西北歐苯乙烯現貨價格從2024年1月的1400美元/噸下跌21%至10月的1100美元/噸,擠壓了英力士苯領等一體化生產商的利潤空間,該公司甚至關閉了其位於安特衛普的生產線進行夏季維護。 2024年第二季度,BASF的MDI不可抗力事件導致異氰酸酯價格上漲18%,使得TPU擠出機的前置作業時間了六週。缺乏避險工具或自有原料來源的中小型混煉企業被迫犧牲200-300個基點的利潤率,導致更多家族企業成為私募股權收購和合併的目標。
細分市場分析
2025年,苯乙烯基嵌段共聚物佔據了歐洲熱可塑性橡膠市場38.92%的佔有率,主要用於黏合劑、鞋類和家用電器軟觸感部件的配方。預計到2031年,熱塑性聚氨酯的複合年成長率將達到3.56%,隨著醫療和豪華汽車行業的客戶對耐磨性和耐油性(邵氏A硬度80以上)的需求日益成長,熱塑性聚氨酯有望進一步擴大其在歐洲熱可塑性橡膠市場的佔有率。熱塑性烯烴(TPO)由於無需底漆即可塗漆,仍然是外牆板的主要材料。然而,亞洲進口產品的價格比歐洲進口產品便宜10-15%,這給本地製造商的利潤率帶來了壓力。
根據ASTM D471標準,熱塑性彈性體(TPV)合金在引擎蓋密封件市場佔據主導地位,其油溶脹率必須低於15%。然而,在電動動力傳動系統墊片市場,由於需要連續使用在150 度C以上的高溫下,矽基彈性體合金的市場佔有率正在被蠶食。共聚酯和聚醯胺彈性體滿足了高溫管材這一細分市場的需求,但它們面臨著濕度敏感性和加工成本的挑戰。 ISO 1629標籤系統取消了商標限制,使採購團隊能夠快速更換供應商,這加劇了歐洲熱可塑性橡膠市場的價格壓力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電動車主導歐洲汽車零件產業輕量化熱潮。
- 建築密封劑中聚氯乙烯(PVC) 和三元乙丙橡膠 (EPDM) 的快速替代
- 導管擠出製造商對醫用熱塑性胺甲酸乙酯的需求
- 用於低密度內裝的發泡注塑TPE
- OEM召回義務推動了PCR混合TPE的使用。
- 市場限制因素
- 與原油價格掛鉤的苯乙烯和異氰酸酯的價格波動劇烈。
- 歐盟 REACH 法規對鄰苯二甲酸酯和苯乙烯單體有嚴格的限制。
- 在電動車領域與耐熱矽膠的競爭
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 苯乙烯基嵌段共聚物(TPE-S)
- 熱塑性烯烴(TPE-O)
- 彈性體合金(TPE-V/TPV)
- 熱塑性聚氨酯(TPU)
- 熱塑性共聚酯
- 熱塑性聚醯胺
- 透過使用
- 汽車和運輸業
- 建築/施工
- 鞋類和運動器材
- 電氣和電子設備
- 醫學領域
- 電器產品
- HVAC
- 黏合劑、密封劑和塗料
- 其他
- 按地區
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率(%)/排名分析
- 公司簡介
- Apar Industries Ltd.
- Arkema
- Avient Corporation
- BASF
- Celanese Corporation
- Covestro AG
- Covestro AG
- DSM
- DuPont
- Evonik Industries AG
- Exxon Mobil Corporation
- Grupo Dynasol
- Huntsman International LLC
- KRATON CORPORATION
- KURARAY CO. LTD.
- LANXESS
- LG Chem
- LyondellBasell Industries Holdings BV
- Mitsubishi Chemical Corporation
- Mitsui Chemicals Inc.
- SABIC
- Sirmax SpA
- Sumitomo Chemical Co. Ltd.
- The Lubrizol Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe thermoplastic elastomers market size was valued at USD 6.19 billion in 2025 and estimated to grow from USD 6.41 billion in 2026 to reach USD 7.59 billion by 2031, at a CAGR of 3.44% during the forecast period (2026-2031).
This report is Segmented by Product Type (Styrenic Block Copolymer, Thermoplastic Olefin, Thermoplastic Polyurethane, and More), Application (Automotive and Transportation, Building and Construction, Footwear and Sporting Goods, Electrical and Electronics, Medical, and More), and Geography (Germany, United Kingdom, France, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Thermoplastic Elastomers Market Trends and Insights
EV-Driven Lightweighting Boom in European Auto Parts
Electric-vehicle architectures must shed 15-20% of their mass to counterbalance the weight of the battery, so OEMs are revising their material lists to favor recyclable thermoplastic elastomers over die-cast metal and vulcanized rubber. Volkswagen specifies Santoprene TPV engine covers that save 30% versus EPDM while handling 120°C oil exposure. Continental AG co-developed foam-injection TPE door seals, weighing 200 g less per vehicle. This seemingly small figure translates to 400 t of annual weight reduction at Wolfsburg volumes. In France and Spain, Stellantis and Renault source localized TPE gaskets to meet EU Battery Regulation carbon footprint thresholds of below 50 kg CO2e/kWh by 2027. ISO 14040 life-cycle audits now influence sourcing decisions, prompting smaller compounders to consider mergers that can finance traceability systems.
Rapid Substitution of PVC and EPDM in Building Seals
Window and door makers across Germany and the Nordics are transitioning to TPE profiles to meet the requirements of DGNB Gold and BREEAM Excellent labels, which penalize the use of halogenated polymers. TPE-S and TPE-V retain elongation above 200% after 5,000 hours of xenon-arc testing per ISO 4892-2, matching the weatherability of PVC without plasticizer bleed. The UK Future Homes Standard, effective from 2025, requires airtightness of below 5 m3/h/m2 at 50 Pa; co-extruded TPE corner keys meet this target while reducing installation time by 15 minutes per unit. Rehau and Deceuninck incorporate 40-50% post-industrial regrind, adding circularity that cushions EPDM price swings. The forthcoming EU Construction Products Regulation Annex ZA will require Environmental Product Declarations, thereby accelerating the uptake of TPE among facade contractors in Frankfurt and Amsterdam.
Volatile Crude-Linked Styrene and Isocyanate Prices
When Brent shifts more than USD 20/bbl inside a quarter, styrene and butadiene follow naphtha spreads almost in lockstep, driving feedstock costs that represent up to 60% of TPE-S production. Spot styrene in Northwest Europe slid 21% from USD 1,400/t in January 2024 to USD 1,100/t by October, pinching margins for integrated players such as INEOS Styrolution, which idled lines at Antwerp during summer maintenance. A BASF force-majeure event on MDI in Q2 2024 inflated isocyanate prices by 18% and left TPU extruders with six-week lead times. Smaller compounders that lack hedge tools or captive feedstocks surrendered 200-300 bps margin, pushing more family-owned plants into private-equity roll-ups.
Other drivers and restraints analyzed in the detailed report include:
- Medical-Grade TPU Demand from Catheter Extruders
- Foam-Injection TPE for Low-Density Interior Trims
- Tight EU REACH Limits on Phthalates and Styrene Monomer
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Styrenic block copolymers held 38.92% of the Europe thermoplastic elastomers market in 2025, underpinning formulations for adhesives, footwear, and soft-touch appliance parts. Thermoplastic polyurethanes are projected to post a 3.56% CAGR to 2031, increasing their share of the European thermoplastic elastomers market size as medical and premium automotive customers value abrasion and oil resistance at 80+ Shore A hardness levels. Thermoplastic olefins remain staples for exterior fascias due to their paintability without primers; however, Asian imports price them 10-15% below European output, thereby trimming margins for local producers.
Elastomeric alloys, positioned as TPVs, dominate under-hood seals that must limit oil swell to 15% per ASTM D471; however, silicone rivals are eroding their share in e-powertrain gaskets that require continuous use above 150 °C. Copolyesters and polyamide elastomers address high-temperature tubing niches, but they face hurdles related to moisture sensitivity and processing costs. ISO 1629 labeling has stripped away trade-name lock-in, letting procurement teams switch suppliers rapidly and sparking price pressure across the Europe thermoplastic elastomers market.
Complete Report Scope:
- By Product Type
- Styrenic Block Copolymer (TPE-S)
- Thermoplastic Olefin (TPE-O)
- Elastomeric Alloy (TPE-V / TPV)
- Thermoplastic Polyurethane (TPU)
- Thermoplastic Copolyester
- Thermoplastic Polyamide
- By Application
- Automotive and Transportation
- Building and Construction
- Footwear and Sporting Goods
- Electrical and Electronics
- Medical
- Household Appliances
- HVAC
- Adhesives, Sealants and Coatings
- Others
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Apar Industries Ltd.
- Arkema
- Avient Corporation
- BASF
- Celanese Corporation
- Covestro AG
- Covestro AG
- DSM
- DuPont
- Evonik Industries AG
- Exxon Mobil Corporation
- Grupo Dynasol
- Huntsman International LLC
- KRATON CORPORATION
- KURARAY CO. LTD.
- LANXESS
- LG Chem
- LyondellBasell Industries Holdings BV
- Mitsubishi Chemical Corporation
- Mitsui Chemicals Inc.
- SABIC
- Sirmax SpA
- Sumitomo Chemical Co. Ltd.
- The Lubrizol Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV-driven lightweighting boom in European auto parts
- 4.2.2 Rapid substitution of Polyvinyl Chloride and EPDM in building seals
- 4.2.3 Medical-grade Thermoplastic-Urethane demand from catheter extruders
- 4.2.4 Foam-injection TPE for low-density interior trims
- 4.2.5 OEM take-back mandates fueling PCR-blend TPE usage
- 4.3 Market Restraints
- 4.3.1 Volatile crude-linked styrene and isocyanate prices
- 4.3.2 Tight EU REACH limits on phthalates and styrene monomer
- 4.3.3 Competition from high-temp silicones in e-mobility
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Styrenic Block Copolymer (TPE-S)
- 5.1.2 Thermoplastic Olefin (TPE-O)
- 5.1.3 Elastomeric Alloy (TPE-V / TPV)
- 5.1.4 Thermoplastic Polyurethane (TPU)
- 5.1.5 Thermoplastic Copolyester
- 5.1.6 Thermoplastic Polyamide
- 5.2 By Application
- 5.2.1 Automotive and Transportation
- 5.2.2 Building and Construction
- 5.2.3 Footwear and Sporting Goods
- 5.2.4 Electrical and Electronics
- 5.2.5 Medical
- 5.2.6 Household Appliances
- 5.2.7 HVAC
- 5.2.8 Adhesives, Sealants and Coatings
- 5.2.9 Others
- 5.3 By Geography
- 5.3.1 Germany
- 5.3.2 United Kingdom
- 5.3.3 France
- 5.3.4 Italy
- 5.3.5 Spain
- 5.3.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Apar Industries Ltd.
- 6.4.2 Arkema
- 6.4.3 Avient Corporation
- 6.4.4 BASF
- 6.4.5 Celanese Corporation
- 6.4.6 Covestro AG
- 6.4.7 Covestro AG
- 6.4.8 DSM
- 6.4.9 DuPont
- 6.4.10 Evonik Industries AG
- 6.4.11 Exxon Mobil Corporation
- 6.4.12 Grupo Dynasol
- 6.4.13 Huntsman International LLC
- 6.4.14 KRATON CORPORATION
- 6.4.15 KURARAY CO. LTD.
- 6.4.16 LANXESS
- 6.4.17 LG Chem
- 6.4.18 LyondellBasell Industries Holdings BV
- 6.4.19 Mitsubishi Chemical Corporation
- 6.4.20 Mitsui Chemicals Inc.
- 6.4.21 SABIC
- 6.4.22 Sirmax SpA
- 6.4.23 Sumitomo Chemical Co. Ltd.
- 6.4.24 The Lubrizol Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 熱可塑性橡膠市場預測至2034年-按產品類型、加工方法、應用和地區分類的全球分析
 南美洲熱可塑性橡膠(TPE)市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 熱可塑性橡膠市場-2026-2032年全球市場預測
 2026年全球醫療設備熱可塑性橡膠市場報告熱可塑性橡膠(TPE):市場佔有率分析、產業趨勢與統計數據、成長預測(2026-2031)中東和非洲熱可塑性橡膠(TPE)市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)醫療設備用熱可塑性橡膠:市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)
 熱可塑性橡膠市場:依類型、應用、終端用戶產業及地區分類
 全球熱可塑性橡膠市場規模、佔有率、趨勢和成長分析報告(2026-2034年)全球熱塑性聚醯胺彈性體市場規模、佔有率、趨勢和成長分析報告(2026-2034年)