


 |
市場調查報告書
商品編碼
2120483
北美地區市場分析:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)North America Location Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
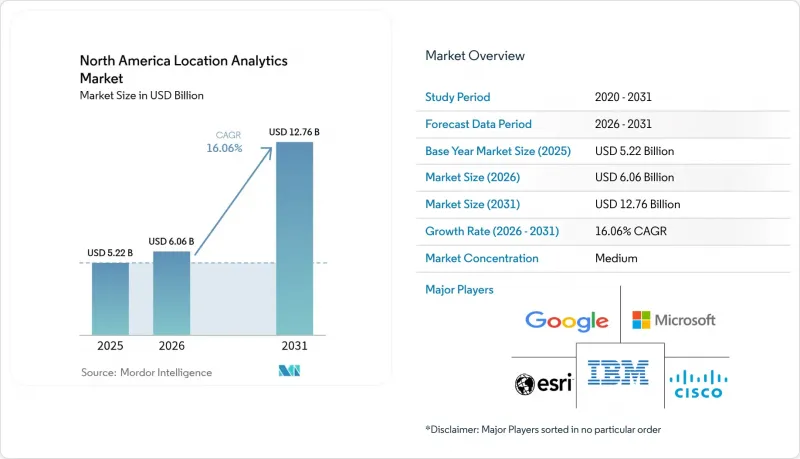
據 Mordor Intelligence 稱,2025 年北美位置分析市值為 52.2 億美元,預計到 2031 年將達到 127.6 億美元,而 2026 年為 60.6 億美元,預測期(2026-2031 年)的複合年成長率為 16.06%。
本報告按位置類型(室內、室外)、部署模式(本地部署、雲端部署、其他)、組件(解決方案、其他)、技術(GPS/GNSS、Wi-Fi、其他)、最終用戶行業(零售/電子商務、銀行/金融服務/保險 (BFSI)、製造業、政府/國防、其他)、應用(風險管理、其他)和國家/地區進行細分。市場預測以美元 (USD) 計價。
北美位置分析市場趨勢與洞察
全通路零售中地理行銷宣傳活動的激增。
零售商正將地理圍欄工具與客戶關係管理 (CRM) 系統結合,以部署即時促銷活動並提高門市層面的轉換率。展示室最佳化研究表明,店內策略性的產品陳列和擴大地理覆蓋範圍能夠提升銷售額和消費者信心。隨著實體店和線上體驗的整合不斷加深,差異化的基於位置的內容正成為建立客戶忠誠度的一種有效手段,而這是純粹的電子商務企業無法複製的。
加強有關隱私和消費者選擇退出機制的監管
加州《加州消費者隱私法案》(CCPA) 的嚴厲打擊主要集中在位置資料的個人性質上,強制要求企業明確選擇退出,並採用更嚴格的同意流程。企業現在需要將隱私工程融入所有分析技術堆疊中,並且可能需要調整資料粒度以確保合規。
細分市場分析
隨著GPS和GNSS成為交通運輸和物流的基礎,戶外定位服務在2025年仍將佔據北美位置分析市場54.35%的佔有率。同時,室內定位正以17.85%的複合年成長率成長,這得歸功於CBRS專用5G和超寬頻(UWB)部署所帶來的亞米級定位精度。製造商正在將這項技術應用於資產級可視性,醫院也正在利用它來追蹤昂貴的設備。
對混合解決方案日益成長的需求要求供應商整合室內和室外資料層,以建立單一資料來源儀表板。工業4.0藍圖要求採用地理區域分類來保障工人安全,並滿足需要連續座標流的自動導引運輸車(AGV)的需求。因此,北美位置分析市場正轉向多模態引擎,以補償室外GPS漂移和室內多路徑校正。
即使到了2025年,本地部署系統仍將佔據北美位置分析市場59.20%的佔有率,這反映出在高度監管的行業中,數據主權的重要性日益凸顯。雲端解決方案正以19.6%的複合年成長率快速成長,計量收費,結合邊緣推理和雲端建模的混合架構,尤其適用於低延遲應用場景,也不斷出現。
私有 CBRS 網路提供了一個本地部署方案,兼顧了雲端協作和資料主權,使工廠能夠避免被公共雲端廠商鎖定。 GeoParquet 等創新技術最大限度地減少了 ETL 開銷,使以往需要專門 GIS 腳本的工作流程能夠實現敏捷操作。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 全通路零售中地理行銷宣傳活動的激增。
- 物聯網感測器和連網型設備的普及
- 加速採用雲端原生地理空間分析平台。
- 企業對混合辦公場所使用分析的需求。
- 透過 CBRS 專用 5G 的可用性,提高了室內定位精度。
- 市場限制因素
- 加強有關隱私和消費者選擇退出機制的監管
- 即時室內定位系統整體擁有成本高
- 地理空間資料科學領域人才短缺
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按位置類型
- 室內的
- 戶外的
- 按部署模式
- 現場
- 雲
- 混合
- 邊緣(設備內部)
- 按組件
- 解決方案
- 服務
- 透過技術
- GPS/GNSS
- Wi-Fi
- Bluetooth Low-Energy(BLE)
- 超寬頻(UWB)
- 蜂窩網路(包括 4G、5G 和 CBRS)
- RFID/NFC
- 磁性及其他
- 按最終用戶行業分類
- 零售與電子商務
- 銀行、金融服務和保險(BFSI)
- 製造業
- 醫療保健和生命科學
- 政府/國防
- 能源與公共產業
- 運輸/物流
- 通訊/IT
- 房地產和智慧建築
- 其他
- 透過使用
- 風險管理
- 供應鍊和庫存最佳化
- 最佳化銷售和行銷
- 設施和資產管理
- 員工和現場人員管理
- 遠端監控和預測性維護
- 緊急和災害應變管理
- 客戶經驗互動
- 詐欺與合規分析
- 其他
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cisco Systems Inc.
- SAP SE
- Esri Inc.
- Aruba Networks(HPE Development LP)
- IBM Corporation
- SAS Institute Inc.
- Pitney Bowes Inc.
- HERE Global BV
- TIBCO Software Inc.
- Ericsson Inc.
- Microsoft Corporation
- Google LLC
- Oracle Corporation
- Alteryx Inc.
- Mapbox Inc.
- CARTO
- Trimble Inc.
- Zebra Technologies Corp.
- Inpixon
- Foursquare Labs Inc.
- Precisely
- TomTom NV
- Mapsted Corp.
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America location analytics market size was valued at USD 5.22 billion in 2025 and estimated to grow from USD 6.06 billion in 2026 to reach USD 12.76 billion by 2031, at a CAGR of 16.06% during the forecast period (2026-2031).
This report is Segmented by Location (Indoor, Outdoor), Deployment Model (On-Premises, Cloud and More), Component (Solutions and More), Technology (GPS / GNSS, Wi-Fi and More), End-User Vertical (Retail, Banking, Manufacturing, Government, and More), Application (Risk Management and More), and by Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Location Analytics Market Trends and Insights
Surge in Omni-Channel Retail Geo-Marketing Campaigns
Retailers pair geofencing tools with CRM suites to trigger real-time promotions, driving higher conversion at store level. Showroom optimization research indicates that strategic in-store product placement and geographic reach expansion lift sales and consumer confidence. As brick-and-click convergence deepens, differentiated location content becomes a loyalty lever that pure-play e-commerce cannot replicate.
Heightened Privacy and Consumer Opt-Out Regulations
California's CCPA enforcement sweep spotlights the personal nature of geolocation data, requiring explicit opt-outs and stronger consent flows. Enterprises must now embed privacy engineering into every analytics stack, sometimes trimming data granularity to stay compliant.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of IoT Sensors & Connected Devices
- Accelerated Adoption of Cloud-Native Geospatial Analytics Platforms
- Corporate Demand for Hybrid Workplace Occupancy Intelligence
- High Total Cost of Ownership for Real-Time Indoor Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Outdoor services retained 54.35% North America location analytics market share in 2025 as GPS/GNSS underpins transportation and logistics. Indoor positioning, however, compounds at 17.85% CAGR, powered by sub-meter accuracy from CBRS-enabled private 5G and ultra-wideband deployments. Manufacturers embed the technology for asset-level visibility, while hospitals apply it to track high-value equipment.
Growing hybrid demand obliges vendors to fuse indoor and outdoor layers into single source-of-truth dashboards. Industry 4.0 blueprints call for worker safety geozones and automated guided vehicles requiring continuous coordinate streams. The North America location analytics market therefore pivots to multi-modal engines that reconcile GPS drift outdoors with multipath corrections indoors.
On-premise systems still accounted for 59.20% of the North America location analytics market size in 2025, reflecting data-sovereignty priorities among heavily regulated sectors. Cloud options are scaling at a 19.6% CAGR as pay-as-you-go processing and native collaboration entice enterprises with limited capex. Hybrid architectures are also rising, combining edge inference with cloud modeling for low-latency use cases.
Private CBRS networks offer an on-site alternative that marries cloud orchestration with sovereign data paths, giving factories a route around public-cloud lock-in. Format innovations such as GeoParquet minimize ETL overhead, unlocking agile workflows that previously demanded specialist GIS scripting.
Complete Report Scope:
- By Location Type
- Indoor
- Outdoor
- By Deployment Model
- On-premise
- Cloud
- Hybrid
- Edge (on-device)
- By Component
- Solutions
- Services
- By Technology
- GPS / GNSS
- Wi-Fi
- Bluetooth Low-Energy (BLE)
- Ultra-Wideband (UWB)
- Cellular (4G/5G incl. CBRS)
- RFID & NFC
- Magnetic & Other
- By End-User Vertical
- Retail & E-Commerce
- Banking, Financial Services & Insurance (BFSI)
- Manufacturing
- Healthcare & Life Sciences
- Government & Defense
- Energy & Utilities
- Transportation & Logistics
- Telecom & IT
- Real Estate & Smart Buildings
- Other Verticals
- By Application
- Risk Management
- Supply Chain & Inventory Optimization
- Sales & Marketing Optimization
- Facility & Asset Management
- Workforce & Field-Force Management
- Remote Monitoring & Predictive Maintenance
- Emergency & Disaster Response Management
- Customer Experience & Engagement
- Fraud & Compliance Analytics
- Others
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Cisco Systems Inc.
- SAP SE
- Esri Inc.
- Aruba Networks (HPE Development LP)
- IBM Corporation
- SAS Institute Inc.
- Pitney Bowes Inc.
- HERE Global BV
- TIBCO Software Inc.
- Ericsson Inc.
- Microsoft Corporation
- Google LLC
- Oracle Corporation
- Alteryx Inc.
- Mapbox Inc.
- CARTO
- Trimble Inc.
- Zebra Technologies Corp.
- Inpixon
- Foursquare Labs Inc.
- Precisely
- TomTom N.V.
- Mapsted Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in omni-channel retail geo-marketing campaigns
- 4.2.2 Proliferation of IoT sensors & connected devices
- 4.2.3 Accelerated adoption of cloud-native geospatial analytics platforms
- 4.2.4 Corporate demand for hybrid workplace occupancy intelligence
- 4.2.5 Availability of CBRS private-5G improving indoor location accuracy
- 4.3 Market Restraints
- 4.3.1 Heightened privacy and consumer opt-out regulations
- 4.3.2 High total cost of ownership for real-time indoor location systems
- 4.3.3 Shortage of geospatial data-science talent
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE & GROWTH FORECASTS (VALUE)
- 5.1 By Location Type
- 5.1.1 Indoor
- 5.1.2 Outdoor
- 5.2 By Deployment Model
- 5.2.1 On-premise
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.2.4 Edge (on-device)
- 5.3 By Component
- 5.3.1 Solutions
- 5.3.2 Services
- 5.4 By Technology
- 5.4.1 GPS / GNSS
- 5.4.2 Wi-Fi
- 5.4.3 Bluetooth Low-Energy (BLE)
- 5.4.4 Ultra-Wideband (UWB)
- 5.4.5 Cellular (4G/5G incl. CBRS)
- 5.4.6 RFID & NFC
- 5.4.7 Magnetic & Other
- 5.5 By End-User Vertical
- 5.5.1 Retail & E-Commerce
- 5.5.2 Banking, Financial Services & Insurance (BFSI)
- 5.5.3 Manufacturing
- 5.5.4 Healthcare & Life Sciences
- 5.5.5 Government & Defense
- 5.5.6 Energy & Utilities
- 5.5.7 Transportation & Logistics
- 5.5.8 Telecom & IT
- 5.5.9 Real Estate & Smart Buildings
- 5.5.10 Other Verticals
- 5.6 By Application
- 5.6.1 Risk Management
- 5.6.2 Supply Chain & Inventory Optimization
- 5.6.3 Sales & Marketing Optimization
- 5.6.4 Facility & Asset Management
- 5.6.5 Workforce & Field-Force Management
- 5.6.6 Remote Monitoring & Predictive Maintenance
- 5.6.7 Emergency & Disaster Response Management
- 5.6.8 Customer Experience & Engagement
- 5.6.9 Fraud & Compliance Analytics
- 5.6.10 Others
- 5.7 By Country
- 5.7.1 United States
- 5.7.2 Canada
- 5.7.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Cisco Systems Inc.
- 6.4.2 SAP SE
- 6.4.3 Esri Inc.
- 6.4.4 Aruba Networks (HPE Development LP)
- 6.4.5 IBM Corporation
- 6.4.6 SAS Institute Inc.
- 6.4.7 Pitney Bowes Inc.
- 6.4.8 HERE Global BV
- 6.4.9 TIBCO Software Inc.
- 6.4.10 Ericsson Inc.
- 6.4.11 Microsoft Corporation
- 6.4.12 Google LLC
- 6.4.13 Oracle Corporation
- 6.4.14 Alteryx Inc.
- 6.4.15 Mapbox Inc.
- 6.4.16 CARTO
- 6.4.17 Trimble Inc.
- 6.4.18 Zebra Technologies Corp.
- 6.4.19 Inpixon
- 6.4.20 Foursquare Labs Inc.
- 6.4.21 Precisely
- 6.4.22 TomTom N.V.
- 6.4.23 Mapsted Corp.
7 MARKET OPPORTUNITIES & FUTURE OUTLOOK
- 7.1 White-space & Unmet-need Assessment

 位置分析市場規模、佔有率和趨勢分析報告:按組件、分析類型、技術、位置類型、部署方式、企業規模、最終用途和細分市場預測(2026-2033 年)
 中東和非洲地區市場分析:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031年)歐洲位置分析:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 位置分析市場:按組件、部署模式、分析類型和應用分類-2026-2032年全球市場預測
 位置分析市場:按元件、位置類型、部署方式、產業和地區分類
 2026年全球位置分析市場報告
 位置分析市場規模、佔有率、趨勢和預測:按組件、部署類型、位置類型、應用、最終用戶行業和地區分類,2026-2034 年
 位置分析市場分析及預測(至 2035 年):按類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶和解決方案分類
 位置分析市場規模、佔有率、成長率和全球產業分析:按類型、應用和地區分類的洞察,2026-2034 年預測
 全球位置分析市場(至 2035 年):按組件類型、位置類型、部署類型、應用類型、行業類型、地區、行業趨勢和預測