


 |
市場調查報告書
商品編碼
2120415
生物來源肥料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Biological Organic Fertilizer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
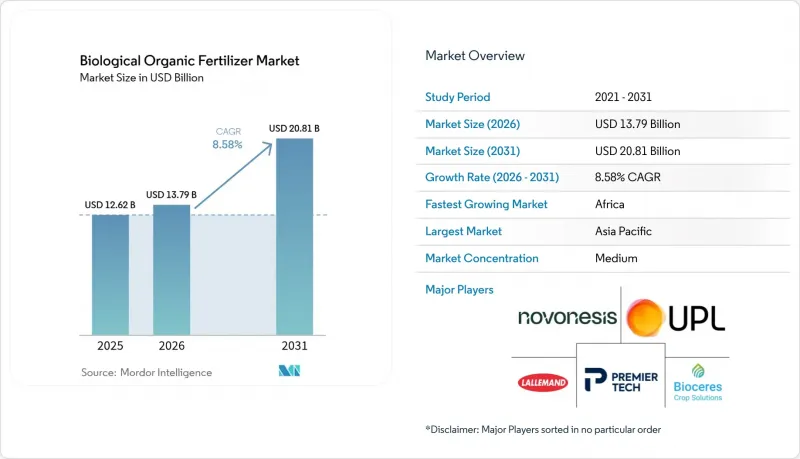
根據 Mordor Intelligence 預測,生物來源有機肥料的市場規模預計將從 2025 年的 126.2 億美元成長到 2026 年的 137.9 億美元,然後在 2031 年達到 208.1 億美元,2026 年至 2031 年的複合年成長率為 8.58%。
本報告按類型(微生物和有機殘留物)、應用(穀物、豆類和油籽、水果和蔬菜、經濟作物、草坪和觀賞植物)以及地區(北美、歐洲、亞太、南美以及中東和非洲)進行細分。市場預測以美元計價。
全球生物來源有機肥料市場趨勢及洞察
聯邦政府對再生農業的獎勵措施
在主要農業區,政府計畫會報銷生物來源材料的大部分成本,為微生物產品帶來良好的經濟前景。 2025年12月,美國農業部(USDA)啟動了7億美元的再生農業試驗計畫,旨在推廣改善土壤健康、水質和生物多樣性的實踐。這筆資金將透過自然資源保護部(NRCS)分配,其中4億美元來自環境品質激勵計畫(EQIP),3億美元來自保育管理計畫(CSP)。在印度,政府透過資本投資補貼計畫(CISS)等計畫鼓勵使用生物肥料,該計畫為政府機構提供高達100%的補貼,為私營企業提供25%的生產成本補貼。農民還可以從潘帕拉加特農業發展計畫(PKVY)獲得財政支持,並透過總理農業舉措(PM-PRANAM)獲得減少化肥使用的獎勵。根據2023年至2027年的通用農業政策(CAP),歐盟規定至少25%的直接支付預算必須分配給支持氣候和環境永續實踐的自願性生態計畫。這些獎勵結合起來,縮短了投資回收期,使生物來源產品在經濟上更具吸引力,即使在大田種植系統中也是如此。
加強對合成肥料的監管
全球監管機構正在對氮磷負荷設定限制,從而持續推動對生物來源有機肥料的需求。歐盟作為其「從農場到餐桌」策略的一部分,正在實施合成肥料相關法規,目標是到2030年將養分流失至少減少50%。該舉措還旨在將肥料總用量減少20%。新的法規(歐盟2019/1009)旨在加強環境標準,推廣有機替代品的使用,並從2026年起限制微塑膠的使用,包括肥料上的聚合物包衣。在中國,為了解決環境問題,正在透過嚴格的註冊要求、禁止使用劇毒產品以及旨在實現化肥使用量零成長的國家指令來限制化肥的使用。甚至大型化肥生產商也在重新審視其商業策略。雅苒國際公司(Yara International ASA)已提高了其微生物研究預算的比例。雖然不同地區的監管嚴格程度有所不同,但已開發市場和新興市場都出現了分階段監管的趨勢,向生物來源材料的結構性轉變正在形成。
高溫氣候下保存期限短
微生物在30 度C以上的溫度下會損失大量生命力,這限制了它們在熱帶地區的應用。缺乏完善的冷鏈基礎設施加劇了這個問題,因為非洲只有極少數農村配送中心配備了冷藏設施。這種限制導致奈及利亞和肯亞等氣候溫暖地區在一年中最熱的月份產品退貨率顯著升高。雖然包埋可以提供一定的保護,但它會大幅增加成本,給小規模農戶帶來經濟挑戰。解決這項問題的努力,例如在印度引入太陽能村莊冷藏系統,仍處於起步階段,目前只有少數設施運作中,尚未有效降低這些地區溫度敏感性的風險。
細分市場分析
微生物肥料是最大的類別,預計到2025年將佔生物來源有機肥料市場佔有率的57.3%,並在2031年之前以10.5%的複合年成長率成長,是所有類別中成長最快的。根瘤菌預計將在生物基有機肥料市場佔據重要佔有率,因為北美和亞洲等地區的豆科作物種植者正在擴大接種劑的使用,以減少對合成氮肥的依賴,同時保持生物來源產量。固氮螺菌也正在快速成長,這主要得益於大規模玉米種植者為減少氮肥用量所採取的措施。磷酸鹽釋放細菌和菌根真菌的使用也在穩步成長,尤其是在磷缺乏普遍存在且由於多年生作物的經濟效益,價格較高的解決方案在經濟上可行的地區。這種趨勢在咖啡、杏仁和酪梨等作物中尤其明顯。
到2025年,有機殘渣將佔據剩餘佔有率。綠肥在這一細分市場中主導,但其勞動密集的特徵給機械化糧食生產地區帶來了挑戰。魚粉和骨粉在高價值蔬菜種植系統中表現良好,其緩釋磷的特性能滿足高強度灌溉的需求。楝樹和蓖麻油餅獲得了區域補貼,但人們對重金屬殘留和營養成分分析結果的不穩定性擔憂,阻礙了其在出口導向市場的擴張。有機殘渣的採用取決於當地的農業實踐、原料供應情況以及這些投入品與合成替代品相比的成本效益。提高營養穩定性並解決污染問題對於促進其在全球市場的推廣至關重要。
區域分析
亞太地區是最大的市場,預計到2025年將佔生物來源有機肥料市場佔有率的42.5%。印度和中國正透過慷慨的補貼計畫和強制性的營養物減量措施來推動市場成長。在印度,印度農民肥料合作社(IFFCO)和克里沙克·巴拉蒂合作社(KRIBHCO)是領先的肥料合作社,透過支持國內生物來源有機肥料市場,為農業永續性做出貢獻。這些合作社除了主要經營化肥業務外,還生產包括生物肥料和堆肥在內的各種環保產品,確保本地供應。在中國,政府對從化肥轉向生物肥料的經銷商提供稅收優惠,加速了生物肥料在山東和河南兩省通路的滲透。
非洲的經濟成長速度最快,預計到2031年年複合成長率(CAGR)將達到8.8%。在奈及利亞,政府已撥出大量預算,向小規模農戶發放代金券以支持微生物產品,早期玉米試驗種植已顯示出顯著的增產效果。在南非,西開普省水果種植區的生物來源農業材料聯合資助計畫已大幅減少了合成氮肥的使用。然而,冷鏈基礎設施不足和產品保存期限有限等挑戰仍然阻礙這些努力充分發揮其潛力。儘管存在這些障礙,但來自美國國際開發署(USAID)和比爾及梅琳達·蓋茲基金會等機構的捐助支持計畫正在穩步擴大先導計畫的範圍。
2025年,北美和歐洲市場收益貢獻顯著,這主要得益於補貼計畫和嚴格的硝酸鹽法規推動的穩定年成長。在美國,保護潔淨科技計畫(Conservation Stewardship Program)的補貼顯著提高了中西部地區間作農戶的採用率。加拿大的農業清潔技術計劃(Agricultural Clean Technology Program)為農場生物反應器的聯合資金籌措提供了大量資金,從而大幅降低了生產成本。在歐洲,德國、法國和荷蘭等國由於嚴格的氮排放限制,採用率最高;西班牙和義大利的採用速度較慢,但生技藥品銷售額在柑橘和橄欖出口的推動下實現了顯著成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 聯邦政府對再生農業的獎勵措施
- 加強對化肥的監管
- 有機加工食品製造商的需求不斷成長
- 微生物菌叢混合物的快速傳播
- 一個由農民主導的數據合作社正在揭示根植於當地社區的土壤健康。
- 農場生物反應器平台可降低生產成本
- 市場限制因素
- 高溫氣候下保存期限短
- 各國之間存在的、分散的註冊障礙
- 除了特色作物外,農民對自己的產品了解甚少。
- 分散式生產中的生物污染風險
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 微生物
- 根瘤菌
- 固氮菌
- 固氮螺菌
- 藍藻
- 磷酸鹽可溶性細菌
- 菌根
- 其他微生物
- 有機殘留物
- 綠肥
- 魚粉
- 骨粉
- 油籽粕
- 其他
- 微生物
- 透過使用
- 穀物和穀類
- 豆類和油籽
- 水果和蔬菜
- 經濟作物
- 草坪和觀賞植物
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Novonesis Group
- Bioceres Crop Solutions Corp
- Lallemand, Inc.
- Premier Tech Ltd.(Gestion Bernard Belanger Ltee)
- Corteva Agriscience
- Indian Farmers Fertiliser Cooperative Limited(IFFCO)
- Krishak Bharati Cooperative Limited(KRIBHCO)
- Madras Fertilizers Limited(MFL)
- T. Stanes and Company Limited(Amalgamations Group)
- String Bio Private Limited
- UPL Limited
- Kiwa Bio-Tech Products Group Corporation
- Protan AG
- Savio Bio Organic and Fertilizers Private Limited(SBOF)
- Yara International ASA
- Coromandel International Limited
- Sustane Natural Fertilizer, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the biological organic fertilizer market size is projected to grow from USD 12.62 billion in 2025 to USD 13.79 billion in 2026 and is forecast to reach USD 20.81 billion by 2031 at an 8.58% CAGR over 2026-2031.
This report is Segmented by Type (Microorganism and Organic Residues), by Application (Grains and Cereals, Pulses and Oilseeds, Fruits and Vegetables, Commercial Crops, and Turf and Ornamentals), and by Geography (North America, Europe, Asia-Pacific, South America, The Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Biological Organic Fertilizer Market Trends and Insights
Federal Incentives for Regenerative Farming
Across major farming regions, government programs refund a large share of biological input costs, tilting the economic calculus in favor of microbial products. In December 2025, the United States Department of Agriculture (USDA) launched a USD 700 million Regenerative Pilot Program to promote practices that enhance soil health, water quality, and biodiversity. The funding is allocated through the Natural Resources Conservation Service (NRCS), with USD 400 million provided via the Environmental Quality Incentives Program (EQIP) and USD 300 million through the Conservation Stewardship Program (CSP). India encourages the use of biological fertilizers through subsidies provided under programs such as the Capital Investment Subsidy Scheme (CISS), which offers up to 100% assistance to government agencies and 25% assistance to private units for production. Farmers also benefit from financial support under the Paramparagat Krishi Vikas Yojana (PKVY) and receive incentives to reduce chemical fertilizer use through the PM-PRANAM initiative. Under the Common Agricultural Policy (CAP) 2023-2027, the European Union requires that at least 25% of the direct payments budget be dedicated to voluntary eco-schemes that support climate and environmentally sustainable practices. Together, these incentives shorten payback periods, making biological products economically attractive even in row-crop systems.
Escalating Restrictions on Synthetic Fertilizers
Regulators worldwide are capping allowable nitrogen and phosphorus loads, creating a durable pull for the biological organic fertilizer market. The European Union is implementing restrictions on synthetic fertilizers to achieve a reduction in nutrient losses of at least 50% by 2030, as part of the "Farm to Fork" strategy. This initiative also aims to reduce overall fertilizer use by 20%. New regulations (EU 2019/1009) aim to enhance environmental standards, encourage the use of organic alternatives, and limit the use of microplastics, including polymer coatings on fertilizers, beginning in 2026. China enforces restrictions on chemical fertilizer use through stringent registration requirements, bans on high-toxicity products, and a national directive aimed at achieving zero growth in usage to address environmental concerns. Even fertilizer majors are repositioning. Yara International ASA increased the share of its research budget dedicated to microbes. While enforcement intensity varies by region, progressive restrictions are visible across developed and emerging markets, anchoring a structural shift toward biological inputs.
Short Shelf Life in High-Temperature Climates
Microbial viability declines significantly when exposed to temperatures above 30 °C, limiting its use in tropical regions. The absence of adequate cold-chain infrastructure further intensifies this issue, as only a small proportion of rural distribution points in Africa are equipped with refrigeration facilities. This limitation results in a considerable percentage of product returns in countries with warmer climates, such as Nigeria and Kenya, during the hotter periods of the year. Although encapsulation provides some protection, it also significantly increases costs, creating financial challenges for smallholder farmers. Efforts to address this issue, such as the introduction of solar-powered village cold rooms in India, remain in the early stages, with the number of operational units still too limited to effectively reduce the risks associated with temperature sensitivity in these regions.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Microbial Consortia Blends
- Farmer-Led Data Cooperatives Unlocking Localized Soil Health Insights
- Low Farmer Awareness Outside Specialty Crops
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Microorganisms are the largest type, capturing 57.3% of the biological organic fertilizer market share in 2025 and are forecast to grow at a 10.5% CAGR through 2031, the highest among all categories. Rhizobium is anticipated to hold a significant share of the biological organic fertilizer market, as legume growers across regions such as North America and Asia increasingly adopt inoculants to reduce their reliance on synthetic nitrogen while maintaining crop productivity. Azospirillum is experiencing rapid growth, driven by its adoption in large-scale maize farming operations aiming to achieve similar reductions in nitrogen use. The use of phosphate-solubilizing bacteria and mycorrhizal fungi is also growing steadily, particularly in areas where phosphorus deficiency is prevalent or where the economic considerations of perennial crops make premium-priced solutions viable. This trend is especially notable in crops such as coffee, almonds, and avocados.
Organic residues accounted for the remaining share in 2025. Green manure leads this sub-segment but faces challenges in mechanized grain belts due to its labor-intensive nature. Fish and bone meals perform well in high-value vegetable systems, as their slow-release phosphorus complements tight irrigation schedules. Although region-specific subsidies support neem and castor oil cakes, scalability in export-oriented markets is limited by concerns over heavy-metal residues and inconsistent nutrient analysis. The adoption of organic residues is influenced by regional agricultural practices, availability of raw materials, and the cost-effectiveness of these inputs compared to synthetic alternatives. Efforts to improve nutrient consistency and address contamination concerns are critical for enhancing their adoption in global markets.
Complete Report Scope:
- By Type
- Microorganism
- Rhizobium
- Azotobacter
- Azospirillum
- Blue-green Algae
- Phosphate-Solubilizing Bacteria
- Mycorrhiza
- Other Microorganisms
- Organic Residues
- Green Manure
- Fish Meal
- Bone Meal
- Oil Cakes
- Others
- Microorganism
- By Application
- Grains and Cereals
- Pulses and Oilseeds
- Fruits and Vegetables
- Commercial Crops
- Turf and Ornamentals
- By Geography
- North America
- United States
- Canada
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific is the largest geography and commanded 42.5% of the biological organic fertilizer market share in 2025. India and China anchor growth via generous subsidy pools and mandatory nutrient-reduction directives. In India, the Indian Farmers Fertiliser Cooperative Limited (IFFCO) and Krishak Bharati Cooperative Limited (KRIBHCO) are prominent fertilizer cooperatives contributing to agricultural sustainability by supporting the domestic biological fertilizer market. They manufacture various eco-friendly products, including biofertilizers and compost, alongside their primary chemical fertilizer operations, securing local supply. China offers tax rebates to distributors that swap synthetic inventory for biologicals, accelerating channel penetration in Shandong and Henan provinces.
Africa records the fastest CAGR of 8.8% through 2031. Nigeria has allocated a significant budget for smallholder vouchers to support microbial products, with initial maize trials showing a notable increase in yields. In South Africa, collaborative funding for biological inputs in the Western Cape fruit-growing region has led to a significant reduction in synthetic nitrogen use. However, challenges such as gaps in cold-chain infrastructure and limitations in product shelf life continue to restrict the full potential of these initiatives. Despite these obstacles, donor-supported programs from organizations such as the United States Agency for International Development (USAID) and the Bill and Melinda Gates Foundation are steadily expanding the scope of pilot projects.
North America and Europe contributed significantly to the 2025 market revenue, with steady annual growth driven by reimbursement programs and strict nitrate regulations. In the United States, payments under the Conservation Stewardship Program led to a substantial annual increase in adoption among row-crop operators in the Midwest. Canada's Agricultural Clean Technology Program provided substantial funding to support the co-financing of on-farm bioreactors, resulting in a significant reduction in production costs. In Europe, countries such as Germany, France, and the Netherlands showed the fastest adoption rates due to stringent nitrogen limits, while Spain and Italy experienced slower adoption but still recorded notable growth in biological sales, supported by exports of citrus and olives.
- Novonesis Group
- Bioceres Crop Solutions Corp
- Lallemand, Inc.
- Premier Tech Ltd. (Gestion Bernard Belanger Ltee)
- Corteva Agriscience
- Indian Farmers Fertiliser Cooperative Limited (IFFCO)
- Krishak Bharati Cooperative Limited (KRIBHCO)
- Madras Fertilizers Limited (MFL)
- T. Stanes and Company Limited (Amalgamations Group)
- String Bio Private Limited
- UPL Limited
- Kiwa Bio-Tech Products Group Corporation
- Protan AG
- Savio Bio Organic and Fertilizers Private Limited (SBOF)
- Yara International ASA
- Coromandel International Limited
- Sustane Natural Fertilizer, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal incentives for regenerative farming
- 4.2.2 Escalating restrictions on synthetic fertilizers
- 4.2.3 Rising demand from organic packaged-food processors
- 4.2.4 Rapid adoption of microbial consortia blends
- 4.2.5 Farmer-led data cooperatives unlocking localized soil health insights
- 4.2.6 On-farm bioreactor platforms lowering production costs
- 4.3 Market Restraints
- 4.3.1 Short shelf-life in high-temperature climates
- 4.3.2 Fragmented, country-specific registration hurdles
- 4.3.3 Low farmer awareness outside specialty crops
- 4.3.4 Biocontamination risks during decentralized production
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Microorganism
- 5.1.1.1 Rhizobium
- 5.1.1.2 Azotobacter
- 5.1.1.3 Azospirillum
- 5.1.1.4 Blue-green Algae
- 5.1.1.5 Phosphate-Solubilizing Bacteria
- 5.1.1.6 Mycorrhiza
- 5.1.1.7 Other Microorganisms
- 5.1.2 Organic Residues
- 5.1.2.1 Green Manure
- 5.1.2.2 Fish Meal
- 5.1.2.3 Bone Meal
- 5.1.2.4 Oil Cakes
- 5.1.2.5 Others
- 5.1.1 Microorganism
- 5.2 By Application
- 5.2.1 Grains and Cereals
- 5.2.2 Pulses and Oilseeds
- 5.2.3 Fruits and Vegetables
- 5.2.4 Commercial Crops
- 5.2.5 Turf and Ornamentals
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Rest of North America
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Spain
- 5.3.2.5 Italy
- 5.3.2.6 Russia
- 5.3.2.7 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 Australia
- 5.3.3.5 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Nigeria
- 5.3.6.3 Rest of Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Novonesis Group
- 6.4.2 Bioceres Crop Solutions Corp
- 6.4.3 Lallemand, Inc.
- 6.4.4 Premier Tech Ltd. (Gestion Bernard Belanger Ltee)
- 6.4.5 Corteva Agriscience
- 6.4.6 Indian Farmers Fertiliser Cooperative Limited (IFFCO)
- 6.4.7 Krishak Bharati Cooperative Limited (KRIBHCO)
- 6.4.8 Madras Fertilizers Limited (MFL)
- 6.4.9 T. Stanes and Company Limited (Amalgamations Group)
- 6.4.10 String Bio Private Limited
- 6.4.11 UPL Limited
- 6.4.12 Kiwa Bio-Tech Products Group Corporation
- 6.4.13 Protan AG
- 6.4.14 Savio Bio Organic and Fertilizers Private Limited (SBOF)
- 6.4.15 Yara International ASA
- 6.4.16 Coromandel International Limited
- 6.4.17 Sustane Natural Fertilizer, Inc.
7 Market Opportunities and Future Outlook

 2026-2030年全球生物肥料市場
 化肥工程解決方案市場-2026-2032年全球預測
 2034年生物肥料微生物材料市場預測-按微生物類型、製劑形式、作物類型、應用、最終用戶和地區分類的全球分析
 歐洲生物肥料:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲生物來源有機肥料:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)以固氮菌的生物肥料市場-2026-2032年全球市場預測生物肥料市場-2026-2032年全球市場預測生物肥料市場預測至2034年—按產品類型、作物類型、微生物、配方、應用方法和地區分類的全球分析中東和非洲生物肥料:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 基於固氮菌的生物肥料市場規模、佔有率和成長分析:按產品形式、作物類型、應用方法、最終用戶、銷售管道、分銷通路和地區分類-2026-2033年產業預測