


 |
市場調查報告書
商品編碼
2120395
塑膠蓋子與封口裝置:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Plastic Caps And Closures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年塑膠蓋子與封口裝置市場價值為 782 萬噸,預計到 2031 年將從 2026 年的 818 萬噸成長至 1027 萬噸,預測期(2026-2031 年)的複合年成長率為 4.64%。
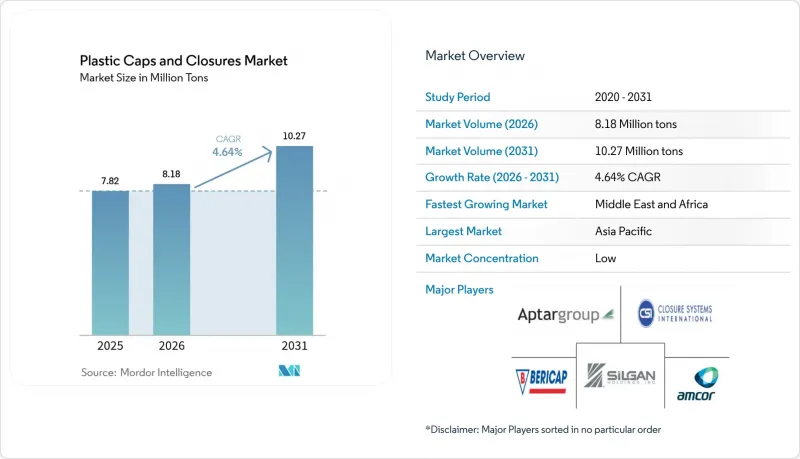
本報告按產品類型(螺旋蓋、分配蓋等)、原料(聚丙烯 (PP)、高密度聚苯乙烯(HDPE) 等)、製造流程(壓縮成型、射出成型、後成型熱封帶)、終端用戶產業(飲料、食品等)和地區進行細分。市場規模和預測以數量(百萬噸)為單位。
全球塑膠蓋子與封口裝置市場的趨勢和洞察。
歐盟一次性塑膠指令強制要求使用帶有繫繩的瓶蓋。
歐盟一項將於2024年7月生效的規定,要求3公升以下飲料容器必須使用繫繩式瓶蓋。這項規定促使相關設計標準進行修訂,並大規模設備升級。領先的系統供應商正在推出多種安裝方案,確保瓶蓋連接牢固,同時不影響生產線速度,從而在實現減少浪費目標的同時,保障消費者的使用體驗。北美品牌商也在加州即將實施的法規之前,率先試行類似的解決方案,顯示全球正向繫繩式技術轉型。
東協地區飲料工廠的無菌PET灌裝生產線數量迅速增加
新型無菌填充機推動了對輕質無菌瓶蓋的需求,不僅將保存期限延長至12個月,還減少了60.1%的塑膠用量。越南和印尼的計畫清晰地展現了這一趨勢的規模,僅一家工廠每年就能額外產生2萬噸瓶蓋需求,這與支持循環經濟目標的再生PET舉措密切相關。
丙烯和乙烯合約價格的波動正在影響PP/PE的利潤率。
原料價格波動正在削弱嚴重依賴聚丙烯和聚乙烯的瓶蓋製造商的獲利能力。為了應對這種成本衝擊,各公司正透過避險交易、混合再生樹脂以及持續推進自動化專案來降低加工成本。
細分市場分析
預計到2025年,螺旋蓋將佔據塑膠蓋子與封口裝置市場佔有率的65.02%,這主要得益於其與高速飲料、食品和藥品生產線的廣泛相容性。螺旋蓋成本更低、密封性能可靠,即使到2031年,分裝產品的複合年成長率預計達到6.18%,螺旋蓋仍將繼續保持其主導地位。分裝包裝形式在調味品和個人保健產品中越來越受歡迎,因為消費者高度關注數量控制和衛生問題。防篡改和兒童安全蓋正受益於日益嚴格的安全法規,這些法規正在重塑非處方藥的包裝。
在啤酒和高階烈酒行業,皇冠蓋和旋蓋仍然扮演著重要角色,因為這些行業都重視傳統和商店形象。按扣式設計適用於需要快速重新密封的家用化學品。對繫繩式瓶蓋日益成長的需求正在推動所有旋蓋的重新設計,使瓶蓋創新與法規遵循直接相關。採用輕質瓶的終端用戶更傾向於使用先進的螺紋形狀,這種形狀既能減少樹脂用量,又不影響密封完整性,這支撐了旋蓋在塑膠蓋子與封口裝置市場的長期發展前景。
到2025年,聚丙烯將佔據塑膠蓋子與封口裝置市場55.71%的佔有率。其優異的耐化學性、熱穩定性和加工性能使其在食品和製藥應用領域中佔據了重要地位。高密度聚苯乙烯適用於需要抗衝擊性的工業化學品包裝,而低密度聚乙烯則用於軟性按扣式封口。 PET產品持續成長,因為單一材料包裝簡化了回收系統,並可實現符合歐盟法規的固定式包裝設計。
生物基和化學回收樹脂正以7.62%的複合年成長率快速成長。各大品牌正加大投資,以因應擴大生產者責任延伸(EPR)費用並滿足消費者對永續性的期望。早期採用植物來源聚丙烯的商業生產線正為低碳蓋子與封口裝置鋪路。儘管供應鏈認證、顏色一致性和成本平衡仍然是挑戰,但化學技術的不斷進步預計將在2030年後加速塑膠蓋子與封口裝置產業的應用。
區域分析
到2025年,亞太地區將佔全球產量的40.12%。這主要得益於中國的規模優勢、日本的品質標準以及印度飲料和製藥業的快速發展。東協對無菌包裝投資的激增進一步推動了該地區蓋子與封口裝置的消費,而循環經濟政策則加速了再生PET的普及應用。澳洲遵守國際藥品安全法規,促進了區域間貿易的協調,並推動了對兒童安全專用瓶蓋的需求。
預計中東和非洲地區將錄得最高成長率,到2031年複合年成長率將達到7.78%。沙烏地阿拉伯和阿拉伯聯合大公國(阿拉伯聯合大公國)的多元化舉措正在吸引外資進入包裝產業,而土耳其則正利用其戰略出口位置優勢。奈及利亞的人口成長和南非製造地的擴張正在推動飲料和家居用品瓶蓋需求的成長。促進該地區價值創造的改革正在支持塑膠蓋子與封口裝置市場的未來產能擴張。
在歐洲,監管阻力與永續性之間正尋求平衡。關於「繫繩式瓶蓋」的法規要求對生產線進行高成本的維修,同時也拓展了設計差異化的可能性。德國在技術合規計畫方面主導,法國致力於推廣高階設計,而英國的生產者責任延伸(EPR)收費系統正在重塑成本模式。西班牙和義大利正利用其成熟的食品飲料出口來維持對蓋子與封口裝置的需求。全部區域對循環經濟目標的承諾正在加速向單一材料和可回收瓶蓋的過渡,即使在宏觀經濟成長放緩的情況下,也保持市場重要性。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟的《一次性塑膠指令》強制要求使用帶繩瓶蓋。
- 東協地區飲料工廠的無菌PET灌裝生產線數量迅速增加
- 美國和加拿大製藥業向兒童安全PP瓶蓋過渡。
- 拉丁美洲乳製品市場正轉向採用帶螺旋蓋的山形蓋頂紙盒。
- 市場限制因素
- 丙烯和乙烯合約價格的波動會影響聚丙烯和聚乙烯的利潤率。
- 高階烈酒市場轉向使用鋁製ROPP包裝正在蠶食塑膠的市場佔有率。
- 產業價值鏈分析
- 監理展望
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 螺帽
- 分配蓋
- 兒童安全帽
- 防篡改蓋
- 皇冠帽
- ROPP(滾珠防盜劑)
- 按扣/按壓式帽
- 按成分
- 聚丙烯(PP)
- 高密度聚苯乙烯(HDPE)
- 低密度聚乙烯(LDPE)
- 聚對苯二甲酸乙二醇酯(PET)
- 聚氯乙烯(PVC)
- 其他原料
- 透過製造技術
- 壓縮成型
- 射出成型
- 模壓成型後TE波段的應用
- 按最終用途行業分類
- 飲料
- 食物
- 製藥
- 個人護理化妝品
- 家用和工業化學品
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Silgan Holdings Inc.
- Amcor PLC
- Crown Holdings Inc.
- AptarGroup Inc.
- BERICAP GmbH & Co. KG
- Guala Closures Group
- Closure Systems International
- United Caps
- Tecnocap SpA
- Blackhawk Molding Co.
- Evergreen Packaging LLC
- Tetra Pak International SA
- ALPLA Group
- Pact Group
- Ball Corporation
- Smurfit Westrock
- Gerresheimer AG
- O.Berk Company
- Karl H. Burkle GmbH(Burkle)
第7章 市場機會與未來展望
According to Mordor Intelligence, the plastic caps and closures market size was valued at 7.82 million tons in 2025 and estimated to grow from 8.18 million tons in 2026 to reach 10.27 million tons by 2031, at a CAGR of 4.64% during the forecast period (2026-2031).
This report is Segmented by Product Type (Screw Closures, Dispensing Closures, and More), Raw Material (Polypropylene (PP), High-Density Polyethylene (HDPE), and More), Manufacturing Technology (Compression Molding, Injection Molding, and Post-Mold TE-Band Application), End-Use Industry (Beverages, Food, and More), and Geography. The Market Sizes and Forecasts are Provided in Terms of Volume (Million Tons).
Global Plastic Caps And Closures Market Trends and Insights
EU Single-Use Plastics Directive Mandating Tethered Caps Adoption
The July 2024 EU requirement that beverage containers below 3 liters carry tethered closures rewired design norms and forced widespread capital upgrades. Leading system suppliers introduced multiple attachment concepts that keep caps connected without compromising line speeds, enhancing litter-reduction goals while safeguarding consumer ergonomics. Brand owners in North America are trialing the same solutions ahead of pending Californian rules, signalling a global pivot toward attachment technology.
Surge in Aseptic PET Bottling Lines Across ASEAN Beverage Plants
New aseptic fillers extend shelf life up to 12 months and use 60.1% less plastic, driving demand for lightweight yet sterile closures. Projects in Vietnam and Indonesia illustrate the scale, with single facilities adding more than 20,000 tons of annual closure demand tied to recycled PET initiatives that back circular-economy targets.
Volatile Propylene and Ethylene Contract Prices Impacting PP/PE Margins
Feedstock swings erode margin stability for closure manufacturers that rely heavily on polypropylene and polyethylene. Firms counter the cost shock through hedging, recycled-resin blends, and ongoing automation programs that compress conversion costs.
Other drivers and restraints analyzed in the detailed report include:
- Pharma Shift to Child-Resistant PP Closures in U.S. and Canada
- Latin American Dairy Pivot Toward Gable-Top Cartons with Screw Caps
- Rising Aluminum ROPP Substitution in Premium Spirits, Cannibalising Plastic
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Screw closures captured 65.02% of plastic caps and closures market share in 2025 thanks to universal compatibility with high-speed beverage, food, and pharmaceutical lines. Their low unit cost and dependable seal underpin enduring dominance, even as dispensing variants post a 6.18% CAGR through 2031. Dispensing formats gain favor in condiments and personal-care SKUs where portion control and hygiene boost consumer appeal. Tamper-evident and child-resistant formats benefit from stricter safety regulations that reshape over-the-counter drug packaging.
Crown and ROPP closures retain relevance in beer and premium spirits where tradition and shelf presence matter. Snap-on designs serve household chemicals seeking quick reclose functionality. Rising tethered-cap requirements are catalyzing redesign projects across all screw variants, linking closure innovation directly to compliance. End-users adopting light-weight bottles favor advanced thread profiles that cut resin use without compromising seal integrity, supporting the long-term outlook for screw formats in the plastic caps and closures market.
Polypropylene held 55.71% share of the plastic caps and closures market size in 2025. Its chemical resistance, heat stability, and processability secure its place in food and pharmaceutical applications. High-density polyethylene supports industrial chemical packs that need impact tolerance, while low-density polyethylene is used in flexible snap closures. PET variants grow as single-material packages simplify recycling systems and enable tethered designs compliant with EU rules.
Bio-based and chemically recycled resins expand at 7.62% CAGR. Brands invest to meet EPR fee modulation and consumer sustainability expectations. Early commercial lines running plant-based polypropylene highlight the pathway to lower-carbon closures. Supply chain qualification, color stability, and cost parity remain hurdles, yet scaling chemistry improvements portend faster adoption beyond 2030 in the plastic caps and closures industry.
Complete Report Scope:
- By Product Type
- Screw Closures
- Dispensing Closures
- Child-Resistant Closures
- Tamper-Evident Closures
- Crown Closures
- ROPP (Roll-On Pilfer-Proof)
- Snap / Press-on Closures
- By Raw Material
- Polypropylene (PP)
- High-Density Polyethylene (HDPE)
- Low-Density Polyethylene (LDPE)
- Polyethylene Terephthalate (PET)
- Polyvinyl Chloride (PVC)
- Other Raw Material
- By Manufacturing Technology
- Compression Molding
- Injection Molding
- Post-Mold TE-Band Application
- By End-Use Industry
- Beverages
- Food
- Pharmaceuticals
- Personal Care and Cosmetics
- Household and Industrial Chemicals
- Other End-Use Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific accounted for 40.12% of global volumes in 2025, anchored by China's scale, Japan's quality standards, and India's expanding beverage and pharma sectors. ASEAN's aseptic investment wave further intensifies regional closure consumption, while circular-economy policies fast-track recycled PET uptake. Australia's alignment with international pharma safety rules harmonizes regional trade and drives demand for specialized child-resistant formats.
Middle East and Africa post the fastest 7.78% CAGR to 2031. Diversification initiatives in Saudi Arabia and the United Arab Emirates invite foreign investment in packaging, while Turkey leverages its strategic export location. Nigeria's population growth and South Africa's manufacturing base increase closure demand for beverages and household products. Regional reforms encouraging local value addition support future capacity builds in the plastic caps and closures market.
Europe balances regulatory headwinds and sustainability opportunities. Tethered-cap rules enforce expensive line retrofits yet unlock design differentiation. Germany leads technical compliance projects, France drives premium design, and the United Kingdom's EPR fee schedules reshape cost models. Spain and Italy utilize established food and beverage exports to sustain closure demand. Collective emphasis on circular-economy targets accelerates the shift toward mono-material and recycled-content caps, preserving market relevance despite slower macro growth.
- Silgan Holdings Inc.
- Amcor PLC
- Crown Holdings Inc.
- AptarGroup Inc.
- BERICAP GmbH & Co. KG
- Guala Closures Group
- Closure Systems International
- United Caps
- Tecnocap S.p.A.
- Blackhawk Molding Co.
- Evergreen Packaging LLC
- Tetra Pak International S.A.
- ALPLA Group
- Pact Group
- Ball Corporation
- Smurfit Westrock
- Gerresheimer AG
- O.Berk Company
- Karl H. Burkle GmbH (Burkle)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Single-Use Plastics Directive Mandating Tethered Caps Adoption
- 4.2.2 Surge in Aseptic PET Bottling Lines Across ASEAN Beverage Plants
- 4.2.3 Pharma Shift to Child-Resistant PP Closures in U.S. and Canada
- 4.2.4 Latin American Dairy Pivot Toward Gable-Top Cartons with Screw Caps
- 4.3 Market Restraints
- 4.3.1 Volatile Propylene and Ethylene Contract Prices Impacting PP/PE Margins
- 4.3.2 Rising Aluminum ROPP Substitution in Premium Spirits, Cannibalising Plastic
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Product Type
- 5.1.1 Screw Closures
- 5.1.2 Dispensing Closures
- 5.1.3 Child-Resistant Closures
- 5.1.4 Tamper-Evident Closures
- 5.1.5 Crown Closures
- 5.1.6 ROPP (Roll-On Pilfer-Proof)
- 5.1.7 Snap / Press-on Closures
- 5.2 By Raw Material
- 5.2.1 Polypropylene (PP)
- 5.2.2 High-Density Polyethylene (HDPE)
- 5.2.3 Low-Density Polyethylene (LDPE)
- 5.2.4 Polyethylene Terephthalate (PET)
- 5.2.5 Polyvinyl Chloride (PVC)
- 5.2.6 Other Raw Material
- 5.3 By Manufacturing Technology
- 5.3.1 Compression Molding
- 5.3.2 Injection Molding
- 5.3.3 Post-Mold TE-Band Application
- 5.4 By End-Use Industry
- 5.4.1 Beverages
- 5.4.2 Food
- 5.4.3 Pharmaceuticals
- 5.4.4 Personal Care and Cosmetics
- 5.4.5 Household and Industrial Chemicals
- 5.4.6 Other End-Use Industry
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Nigeria
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Silgan Holdings Inc.
- 6.4.2 Amcor PLC
- 6.4.3 Crown Holdings Inc.
- 6.4.4 AptarGroup Inc.
- 6.4.5 BERICAP GmbH & Co. KG
- 6.4.6 Guala Closures Group
- 6.4.7 Closure Systems International
- 6.4.8 United Caps
- 6.4.9 Tecnocap S.p.A.
- 6.4.10 Blackhawk Molding Co.
- 6.4.11 Evergreen Packaging LLC
- 6.4.12 Tetra Pak International S.A.
- 6.4.13 ALPLA Group
- 6.4.14 Pact Group
- 6.4.15 Ball Corporation
- 6.4.16 Smurfit Westrock
- 6.4.17 Gerresheimer AG
- 6.4.18 O.Berk Company
- 6.4.19 Karl H. Burkle GmbH (Burkle)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 美國塑膠瓶蓋:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)歐洲塑膠瓶蓋和封蓋:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)北美塑膠瓶蓋和封蓋市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026年全球無內襯瓶蓋市場報告
 塑膠蓋子與封口裝置市場:2026-2032年全球市場預測(按產品類型、材料、製造流程、最終用途和分銷管道分類)
 塑膠瓶蓋及瓶蓋市場報告:按產品類型、原料、容器類型、技術、最終用途和地區分類(2026-2034 年)
 全球塑膠蓋子與封口裝置市場:市場規模、佔有率、成長和行業分析:按材料、產品類型、最終用途和地區分類的預測(至2034年)南美洲塑膠瓶蓋和封蓋:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 全球塑膠瓶蓋和封蓋市場規模、佔有率、趨勢和成長分析報告(2026-2034年)2026年全球塑膠瓶蓋和封蓋市場報告