


 |
市場調查報告書
商品編碼
2119878
英國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)United Kingdom Data Center Networking - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
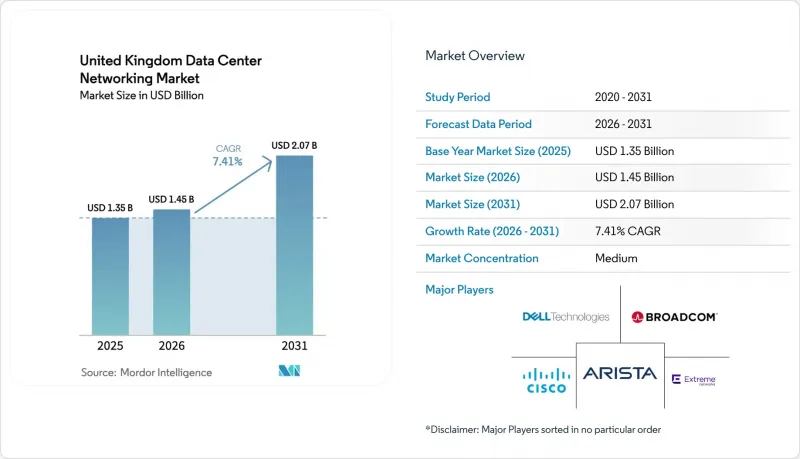
根據 Mordor Intelligence 預測,英國資料中心網路市場規模將從 2025 年的 13.5 億美元成長到 2026 年的 14.5 億美元,然後在 2031 年達到 20.7 億美元,2026 年至 2031 年的複合年成長率為 7.41%。
本報告按組件(產品和服務)、最終用戶(IT和電信、銀行、金融服務和保險 (BFSI)、政府和國防、其他)、資料中心類型(託管、超大規模資料中心業者雲端服務供應商、邊緣和微型資料中心)以及頻寬(10GbE 以下、25-40GbE、其他)進行細分。市場預測以美元 (USD) 為單位。
英國資料中心網路市場趨勢與洞察
人工智慧/機器學習和高效能運算的激增正在推動 400/800G 的升級。
不斷成長的生成式人工智慧叢集需要超低延遲的網路架構,而傳統的 10/25G 連結無法滿足這項需求。 NVIDIA 的 Spectrum-X 平台吞吐量是傳統乙太網路架構的 1.6 倍,而 Arista 的 7060X6 AI 葉交換器和 7800R4 AI 脊交換器的吞吐量分別高達 51.2 Tbps 和 460 Tbps,足以滿足集群級聚合的需求量。 Meta 部署的分散式 400G 交換器進一步強化了超超大規模資料中心業者採用更深層的葉脊式架構的趨勢,這種架構可以縮短東西向通道並最大限度地減少尾流延遲。思科決定將 Silicon One ASIC 整合到 NVIDIA 的乙太網路協定堆疊中,這標誌著通用晶片與以人工智慧為中心的軟體管線正在融合,企業現在認為這是面向未來發展的關鍵所在。
政府的CNI認證和140億英鎊的人工智慧計畫促進了支出。
2024年9月獲得CNI認證後,資料中心營運商將優先進入許可權規劃和安全支持,從而直接促成創紀錄的資本投資,例如Vantage公司斥資120億英鎊(164.7億美元)建設的多園區項目和Nscale公司斥資25億美元建設的國家人工智慧設施。該行動計畫還將創建“人工智慧成長區”,配備專用配電走廊,首站選在卡勒姆,加快先前阻礙容量擴張的許可核准流程。 2030年將公共運算資源增加20倍的計畫(包括蘇格蘭耗資7.5億英鎊(10.2915億美元)的超級電腦)將為滿足公共和學術工作負載對800G互連的多年需求奠定基礎。
英格蘭東南部電網面臨的限制因素
英國國家電網警告稱,未來十年資料中心電力需求可能增加六倍,但倫敦的電力走廊目前已接近運作。近期,英國國務大臣否決了在倫敦西部綠帶建設計畫,這凸顯了城市規劃法規如何加劇電網壓力,導致電力需求轉向倫敦東部的羅姆福德。在那裡,30兆瓦的「綠山」計畫確保了更快的網路連線。儘管英國天然氣和電力市場管理局(Ofgem)的網路連接等待名單改革計劃可能降低延遲,但變電站的建設需要數年時間,限制了短期內的部署速度。
細分市場分析
到2025年,該產品領域將佔據英國資料中心網路市場76.20%的佔有率。這反映了市場對交換器、路由器、應用傳遞控制器、安全設備和光連接模組等實體基礎設施基礎設備的強勁需求。思科的Nexus 9364E-SG2 64埠800G交換器是專為AI規模叢集最佳化的硬體的典範,擁有51.2 Tbps的頻寬和大容量片上緩衝區,可有效緩解微突發流量。隨著儲存區域網路(SAN)向NVMe over Fabrics遷移,以及安全閘道器整合能夠進行線速解密的AI驅動偵測引擎,硬體需求仍然強勁。
儘管服務領域規模較小,但預計其複合年成長率將達到 7.55%,因為企業傾向於將複雜人工智慧架構的設計、整合和維運管理外包。顧問公司正在部署思科 ACI 和 VMware NSX 等軟體定義控制器,以實現混合雲端中各項計畫的自動化。同時,開放原始碼的OpenDaylight 也越來越受到尋求廠商獨立性的企業的青睞。隨著 Coherent 的 2X400G-FR4 Lite 收發器等矽光電元件的普及,企業擴大將光層的調優和生命週期管理委託給專業的服務供應商。
到2025年,IT和電信公司將佔據英國資料中心網路市場規模的36.80%,這主要得益於為維持寬頻和雲端服務品質而進行的持續升級。銀行和保險公司也正在進行大量投資,例如Sterling Bank利用數位房地產互連技術來支援純行動端業務,交易延遲低於20毫秒。
隨著工業4.0推動營運技術(OT)感測器和雲端分析的融合,預計到2031年,製造業將以7.95%的複合年成長率(CAGR)實現最高成長。利潔時集團正利用Azure IoT連接工廠資產,並從中獲取預測性維護洞察,從而將停機時間減少10%,能耗降低3%。政府、國防、醫療保健和媒體產業也正在向人工智慧驅動的工作流程轉型,但監管採購週期的影響阻礙了這些產業的轉型速度與製造業同步。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人工智慧/機器學習和高效能運算的激增正在推動 400/800G 的升級。
- 政府對CNI進行認證,並推動140億英鎊的人工智慧支出。
- 雲端和混合多重雲端中的流量爆炸性成長
- 脊椎-葉片式建築的永續性計劃
- 在倫敦郊區建設邊緣資料中心
- 矽光電1.6T 乙太藍圖
- 市場限制因素
- 英格蘭東南部電網面臨的限制因素
- 800G光學模組和 ASIC 的成本和前置作業時間都在飆升。
- 能源和用水量的新揭露規則
- 超大規模資料中心業者資料中心的資料傳輸費用和廠商鎖定阻礙了開放網路的普及。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 按組件
- 產品
- 乙太網路切換器
- 路由器
- 儲存區域網路(SAN)
- 應用傳遞控制器(ADC)
- 網路安全設備
- 軟體定義網路 (SDN) 控制器
- 光連接模組
- 服務
- 安裝與整合
- 培訓和諮詢
- 支援與維護
- 主機服務
- 產品
- 最終用戶
- 資訊科技/通訊
- 銀行、金融服務和保險(BFSI)
- 政府/國防
- 媒體與娛樂
- 醫療保健和生命科學
- 製造業和工業
- 其他最終用戶
- 依資料中心類型
- 搭配
- 超大規模資料中心業者雲端服務供應商
- 邊緣微資料中心
- 頻寬
- 10GbE 或更低
- 25~40GbE
- 50~100GbE
- 超過 100GbE
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Arista Networks Inc.
- Broadcom Inc.
- Cisco Systems Inc.
- Dell Technologies Inc.
- Extreme Networks Inc.
- Hewlett Packard Enterprise(HPE)
- Huawei Technologies Co. Ltd.
- IBM Corporation
- Intel Corporation
- Juniper Networks Inc.
- Lenovo Group Ltd.
- Marvell Technology Group
- NEC Corporation
- NVIDIA Corporation(incl. Cumulus)
- Nokia Corporation
- Schneider Electric SE
- Siemens AG
- Spirent Communications plc
- Supermicro(Super Micro Computer Inc.)
- Corning Incorporated
- CommScope Holding Co.
- Zayo Group
- Equinix Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom data center networking market size is expected to grow from USD 1.35 billion in 2025 to USD 1.45 billion in 2026 and is forecast to reach USD 2.07 billion by 2031 at 7.41% CAGR over 2026-2031.
This report is Segmented by Component (Product and Services), End User( IT and Telecommunications, Banking, Financial Services and Insurance (BFSI), Government and Defense and More), Data Center Type (Colocation, Hyperscalers/Cloud Service Providers, Edge/Micro Data Centers), by Bandwidth (<=10 GbE, 25-40 GbE and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Data Center Networking Market Trends and Insights
Surge in AI/ML and HPC driving 400/800 G upgrades
Rising generative-AI clusters require ultra-low-latency fabrics that traditional 10/25 G links cannot sustain. NVIDIA's Spectrum-X platform posts 1.6 X throughput gains versus prior Ethernet fabrics, while Arista's 7060X6 AI Leaf and 7800R4 AI Spine supply up to 51.2 Tbps and 460 Tbps, respectively, to meet pod-level aggregation demand.Meta's adoption of distributed 400 G switches further demonstrates hyperscalers' shift to deeper leaf-spine tiers that shorten east-west paths and minimize tail-flow latency. Cisco's decision to embed Silicon One ASICs inside NVIDIA's Ethernet stack exemplifies convergence between merchant silicon and AI-centric software pipelines that enterprises now consider a prerequisite for future readiness.
Government CNI status and GBP 14 billion AI plan catalyzing spend
The September 2024 CNI designation grants data-center operators priority access to planning and security support, directly unlocking record capital pledges such as Vantage's GBP 12 billion (USD 16.47 billion) multi-campus build and Nscale's USD 2.5 billion sovereign AI facility. The Action Plan also inaugurates AI Growth Zones with dedicated power-allocation corridors, starting in Culham, which accelerates permit approvals that historically delayed capacity. A twentyfold expansion in public compute by 2030, including a GBP 750 million (USD 1029.15 million) Scottish supercomputer, underpins multi-year demand for 800 G interconnects across public-sector and academia workloads.
Grid-power constraints in South-East England
National Grid warns data-center electricity demand could rise sixfold this decade, yet the capital's transmission corridors already operate near capacity. A recent Secretary of State refusal for a West London green belt campus highlights how planning curbs add to grid scarcity, prompting shifts to East London's Romford, where Green Mountain's 30 MW project secured faster hookups. Ofgem's queue-reform program may shave connection wait times, but meaningful substation builds require multi-year cycles, tempering near-term rollout velocities.
Other drivers and restraints analyzed in the detailed report include:
- Cloud and hybrid-multi-cloud traffic explosion
- Sustainability push for spine-leaf architectures
- Cost and lead-time spikes for 800 G optics/ASICs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Products held 76.20% of the United Kingdom data center networking market in 2025, reflecting entrenched demand for switches, routers, application delivery controllers, security appliances, and optical interconnects that anchor physical infrastructure. Cisco's Nexus 9364E-SG2 64-port 800 G switch exemplifies hardware tuned for AI-scale clusters, boasting 51.2 Tbps bandwidth and sizable on-die buffers to mask microbursts. Storage area networks now transition to NVMe-over-Fabrics, while security gateways embed AI-driven inspection engines capable of decrypt-at-line-rate, keeping hardware demand buoyant.
The services segment is smaller yet set for 7.55% CAGR as enterprises outsource design, integration, and managed operations of complex AI fabrics. Consulting firms deploy software-defined controllers such as Cisco ACI or VMware NSX to automate policy across hybrid clouds, whereas open-source OpenDaylight appeals to firms pursuing vendor-agnostic postures. Adoption of silicon-photonics optics like Coherent's 2X400 G-FR4 Lite transceiver further nudges organisations to rely on specialist service providers for optical-layer tuning and lifecycle management.
IT and telecom operators commanded 36.80% share of the United Kingdom data center networking market size in 2025 owing to continual refresh cycles that sustain broadband and cloud service quality. Banks and insurers also invest heavily; Starling Bank's use of Digital Realty interconnects underpins mobile-only operations with sub-20 millisecond transaction latency.
Manufacturing posts the fastest 7.95% CAGR to 2031 as Industry 4.0 ties operational-technology sensors to cloud analytics. Reckitt Group links factory assets via Azure IoT to derive predictive-maintenance insights that cut downtime 10% and energy loads 3%. Government, defence, healthcare, and media verticals likewise pivot to AI-assisted workflows yet trail manufacturing's velocity because of regulatory procurement cycles.
Complete Report Scope:
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- Less than or Equal to 10 GbE
- 25-40 GbE
- 50-100 GbE
- Greater than 100 GbE
List of Companies Covered in this Report:
- Arista Networks Inc.
- Broadcom Inc.
- Cisco Systems Inc.
- Dell Technologies Inc.
- Extreme Networks Inc.
- Hewlett Packard Enterprise (HPE)
- Huawei Technologies Co. Ltd.
- IBM Corporation
- Intel Corporation
- Juniper Networks Inc.
- Lenovo Group Ltd.
- Marvell Technology Group
- NEC Corporation
- NVIDIA Corporation (incl. Cumulus)
- Nokia Corporation
- Schneider Electric SE
- Siemens AG
- Spirent Communications plc
- Supermicro (Super Micro Computer Inc.)
- Corning Incorporated
- CommScope Holding Co.
- Zayo Group
- Equinix Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in AI/ML and HPC driving 400/800 G upgrades
- 4.2.2 Government CNI status and GBP 14 billion AI plan catalyzing spend
- 4.2.3 Cloud and hybrid-multi-cloud traffic explosion
- 4.2.4 Sustainability push for spine-leaf architectures
- 4.2.5 Regional edge DC build-out outside London
- 4.2.6 Silicon-photonic 1.6 T Ethernet roadmap
- 4.3 Market Restraints
- 4.3.1 Grid-power constraints in South-East England
- 4.3.2 Cost and lead-time spikes for 800 G optics/ASICs
- 4.3.3 New energy-/water-use disclosure rules
- 4.3.4 Hyperscaler egress fees and lock-in curb open networking
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Products
- 5.1.1.1 Ethernet Switches
- 5.1.1.2 Routers
- 5.1.1.3 Storage Area Network (SAN)
- 5.1.1.4 Application Delivery Controllers (ADC)
- 5.1.1.5 Network Security Appliances
- 5.1.1.6 Software-Defined Networking (SDN) Controllers
- 5.1.1.7 Optical Interconnects
- 5.1.2 Services
- 5.1.2.1 Installation and Integration
- 5.1.2.2 Training and Consulting
- 5.1.2.3 Support and Maintenance
- 5.1.2.4 Managed Network Services
- 5.1.1 Products
- 5.2 By End-User
- 5.2.1 IT and Telecommunications
- 5.2.2 Banking, Financial Services and Insurance (BFSI)
- 5.2.3 Government and Defense
- 5.2.4 Media and Entertainment
- 5.2.5 Healthcare and Life Sciences
- 5.2.6 Manufacturing and Industrial
- 5.2.7 Other End-Users
- 5.3 By Data-Center Type
- 5.3.1 Colocation
- 5.3.2 Hyperscalers/Cloud Service Providers
- 5.3.3 Edge/Micro Data Centers
- 5.4 By Bandwidth
- 5.4.1 Less than or Equal to 10 GbE
- 5.4.2 25-40 GbE
- 5.4.3 50-100 GbE
- 5.4.4 Greater than 100 GbE
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Arista Networks Inc.
- 6.4.2 Broadcom Inc.
- 6.4.3 Cisco Systems Inc.
- 6.4.4 Dell Technologies Inc.
- 6.4.5 Extreme Networks Inc.
- 6.4.6 Hewlett Packard Enterprise (HPE)
- 6.4.7 Huawei Technologies Co. Ltd.
- 6.4.8 IBM Corporation
- 6.4.9 Intel Corporation
- 6.4.10 Juniper Networks Inc.
- 6.4.11 Lenovo Group Ltd.
- 6.4.12 Marvell Technology Group
- 6.4.13 NEC Corporation
- 6.4.14 NVIDIA Corporation (incl. Cumulus)
- 6.4.15 Nokia Corporation
- 6.4.16 Schneider Electric SE
- 6.4.17 Siemens AG
- 6.4.18 Spirent Communications plc
- 6.4.19 Supermicro (Super Micro Computer Inc.)
- 6.4.20 Corning Incorporated
- 6.4.21 CommScope Holding Co.
- 6.4.22 Zayo Group
- 6.4.23 Equinix Inc.
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 全球資料中心網路市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 北美資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)南美洲資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)印度資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)義大利資料中心網路:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)資料中心網路:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)